Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Get SaaSFrame Pro
Monthly
$18
Quarterly
$48
Yearly
$180
Upgrade to access this feature
Browse all screens & flows
Filter and search screens & flows
Access Figma files
Access mobile versions
Bookmark screens & flows
Join now
Search in screen.
Type any word or phrase and find every screen that mentions it.
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.

Legal & Compliance
Lifestyle
Database
AI
Scheduling
Human Resources
Presentation
Learning
Calendar
Marketing
Communication
Tech
Mailing
Hardware
Social
Data & Analytics
Product
Productivity
Website Builder
Customer Support
CRM
Sales & Revenue
Design
Operations
Automation
Collaboration
Finance













Figma file available
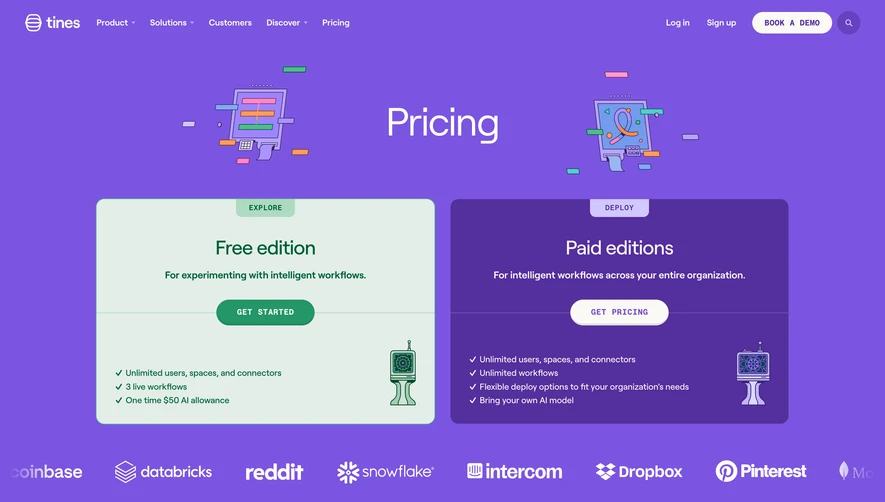
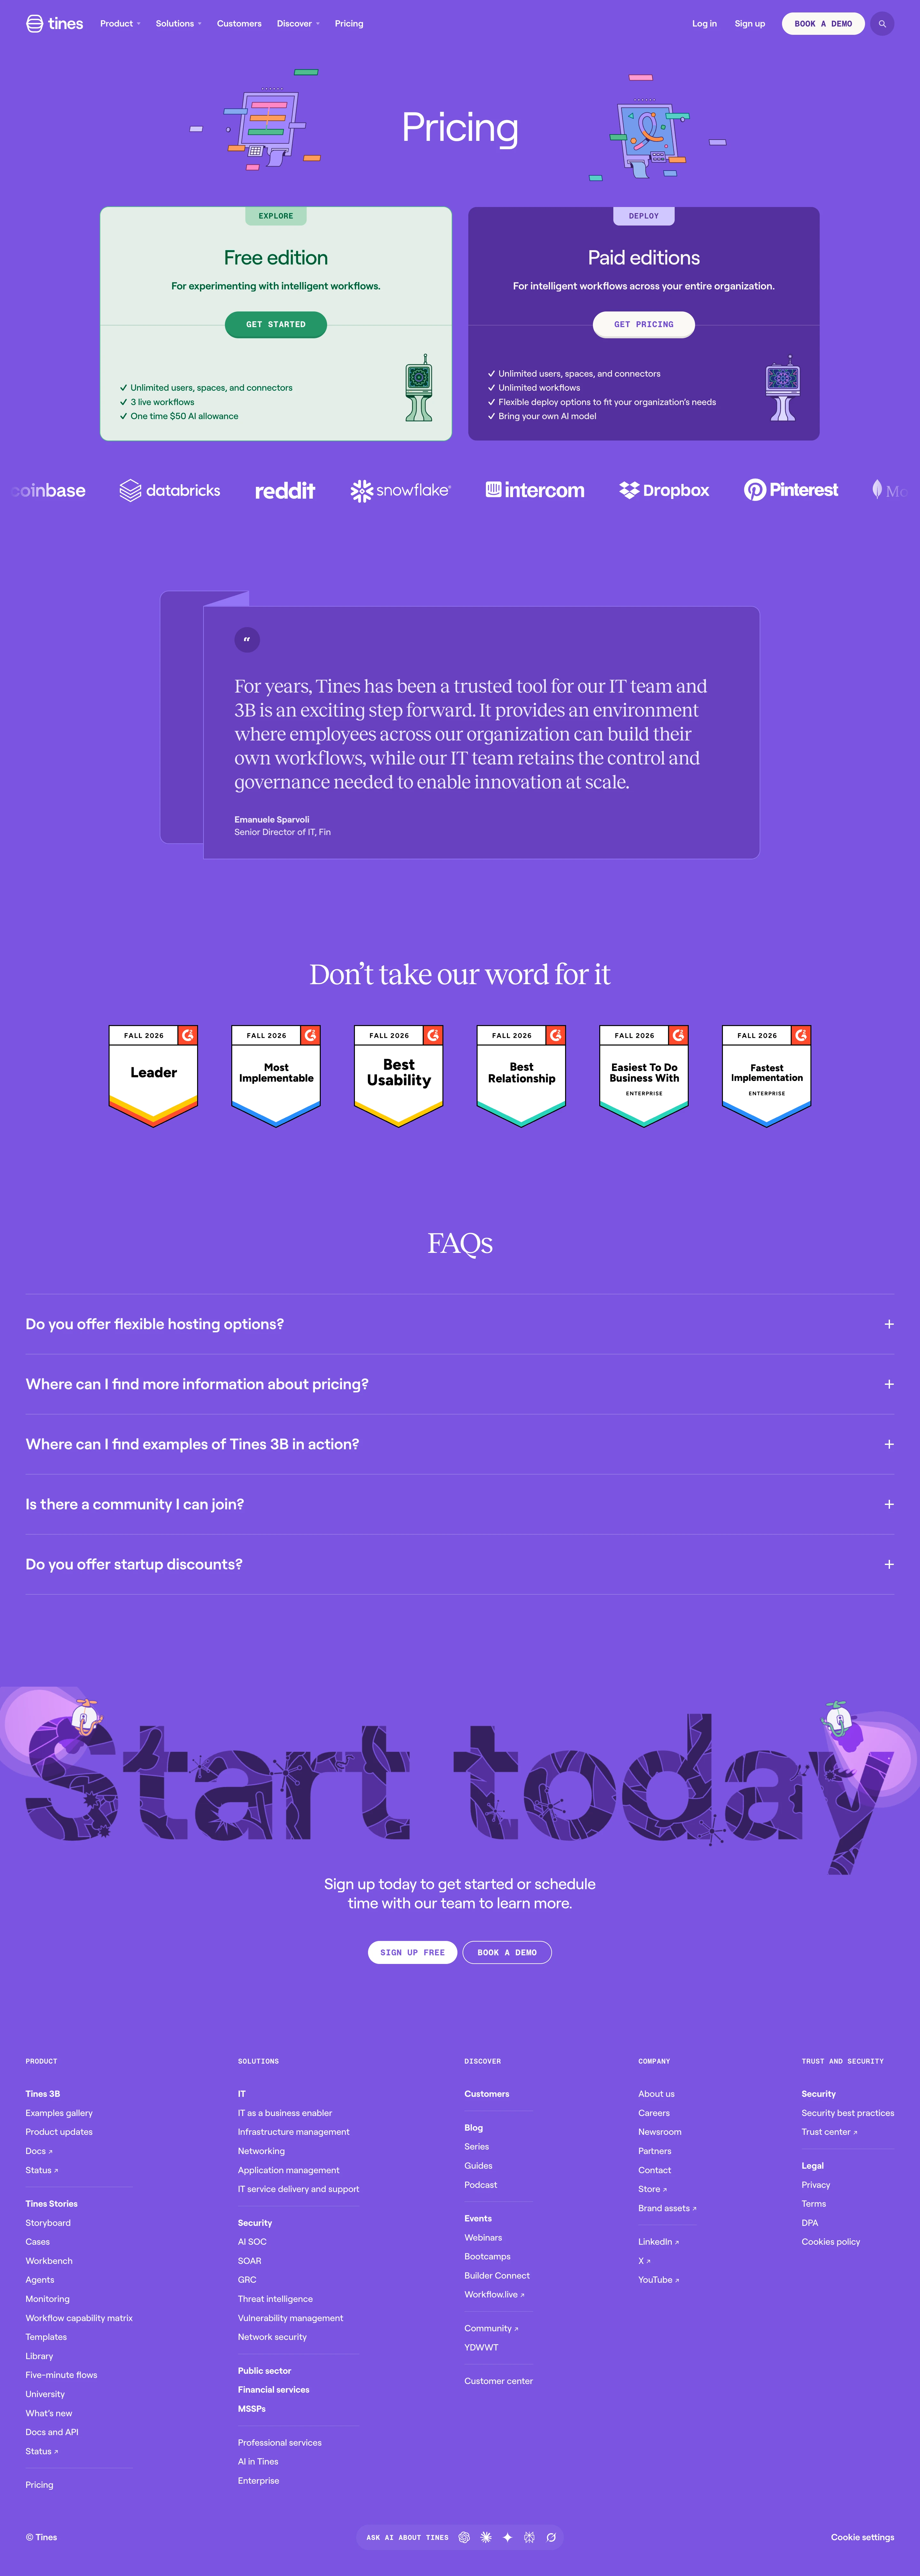
Pricing Page
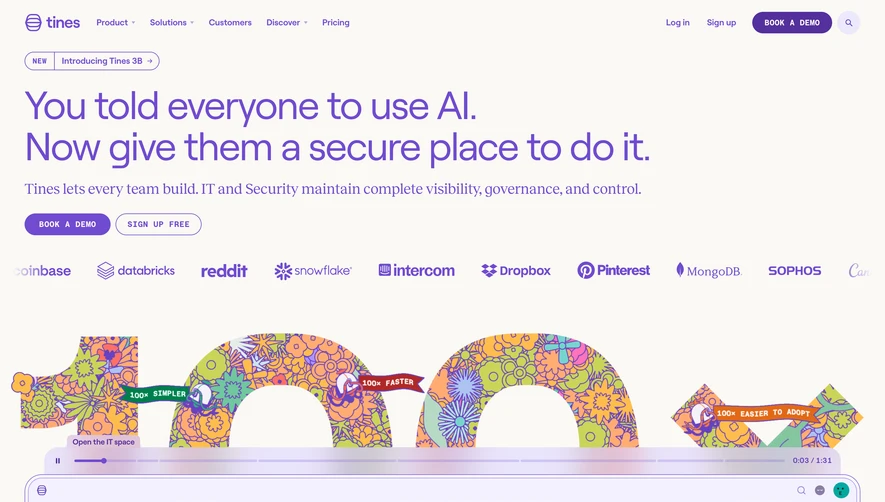
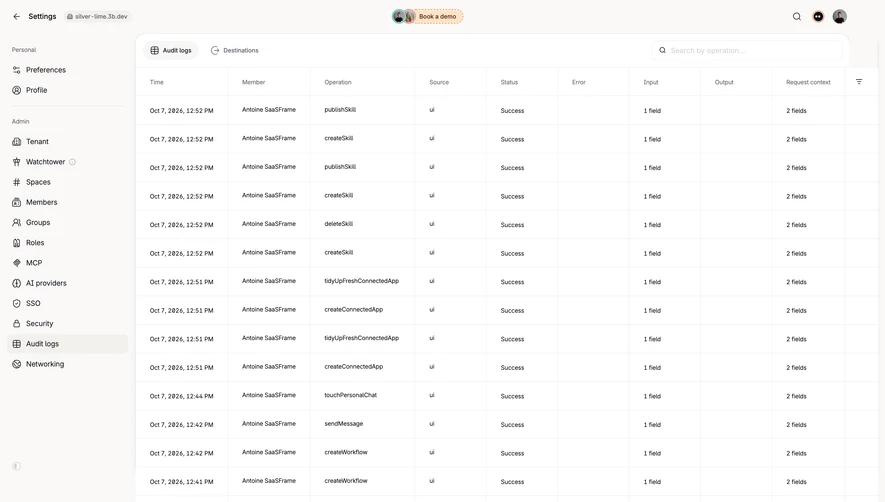
Tines
Pricing Page
Marketing
• tines Product • Pricing Free edition For experimenting with Intelligent workno Paid editions oinbase - databricks reddit * snowflake • intercom Dropbox ® Pinterest For years, Tines has been a trusted tool for our IT team and 3B is an exciting step forward. It provides an environment where employees across our organization can build their own workflows, while our IT team retains the control and governance needed to enable innovation at scale. Don't take our word for it FAQS Do you offer flexible hosting options? Where can I find more information about pricing? Where can I find examples of Tines 3B in action? Is there a community I can join? Do you offer startup discounts? Start today Sign up today to get started or schedule ume win our team to learn more
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
true
false

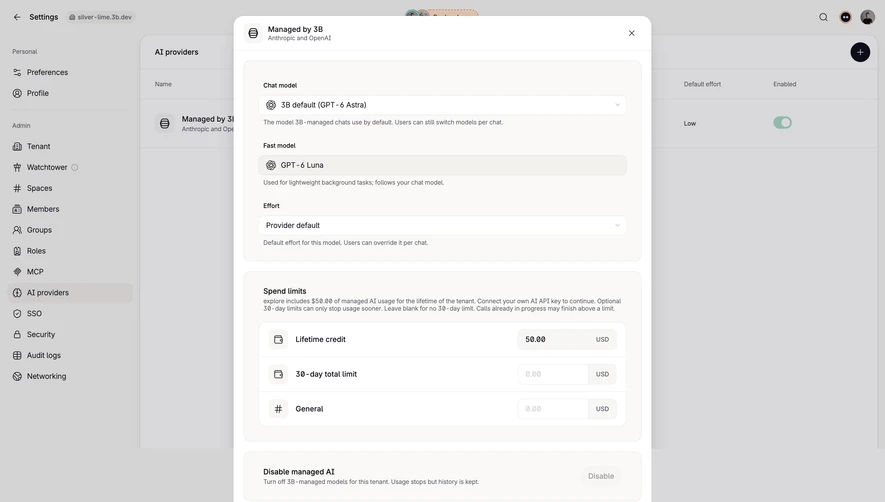
AI Model & Spend Settings
Tines
Settings
Product
< Settings M silver-lime.3b.dev Personal ° Preferences 8 Profile Admin A Tenant # Watchtower O # Spaces Members Al Groups a Roles @ MCP AI providers • SSO • Security • Audit logs Networking AI providers Name Managed by 3l Anthropic and Ope Managed by 3B Anthropic and OpenAI Chat model G 3B default (GPT-6 Astra) Default effort Low Fast model GPT - 6 Luna Used for lightweight background tasks; follows your chat model. Effort Provider default Default effort for this model. Users can override it per chat. Spend limits explore includes $50.00 of managed AI usage for the lifetime of the tenant. Connect your own AI API key to continue. Optional 30-day limits can only stop usage sooner. Leave blank for no 30-day limit. Calls already in progress may finish above a limit. Lifetime credit 50.00 # 30 - day total limit General 0.00 USD USD USD Disable managed AI Turn off 3B-managed models for this tenant. Usage stops but history is kept. Disable Done Enabled
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false
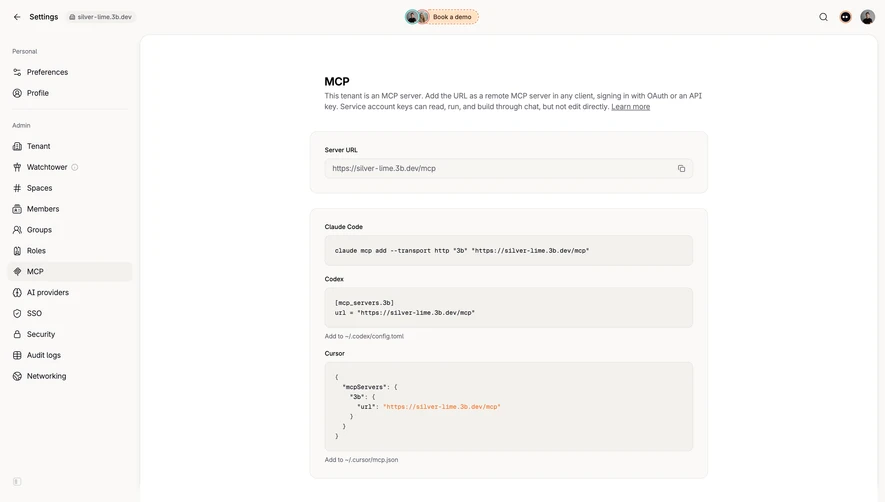
MCP Connection Setup
Tines
Integrations
Product
< Settings da silver-lime. 3b.dev Book a demo Personal ° Preferences ® Profile MCP This tenant is an MCP server. Add the URL as a remote MCP server in any client, signing in with OAuth or an API key. Service account keys can read, run, and build through chat, but not edit directly. Learn more Admin da Tenant # Watchtower O # Spaces Members &i Groups [* Roles @ MCP @ AI providers • SSO • Security • Audit logs @ Networking Server URL https://silver-lime.3b.dev/mcp Claude Code claude mcp add --transport http "3b" "https://silver-lime.3b.dev/mcp" Codex [mcp_servers.3b] url = "https://silver-lime.3b.dev/mcp" Add to ~/.codex/confiq.toml Cursor "mcpServers" : "Зb": { "url". "https://silver-lime.3b.dev/mcp" Add to ~/.cursor/mcp.ison
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false

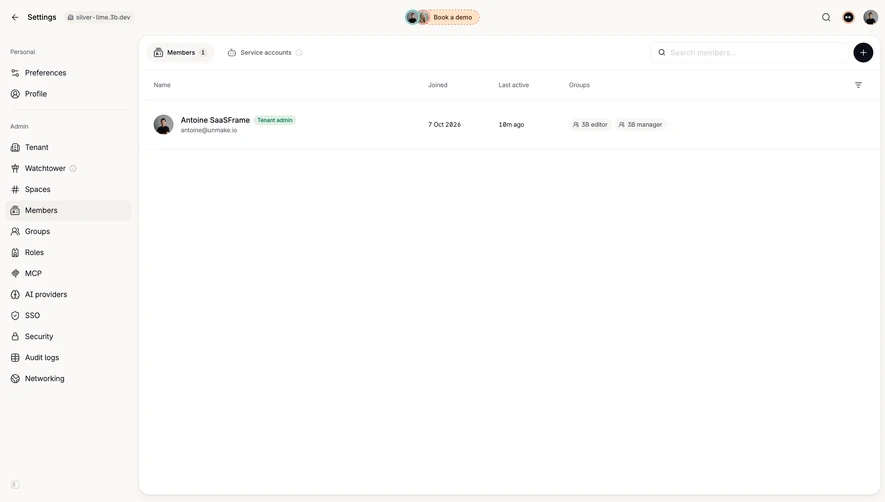
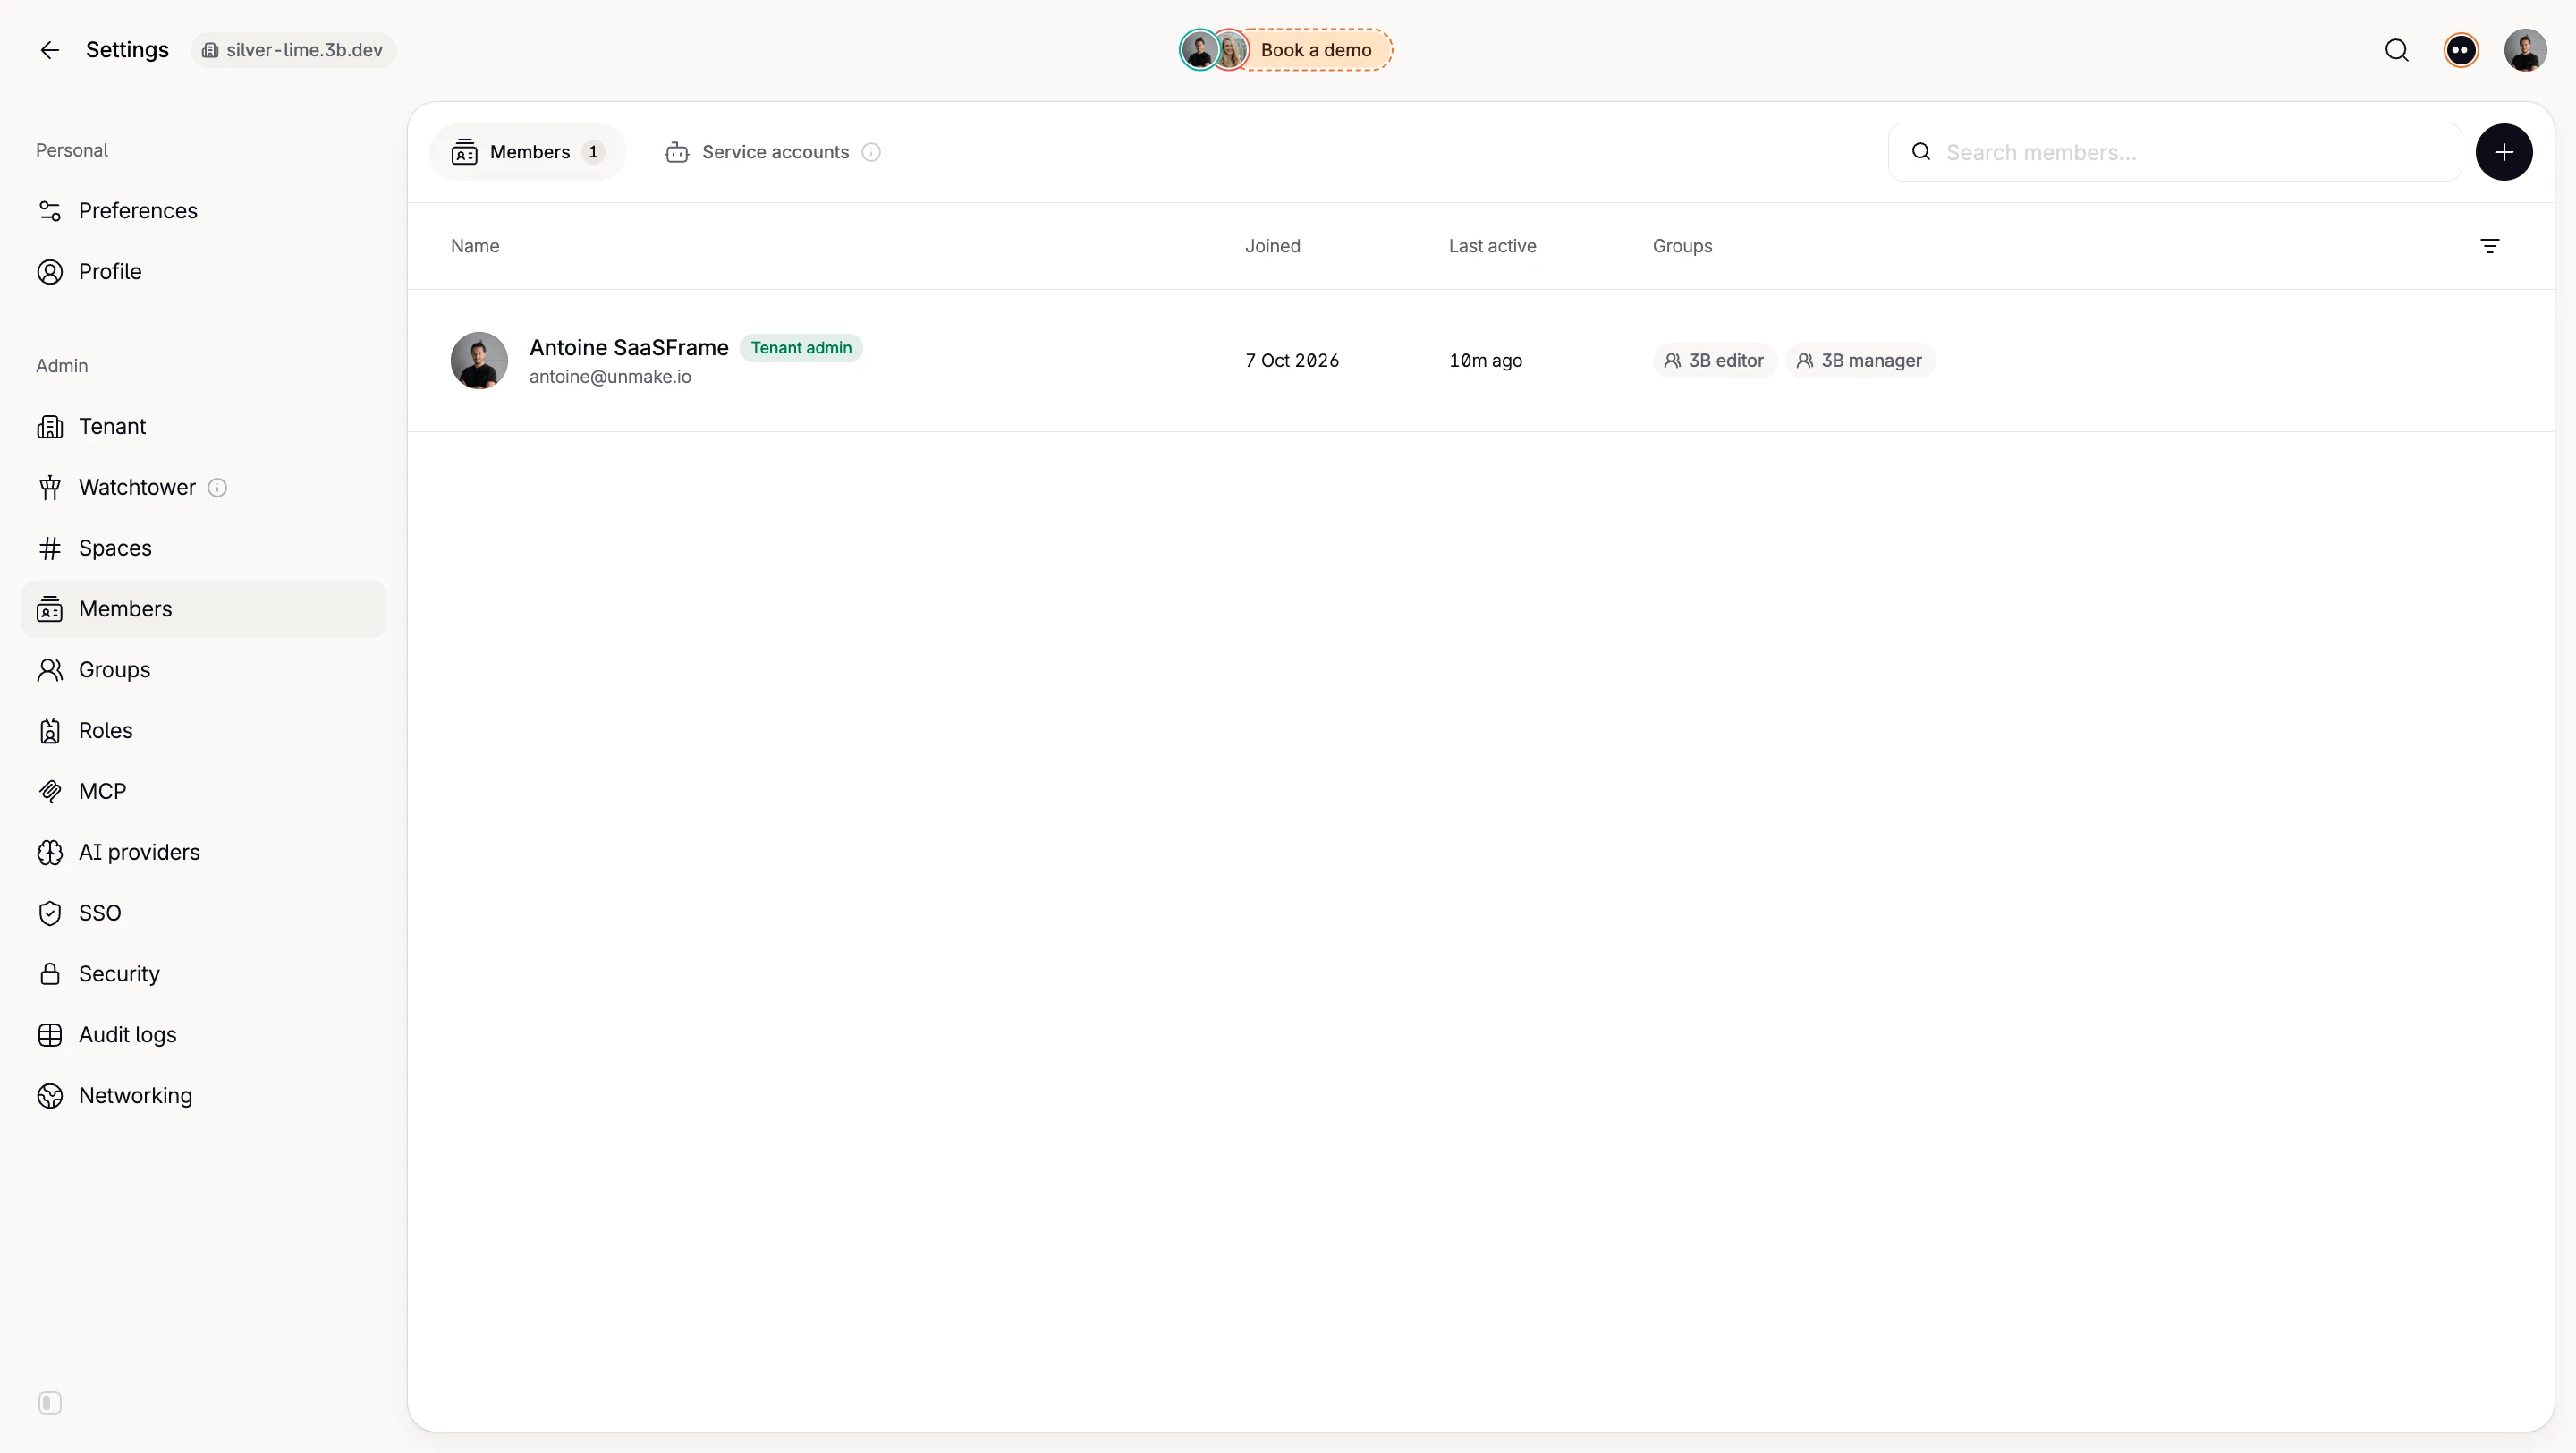
Workspace Members
Tines
Team Members
Product
< Settings @ silver-lime.3b.dev Personal ° Preferences ® Profile Admin dal Tenant # Watchtower O # Spaces Members Al Groups [* Roles • MCP # AI providers • SSO • Security • Audit logs Networking • Book a demo Members 1 Name & Service accounts O Joined Last active Antoine SaaSFrame Tenant admin [email protected] 7 Oct 2026 10m ago Q Search members... Groups & 3B editor & 3B manager
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false
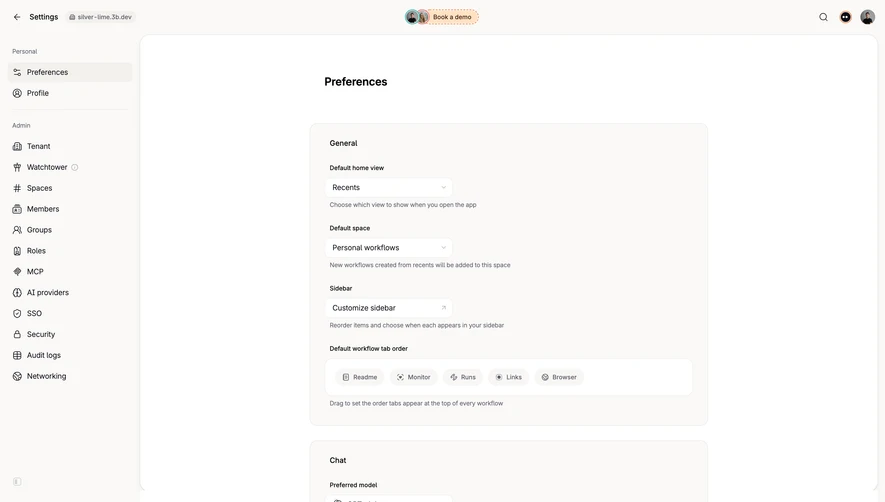
false

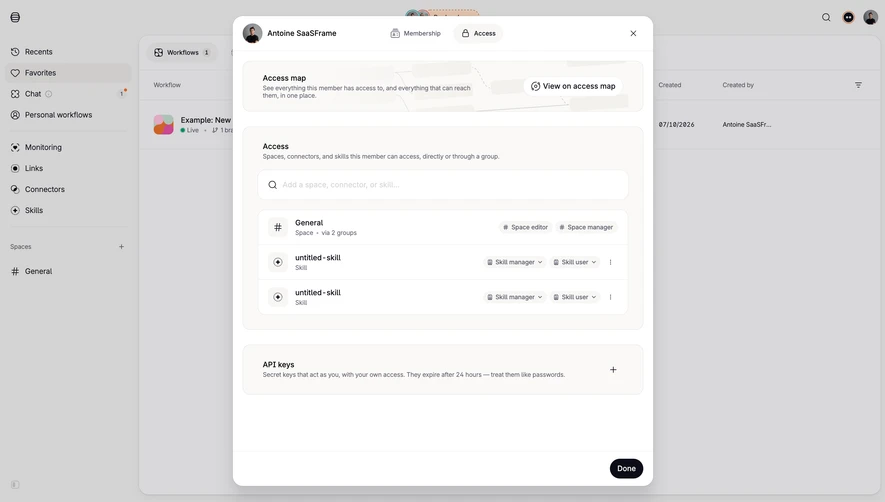
Member Access Permissions
Tines
Settings
Product
• Recents • Favorites & Chat O ® Personal workflows • Monitoring • Links • Connectors + Skills Spaces # General Antoine SaaSFrame a: Membership • Access • Workflows 1 Workflow Access map See everything this member has access to, and everything that can reach them, in one place. View on access map Created Example: New • Live • 1º 1 bra 07/10/2026 Access Spaces, connectors, and skills this member can access, directly or through a group. Q Add a spac # + General Space • via 2 groups untitled - skill Skill untitled - skill Skill # Space editor # Space manager ) Skill manager • ( Skill user v : (a) Skill manager v (a) Skill user v : API keys Secret keys that act as you, with your own access. They expire after 24 hours - treat them like passwords. + Done Created by Antoine SaaSFr...
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false
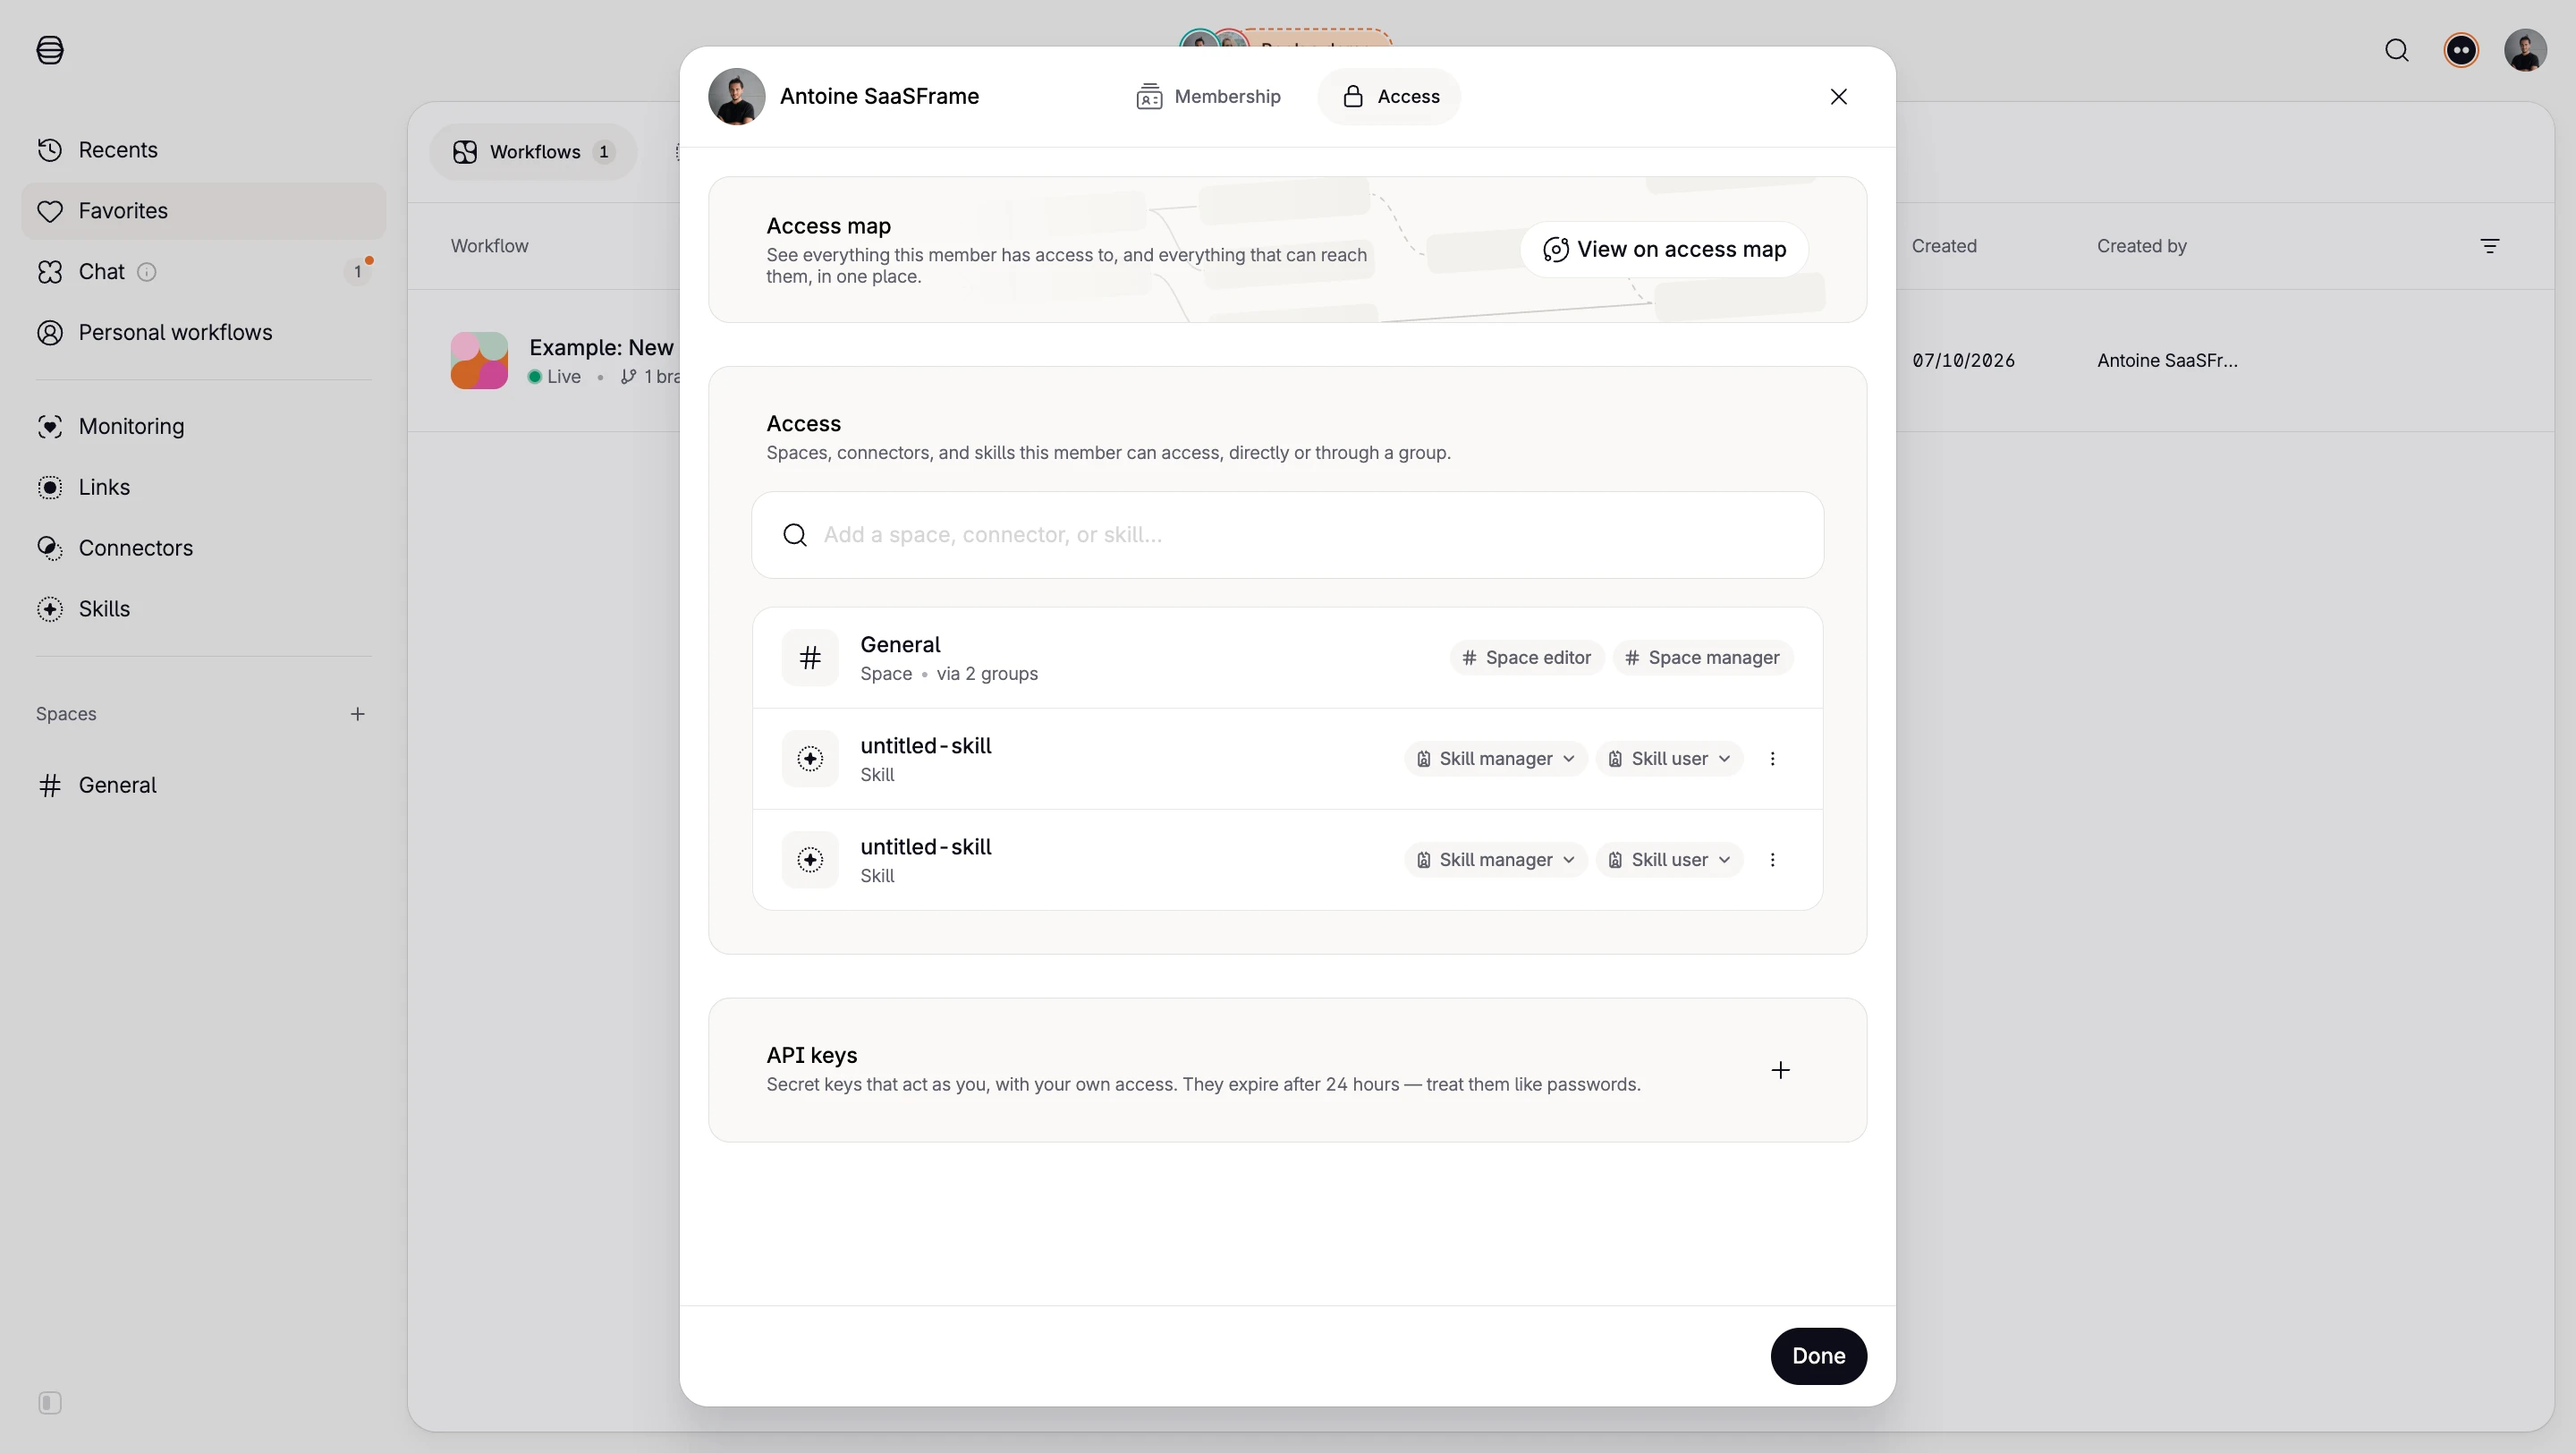
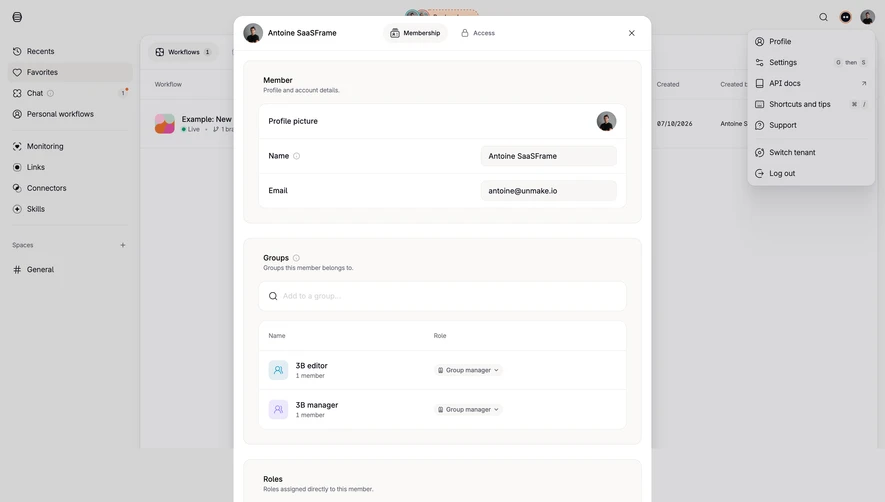
Member Profile & Roles
Tines
Settings
Product
Antoine SaaSFrame a Membership • Access 1 Recents • Favorites & Chat O ® Personal workflows • Monitoring • Links • Connectors + Skills Spaces # General • Workflows 1 Workflow Example: New • Live • 1º 1 bra Member Profile and account details. Profile picture Name O Email Created Created b 07/10/2026 Antoine S Antoine SaaSFrame [email protected] ® Profile - Settings API docs Shortcuts and tips ® Support Switch tenant G Log out G then S 26 1 Groups O Groups this member belongs to. Q Add to a group.... Name 3B editor 1 member 3B manager 1 member Role &a Group manager v & Group manager v Roles Roles assigned directly to this member. * Skill user 2 A Group manager 2 Skill manager 2 Admin Deactivate member Deactivates this member and signs them out immediately. You can reactivate them later. Deactivate member Done
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false

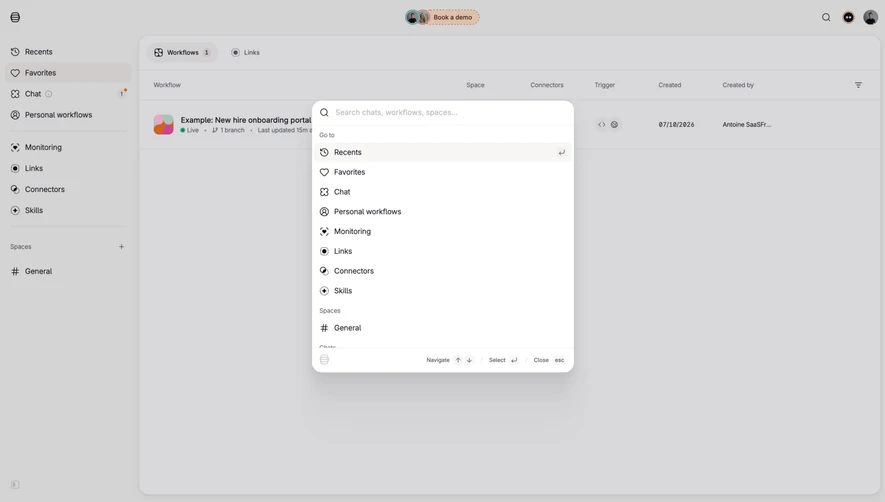
Command Palette
Tines
Search Modal
Product
F Recents • Favorites & Chat O 8 Personal workflows • Monitoring • Links • Connectors (+ Skills Spaces # General + 6 Workflows 1 • Links Workflow Example: New hire onboarding portal • Live • J 1 branch • Last updated 15m a Book a demo Space Connectors Trigger Created a Search chats, workflows, spaces... Go to + Recents • Favorites & Chat • Personal workflows • Monitoring • Links • Connectors + Skills Spaces # General <> Q 07/10/2026 Navigate 1 V / Select + / Close esc Created by Antoine SaaSFr...
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false

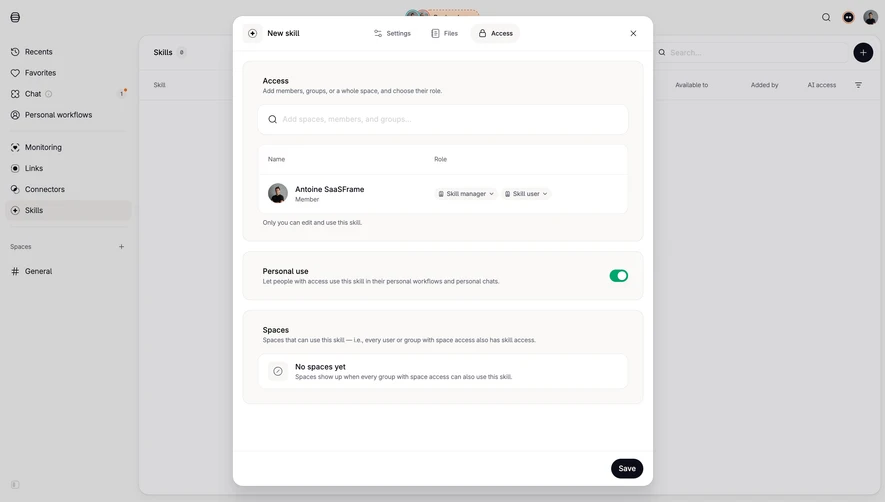
Skill Access Settings
Tines
Add & Edit
Product
New skill Settings = Files • Access • Recents • Favorites & Chat • ® Personal workflows Skills Q Search... Skill Access Add members, groups, or a whole space, and choose their role. Available to Added by AI access Q Add spaces, members, and groups... • Monitoring • Links • Connectors + Skills Name Role Antoine SaaSFrame Member Only you can edit and use this skill. * Skill manager • Skill user v Spaces # General Personal use Let people with access use this skill in their personal workflows and personal chats. Spaces Spaces that can use this skill — i.e., every user or group with space access also has skill access. No spaces yet Save
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false

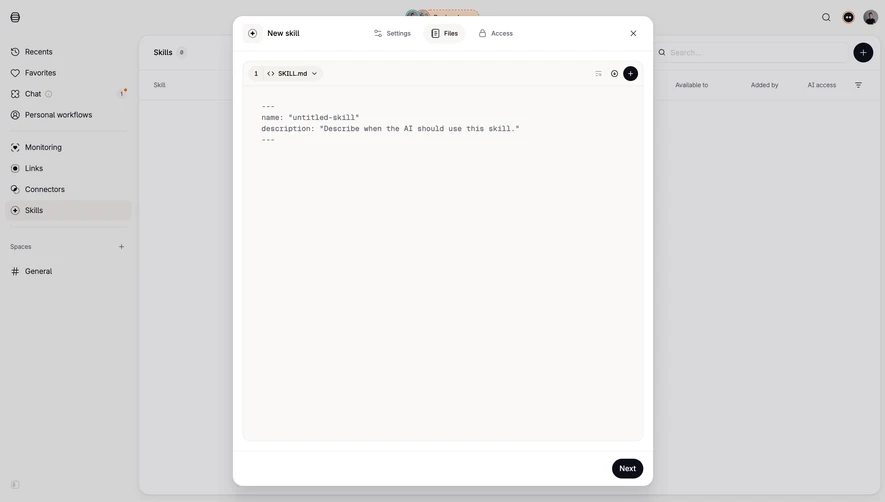
Skill Definition Editor
Tines
Text Editor
Product
• Recents • Favorites & Chat • ® Personal workflows Monitoring • Links • Connectors + Skills Spaces # General New skill ° Settings E Files 8 Access Skills o Q Search... 1 <> SKILL.md v Skill Available to Added by AI access name: 'untitled-skill" description: "Describe when the AI should use this skill." + Next
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false

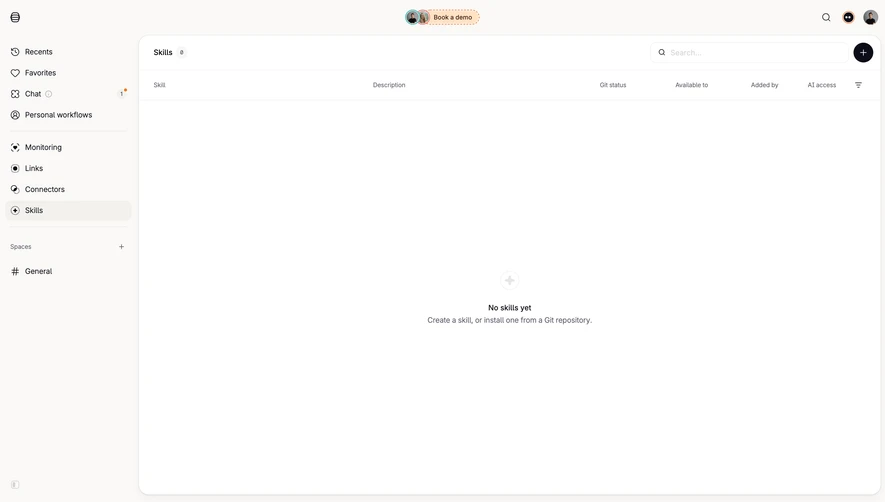
Empty Skills Library
Tines
Empty State
Product
• Recents • Favorites & Chat O ® Personal workflows • Monitoring • Links • Connectors + Skills Spaces # General + Skills o Skill Q Search... Description Git status Available to No skills yet Create a skill, or install one from a Git repository. Added by AI access
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false

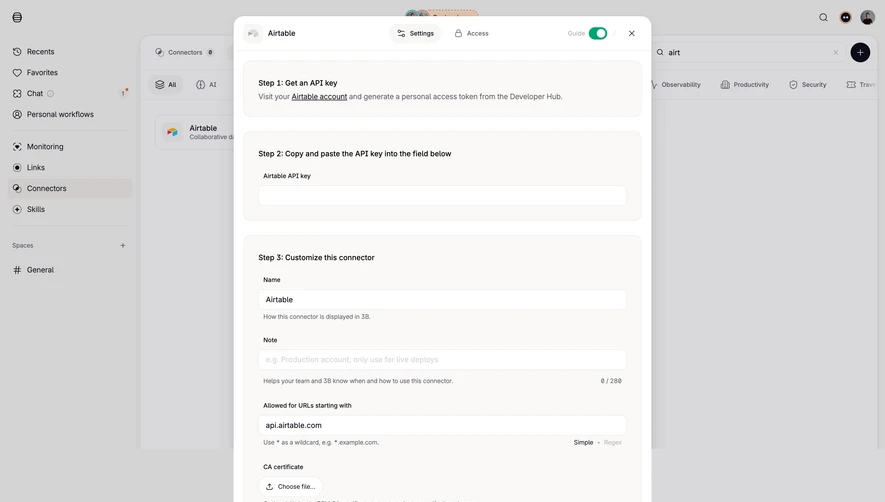
Anthropic Connector Setup
Tines
Add & Edit
Product
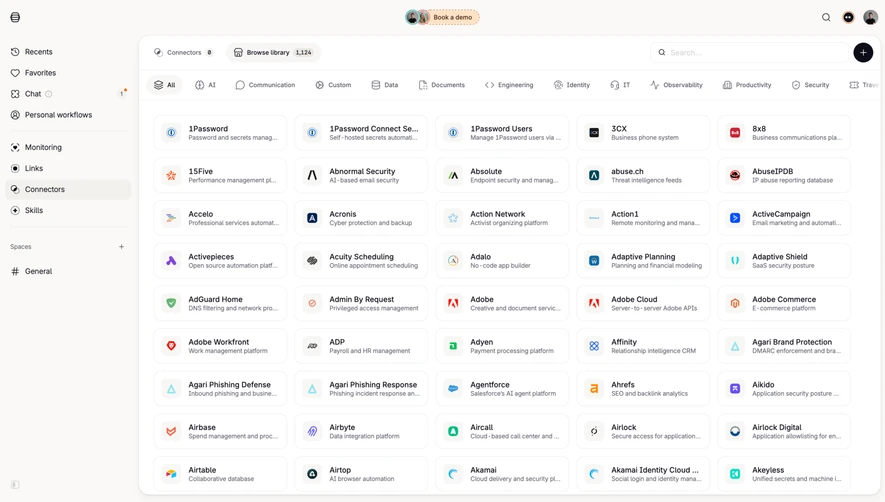
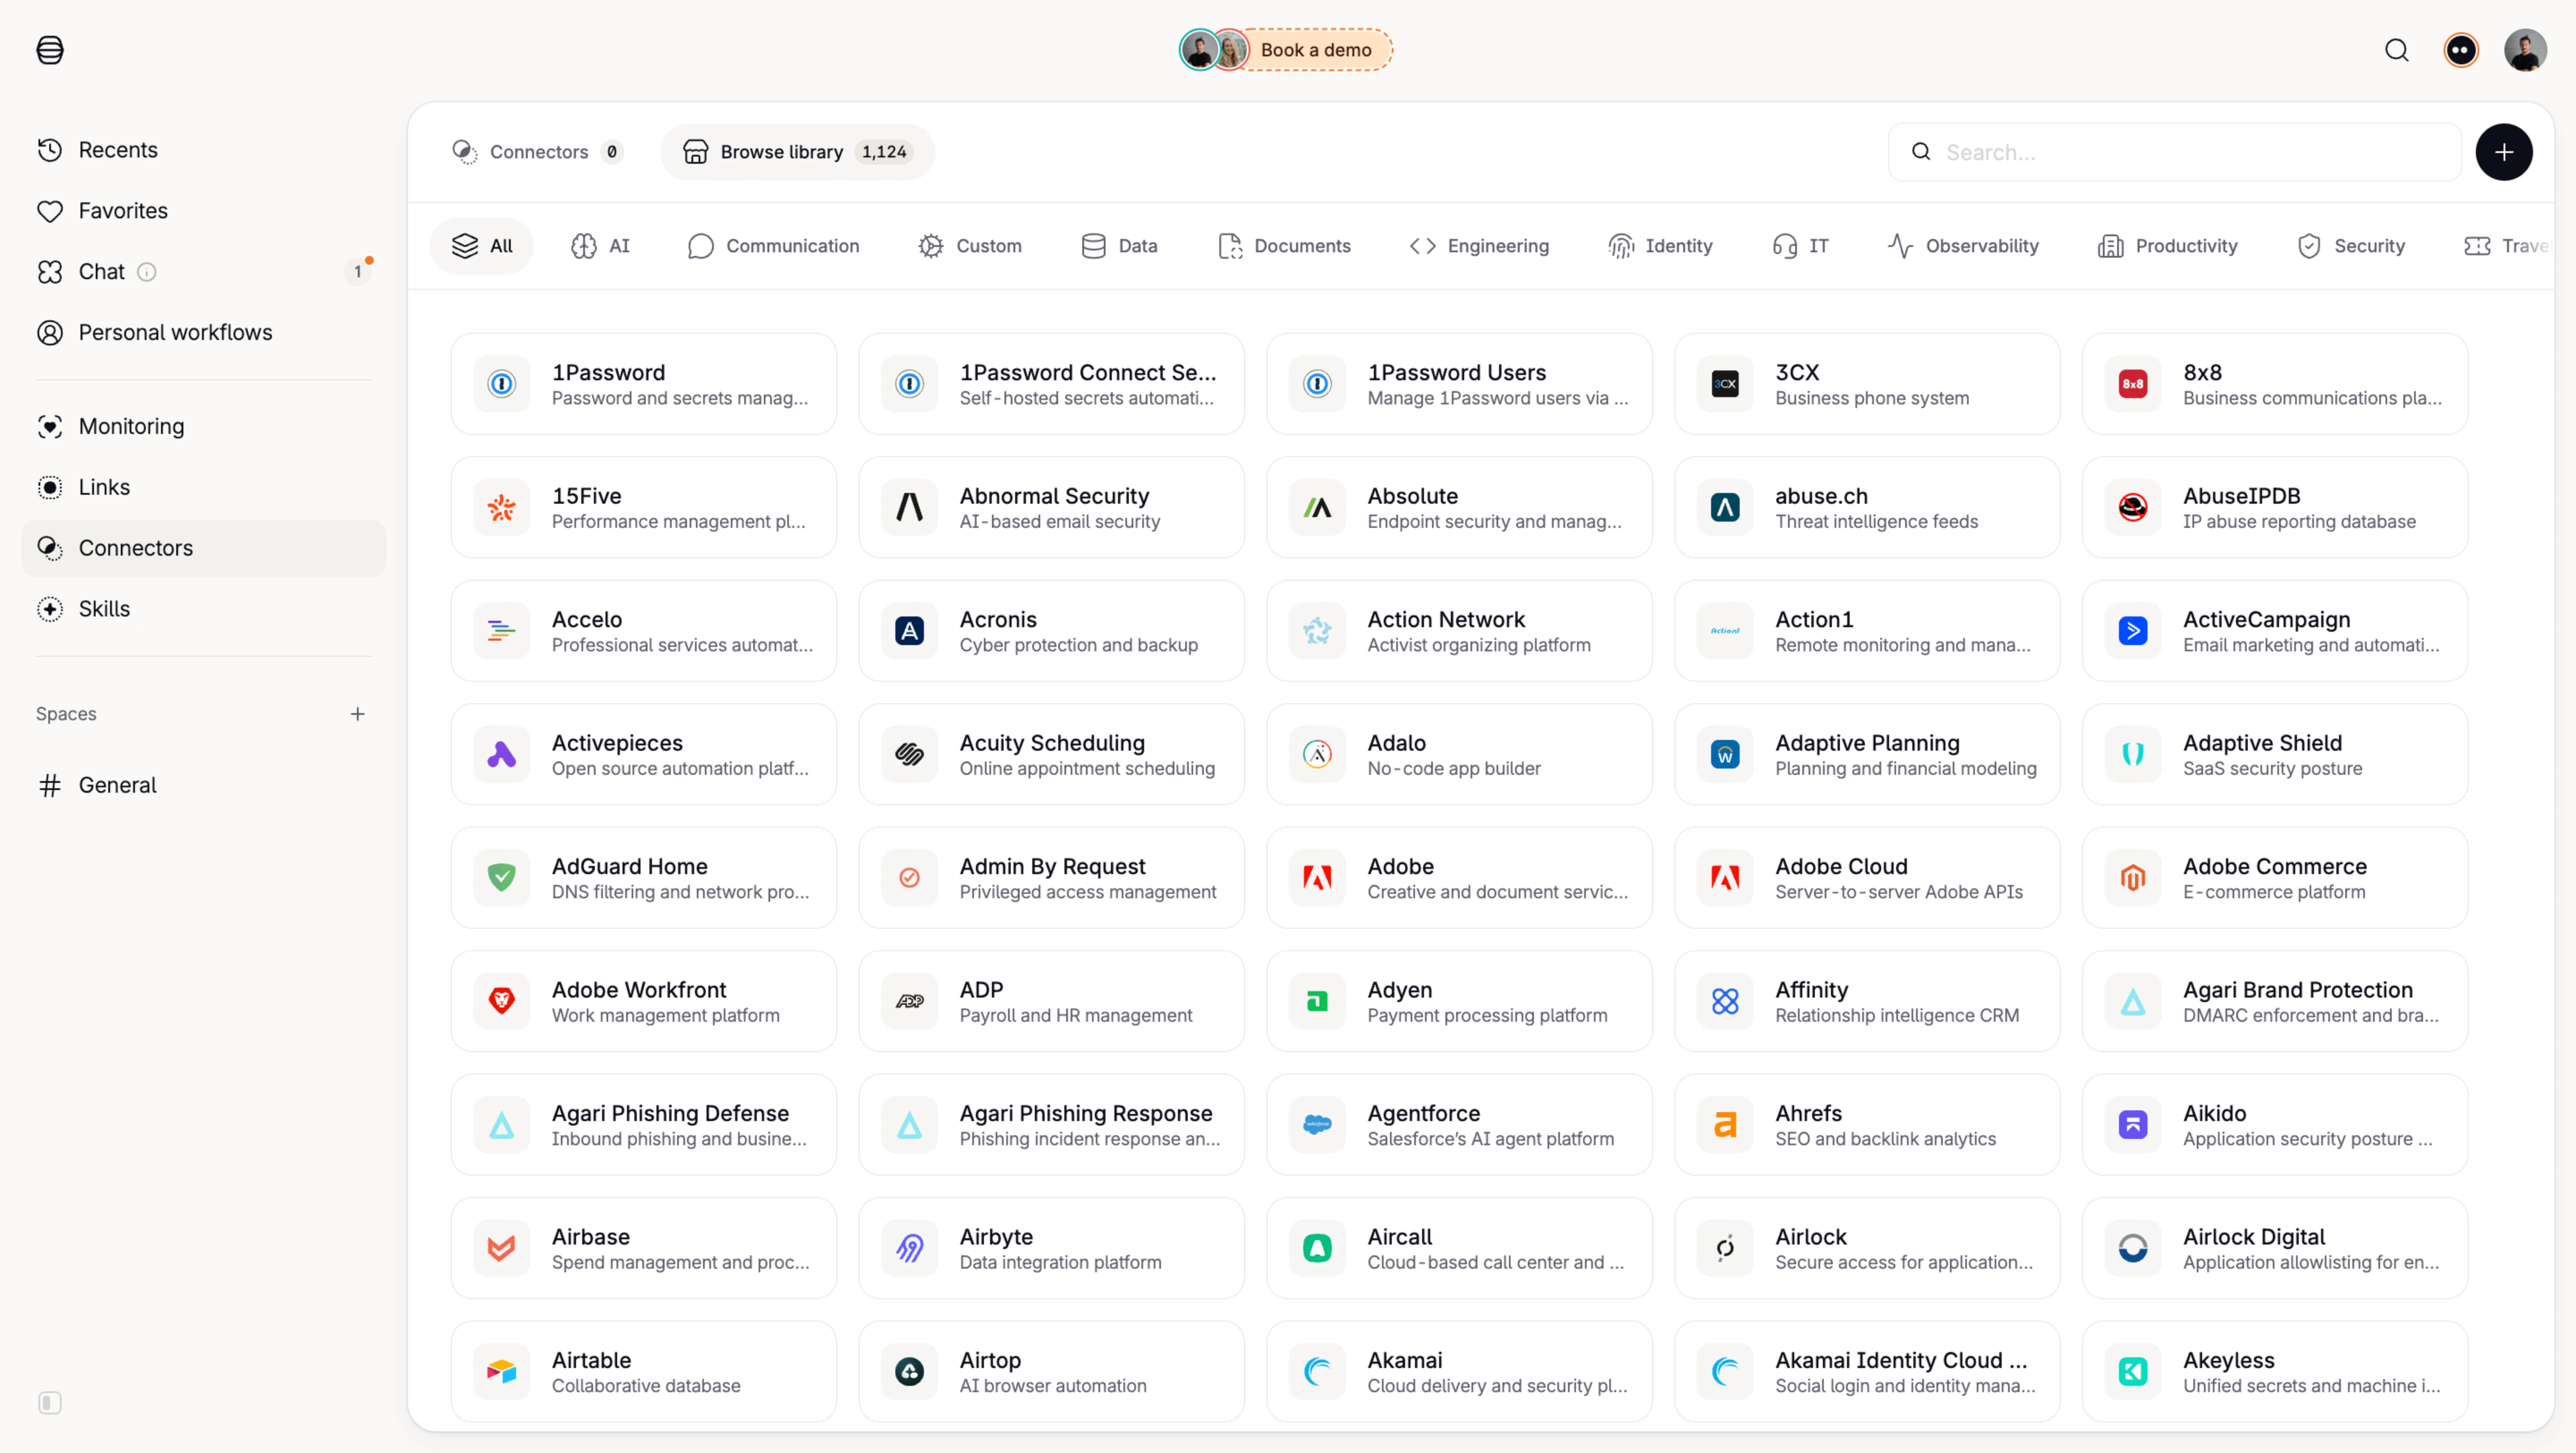
• Recents • Favorites & Chat O ® Personal workflows • Monitoring • Links • Connectors + Skills Spaces # General a Airtable ° Settings • Access Guide • • Connectors • S ALL # AI Airtable Collaborative da Q airt Observability Step 1: Get an API key Visit your Airtable account and generate a personal access token from the Developer Hub. dal Productivity • Security R Trave Step 2: Copy and paste the API key into the field below Airtable API key Step 3: Customize this connector Name Airtable How this connector is displayed in 3B. Note e.g. Production account, only use for live deploys 0/280 Allowed for URLs starting with Simple • Regex CA certificate I Choose file... Optional. Upload a PEM CA certificate to trust a private or self-signed server. • 3B Secure Untested C Next
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false

false
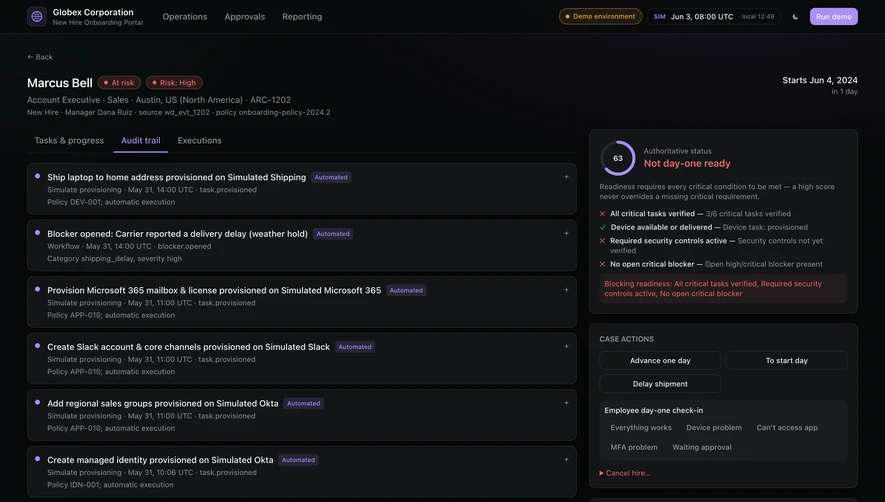
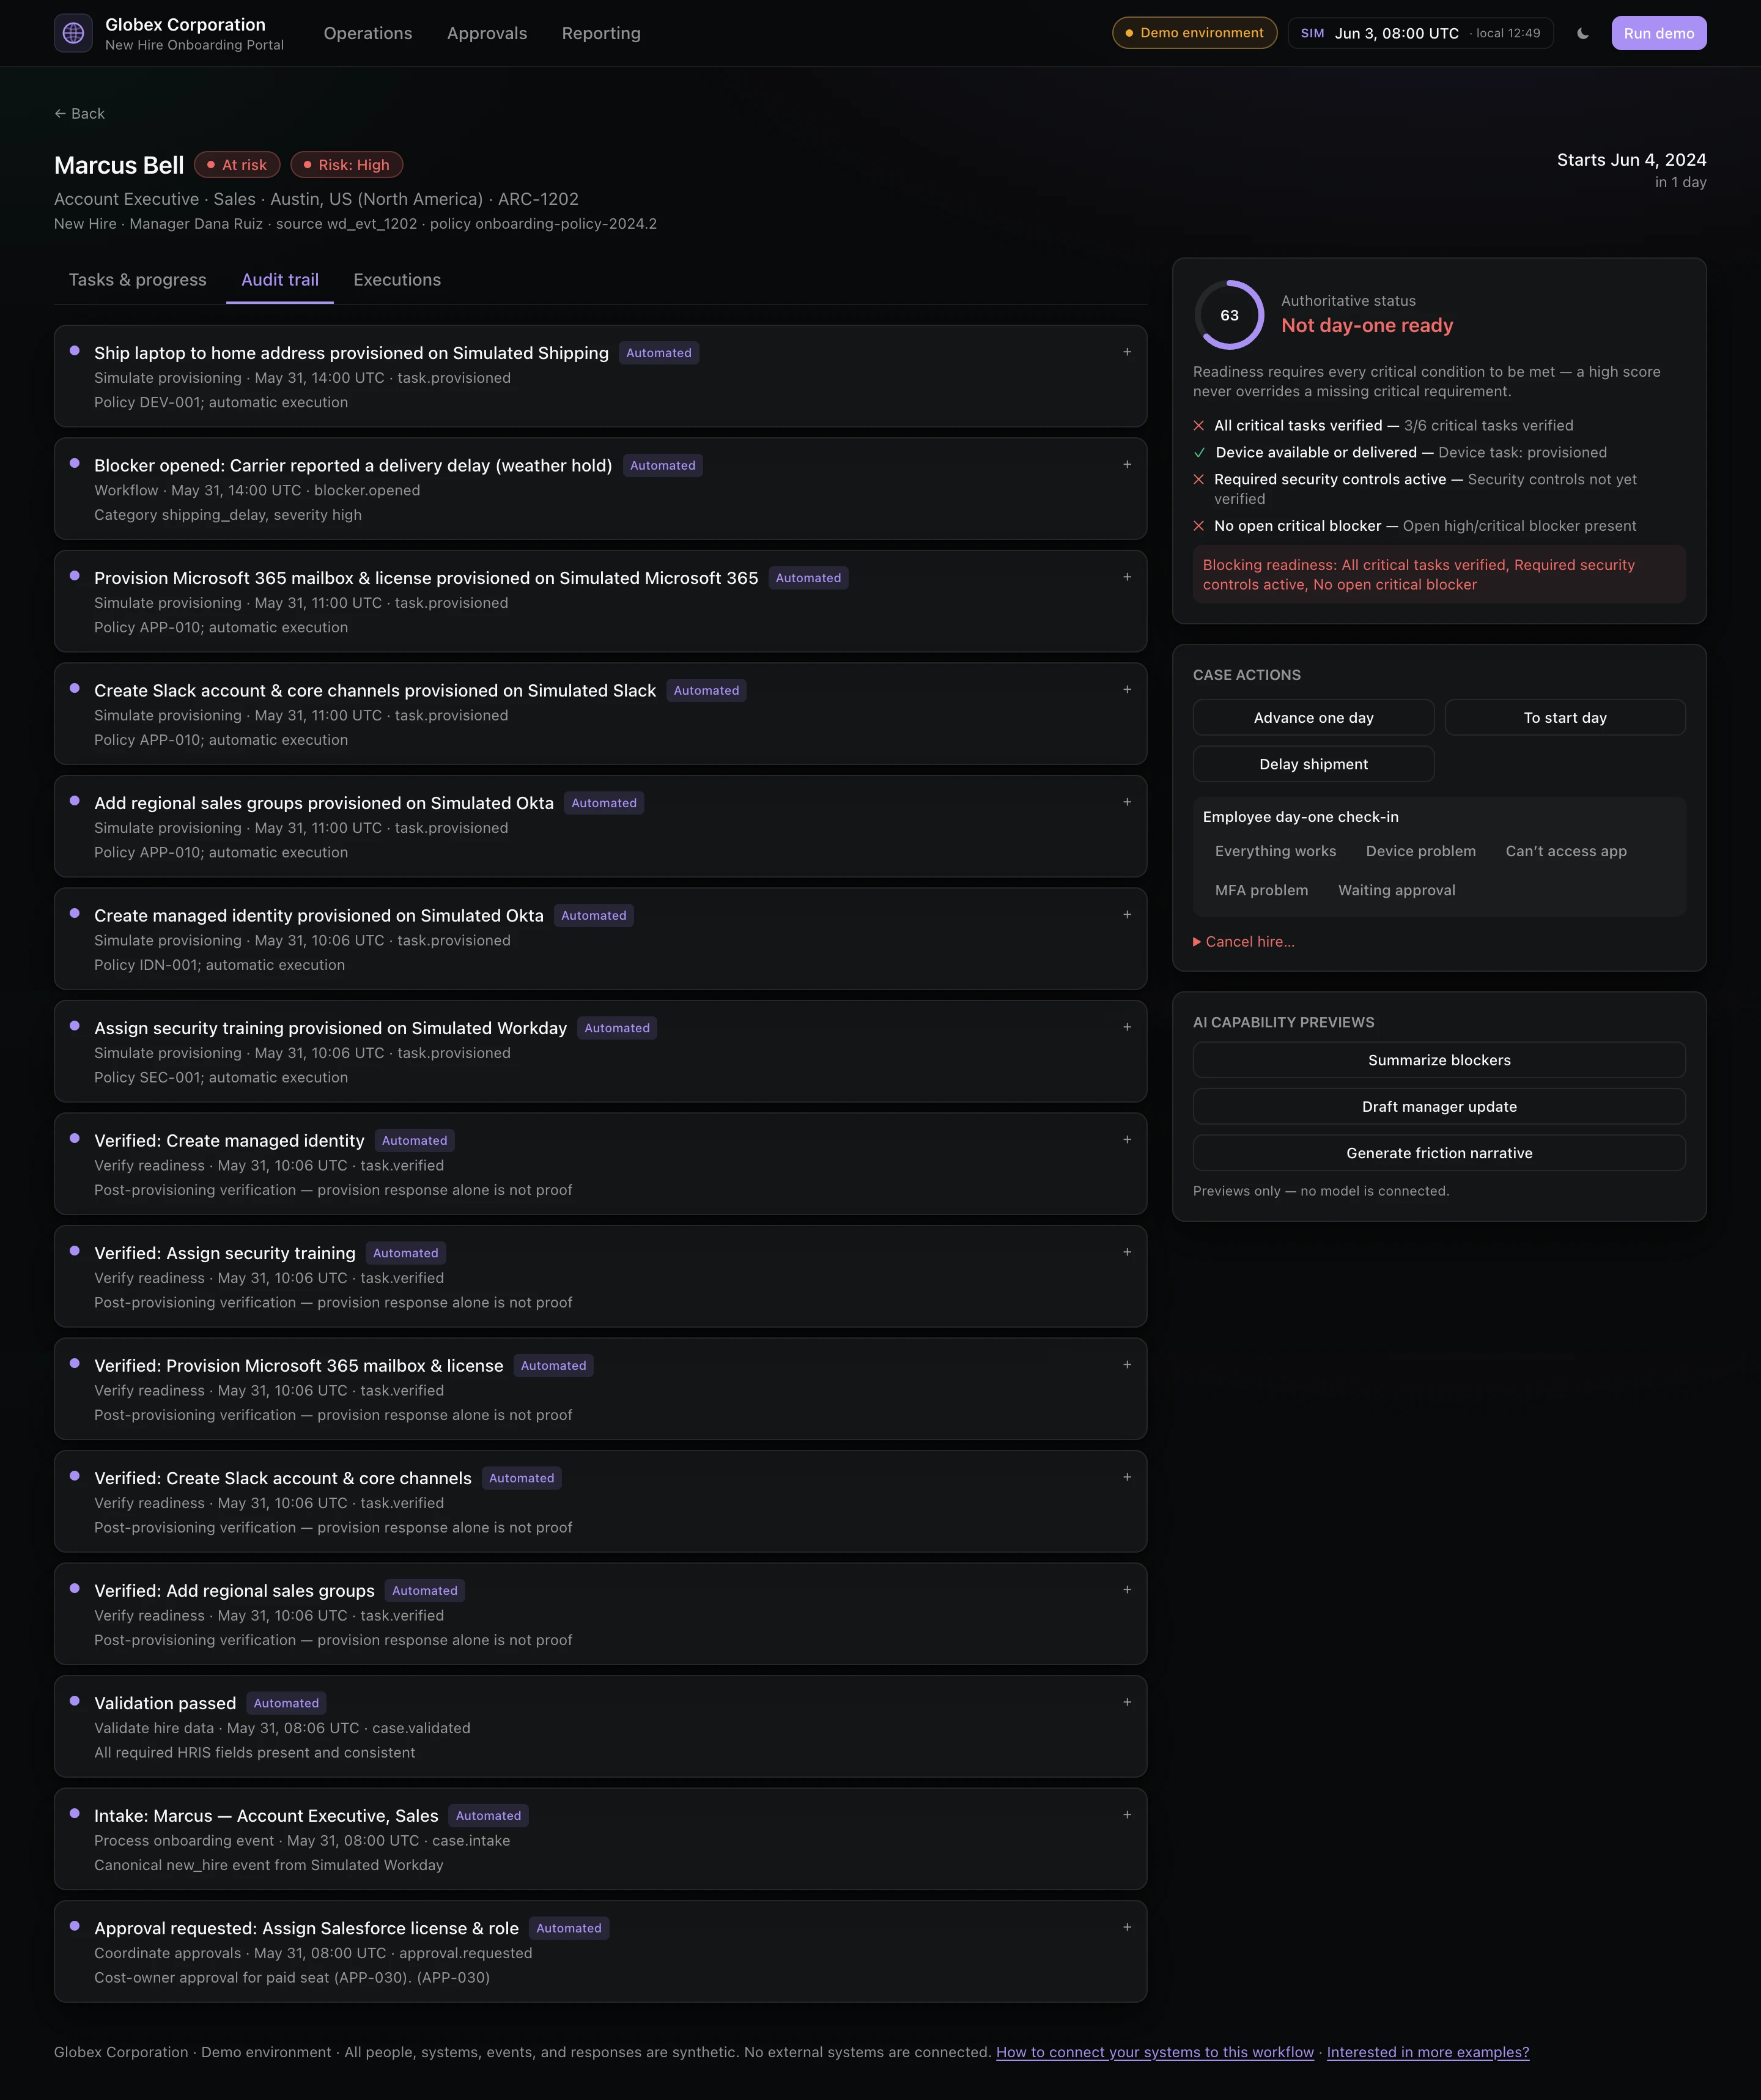
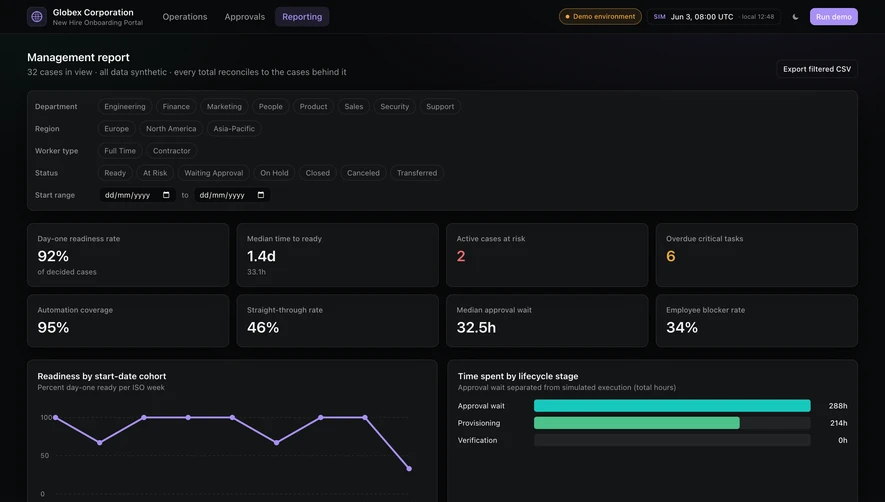
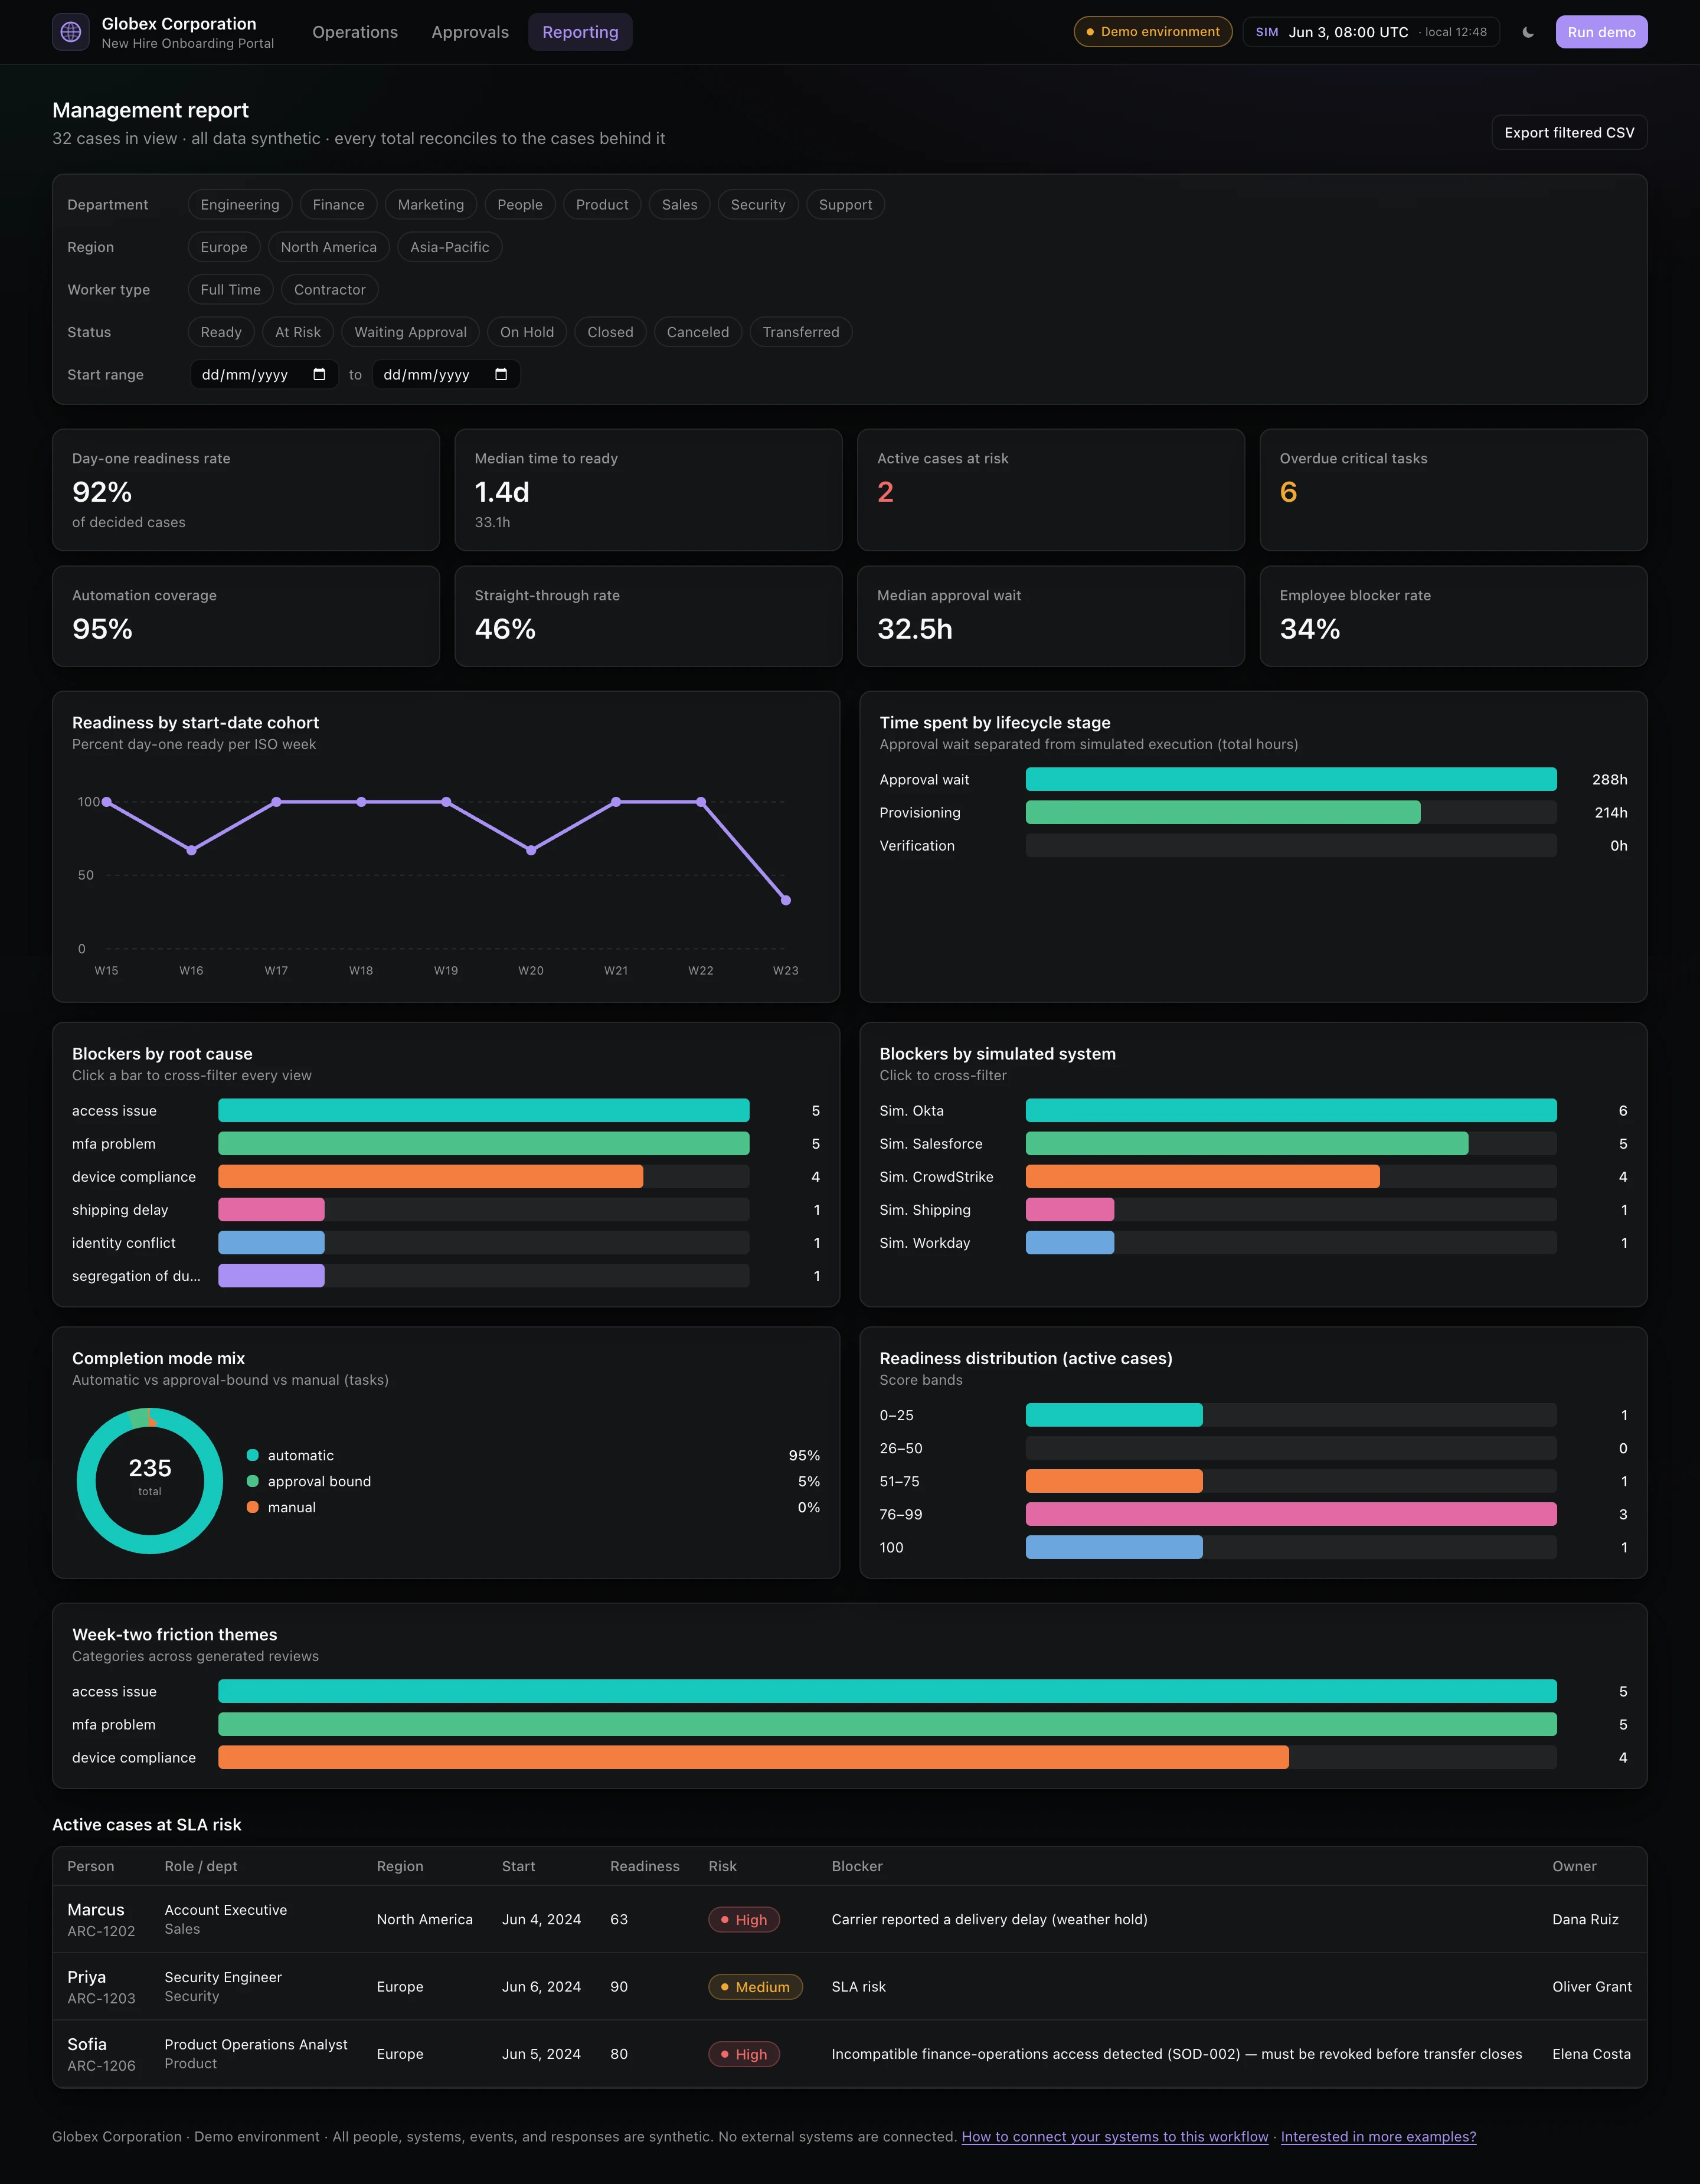
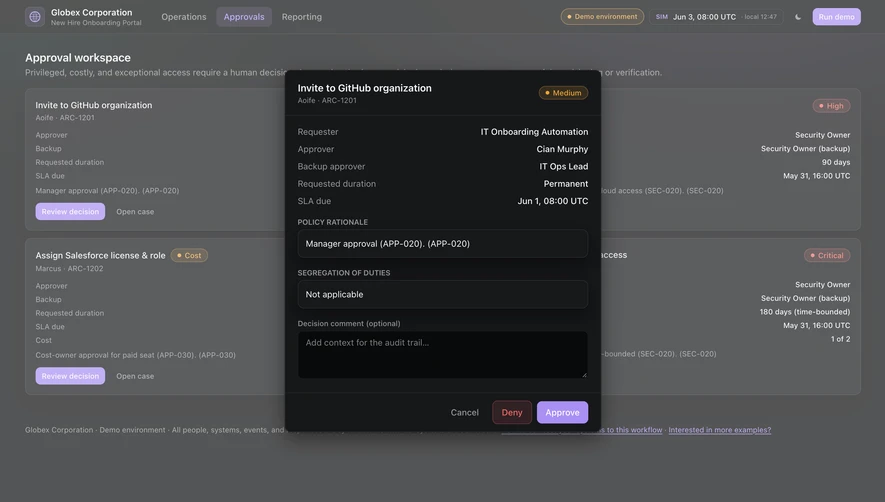

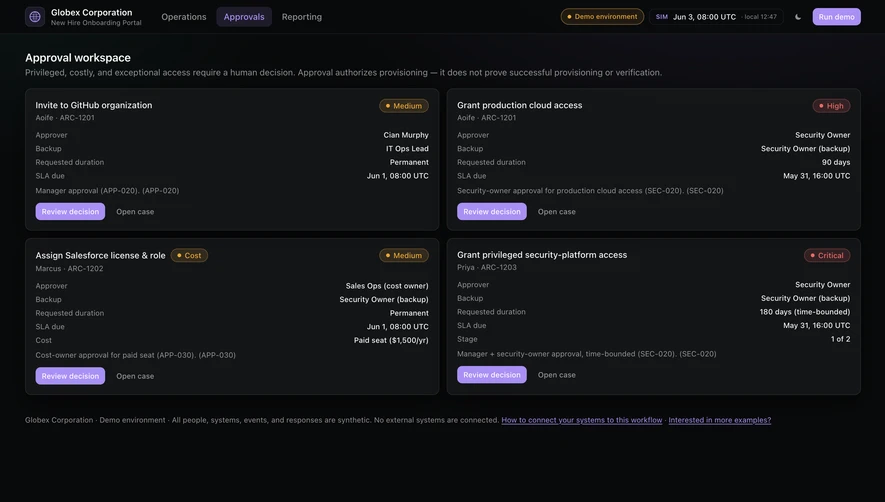

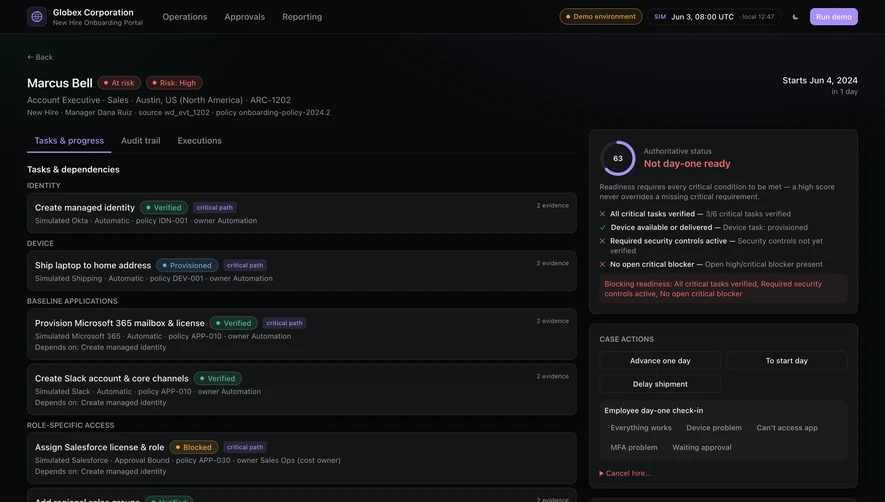
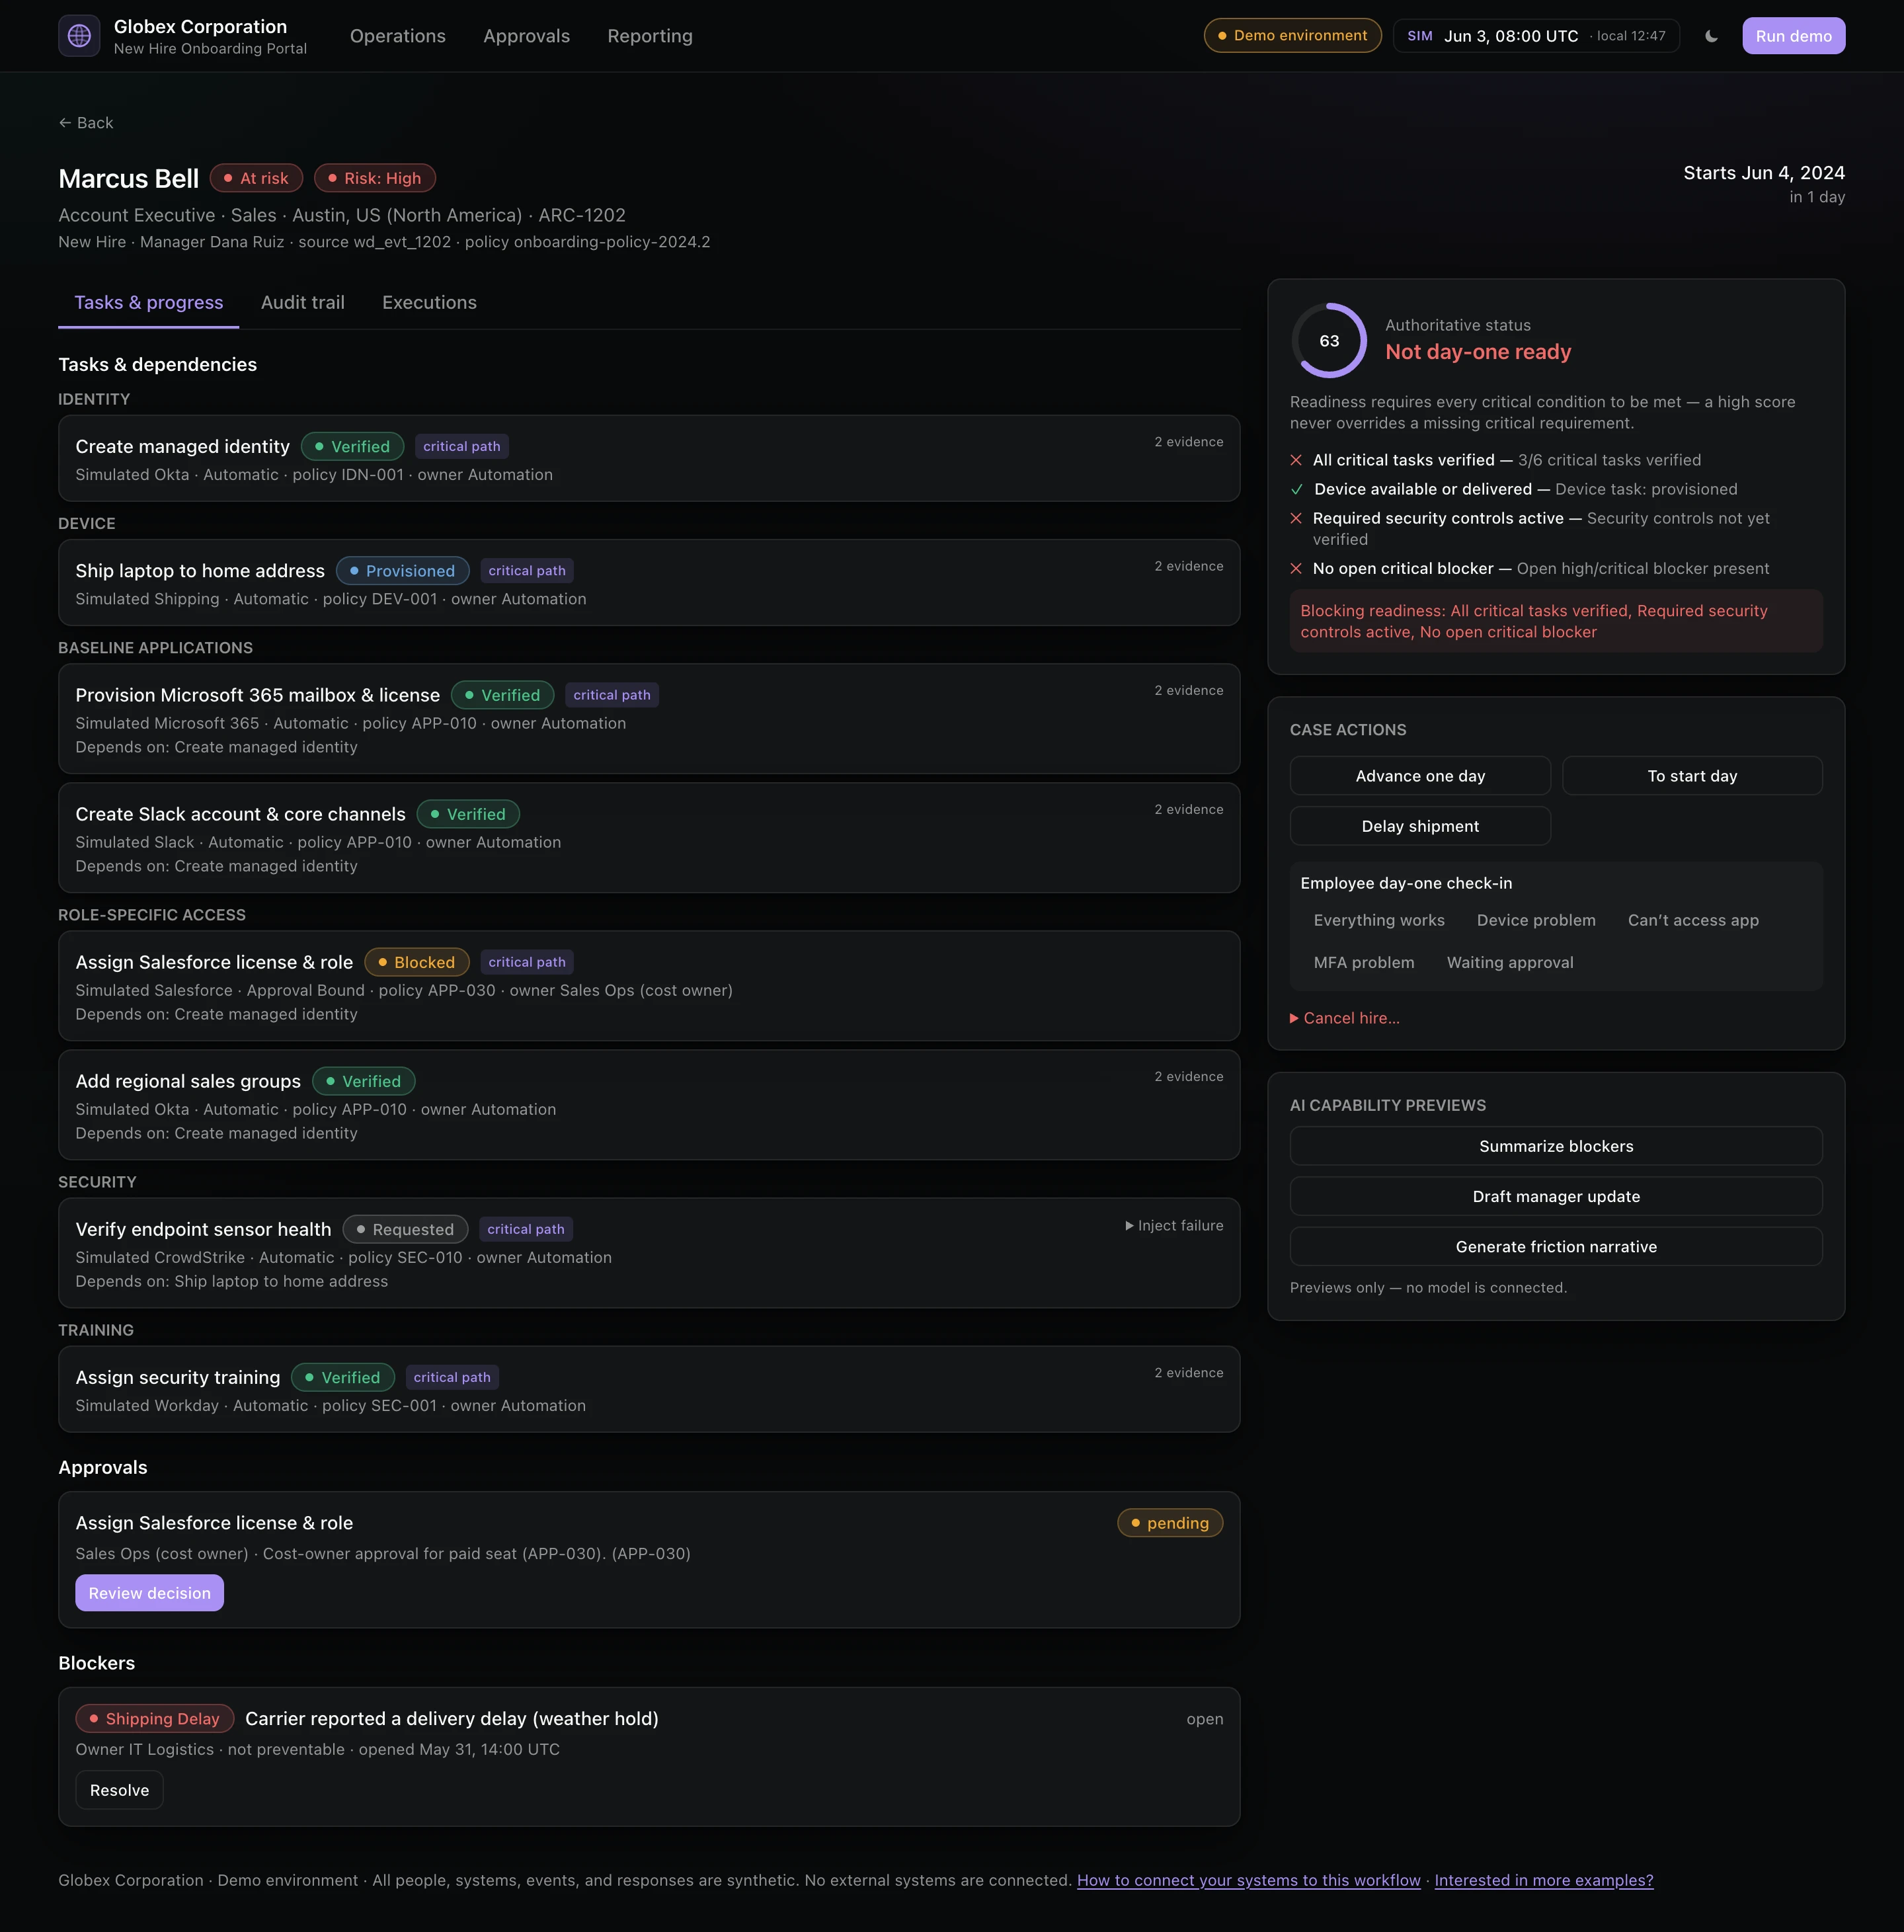

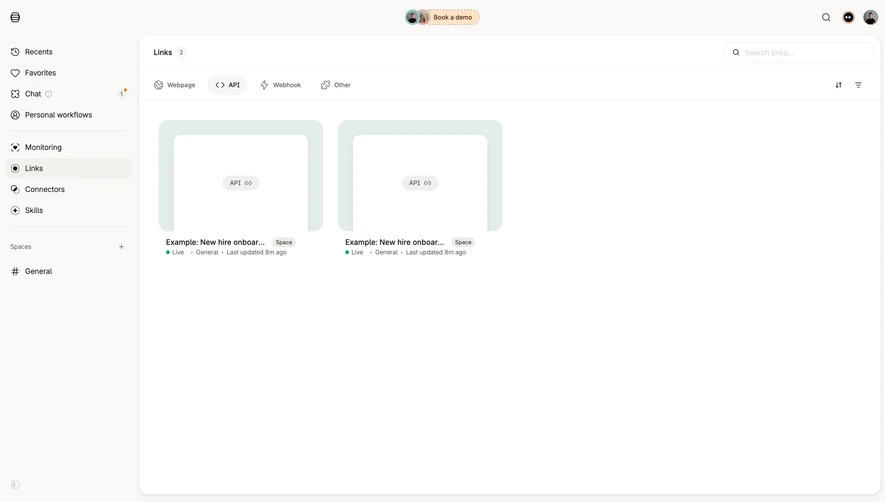
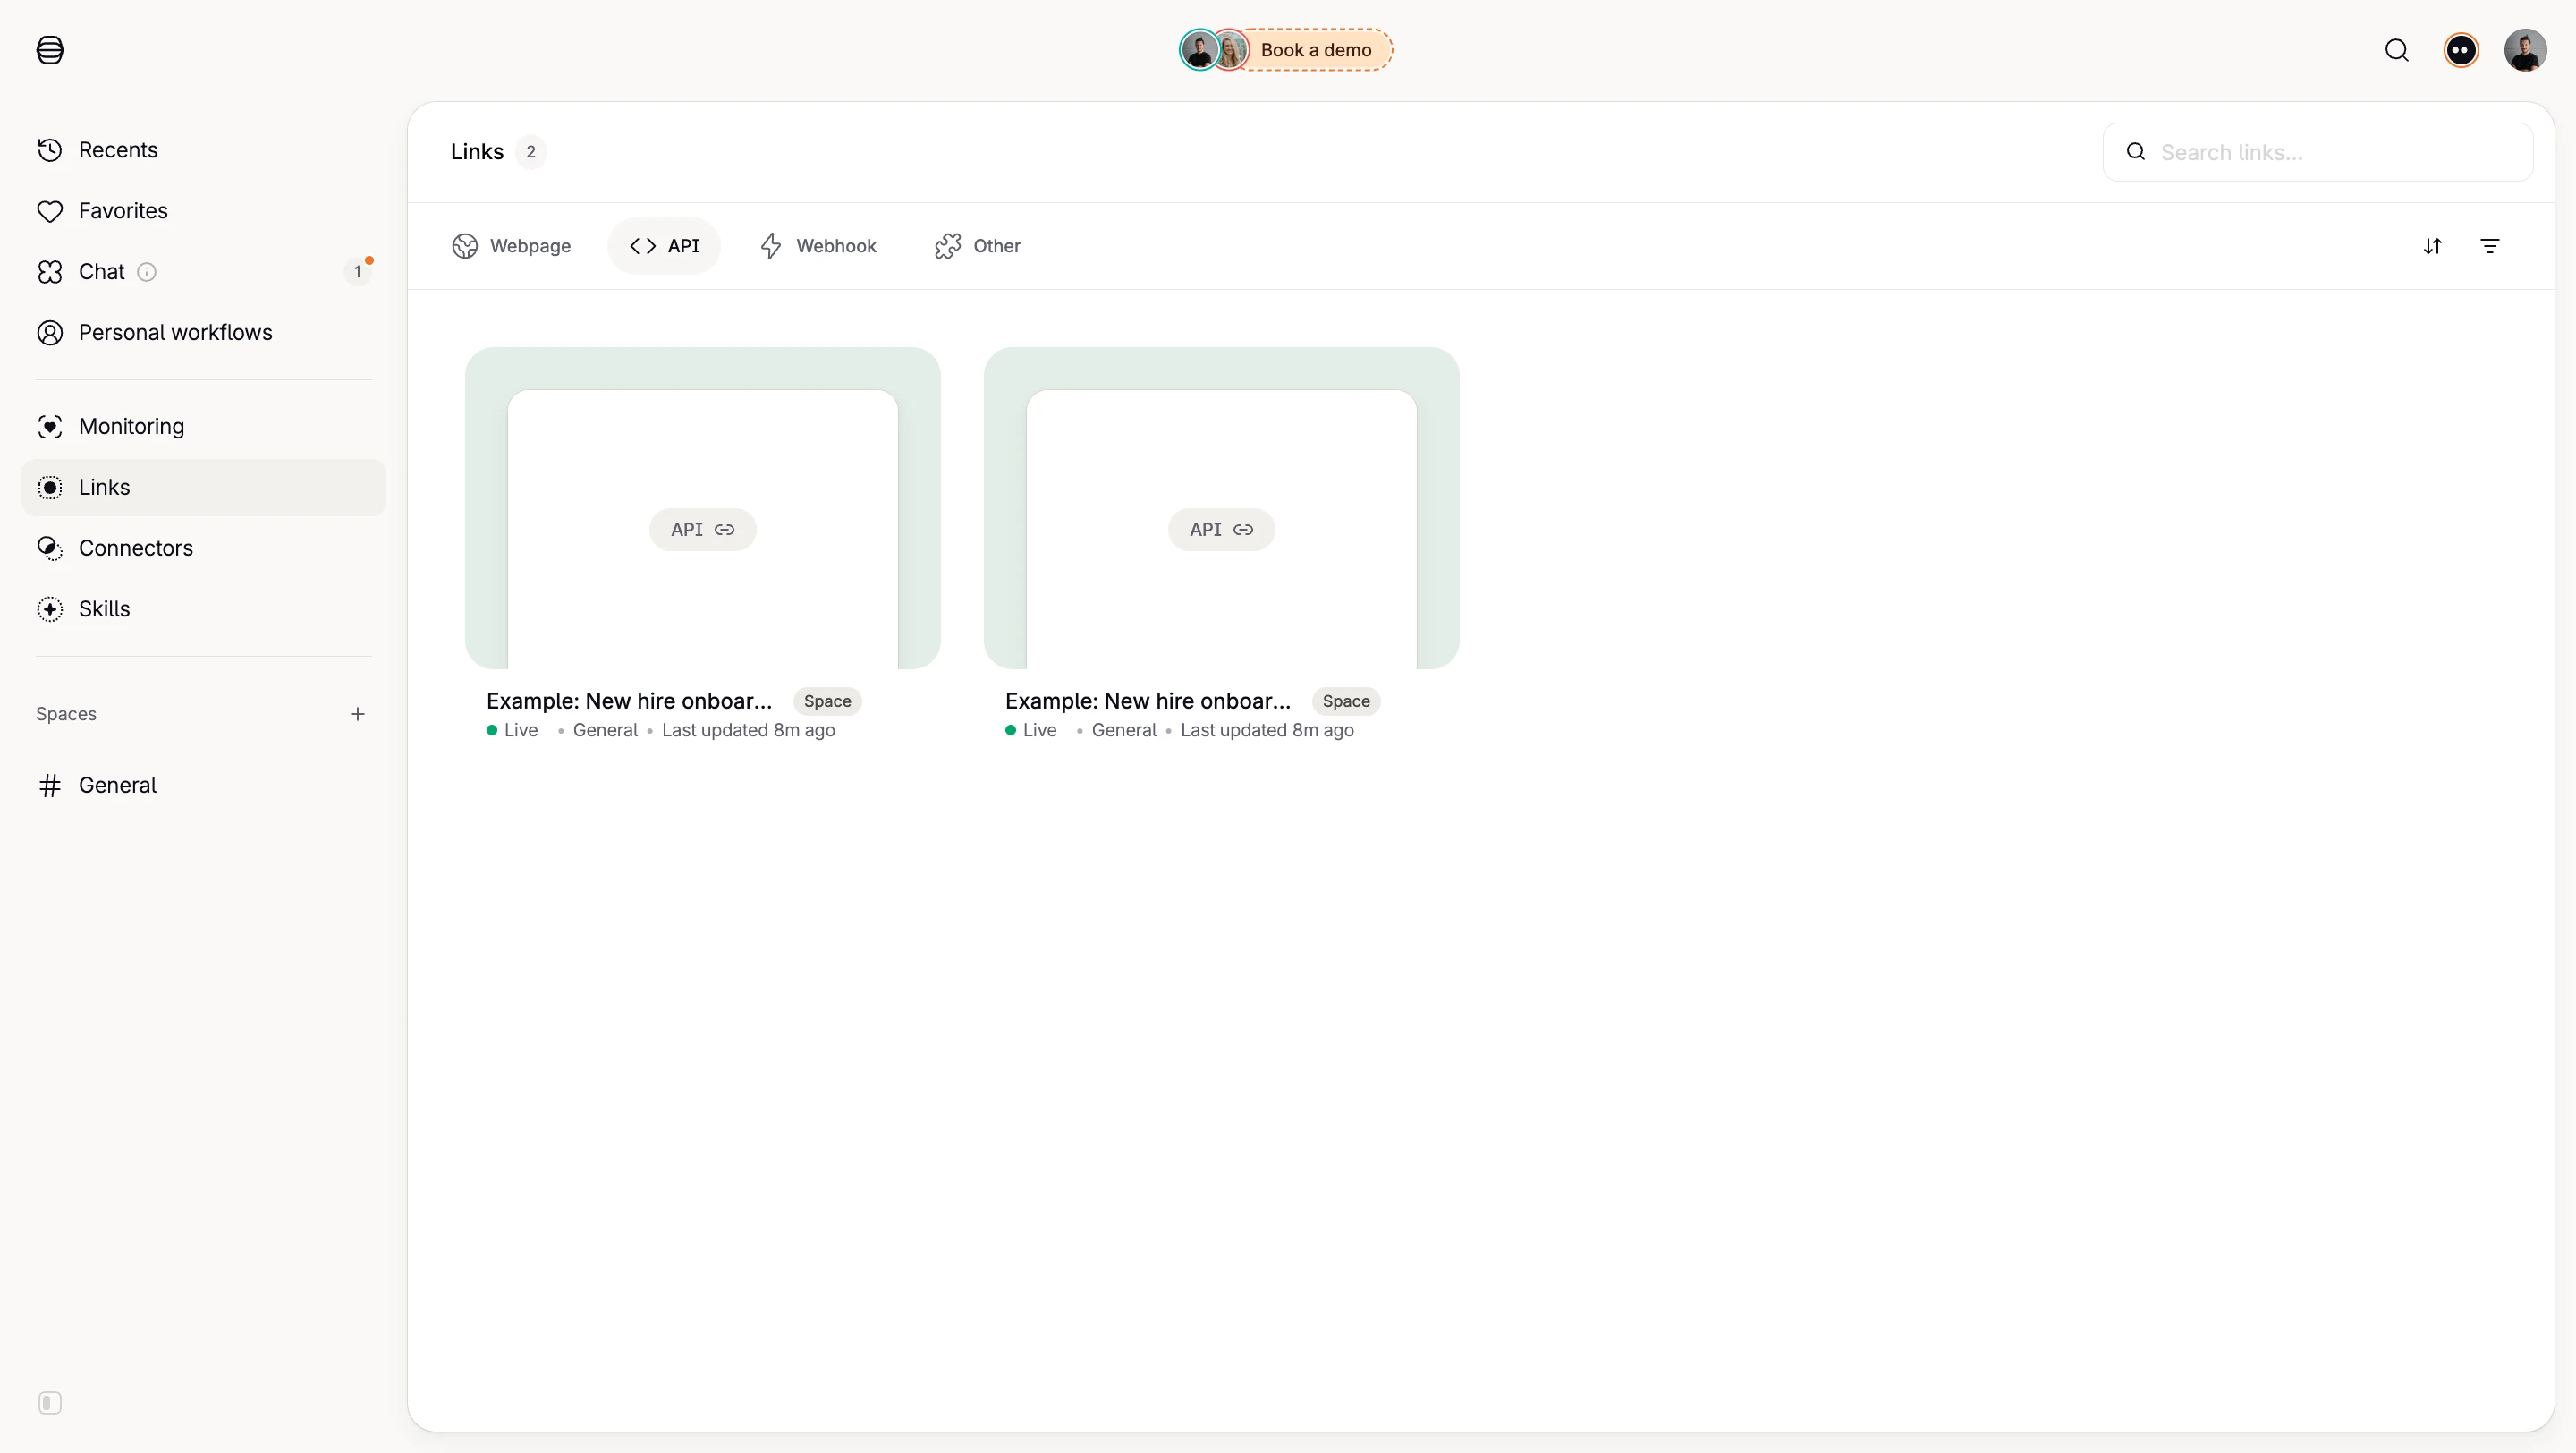
Published Workflow Links
Tines
Table
Product
• Recents • Favorites & Chat • ® Personal workflows • Monitoring • Links • Connectors + Skills Spaces # General Links 2 @ Webpage < > API & Webhook API (> + Example: New hire onboar... Space • Live • General • Last updated 8m ago e) Book a demo § Other Example: New hire onboar... Space • Live • General • Last updated 8m ago a o Q Search links...
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false
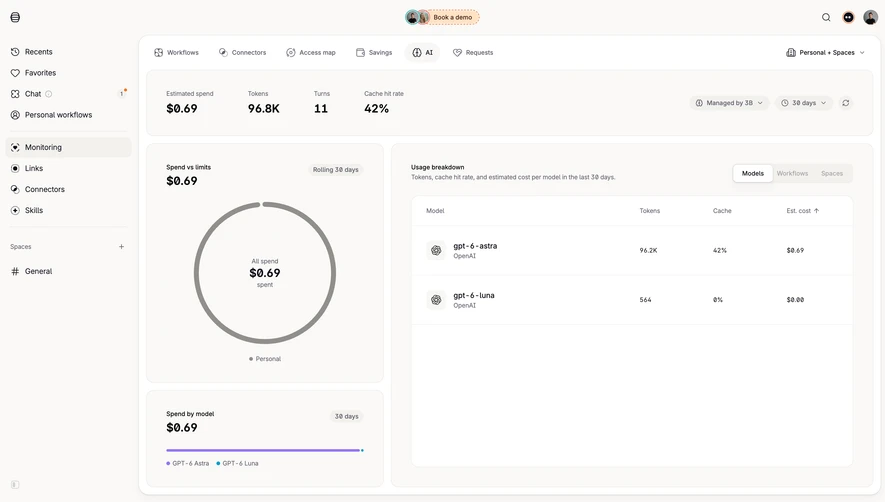
AI Token Usage & Costs
Tines
Usage
Product
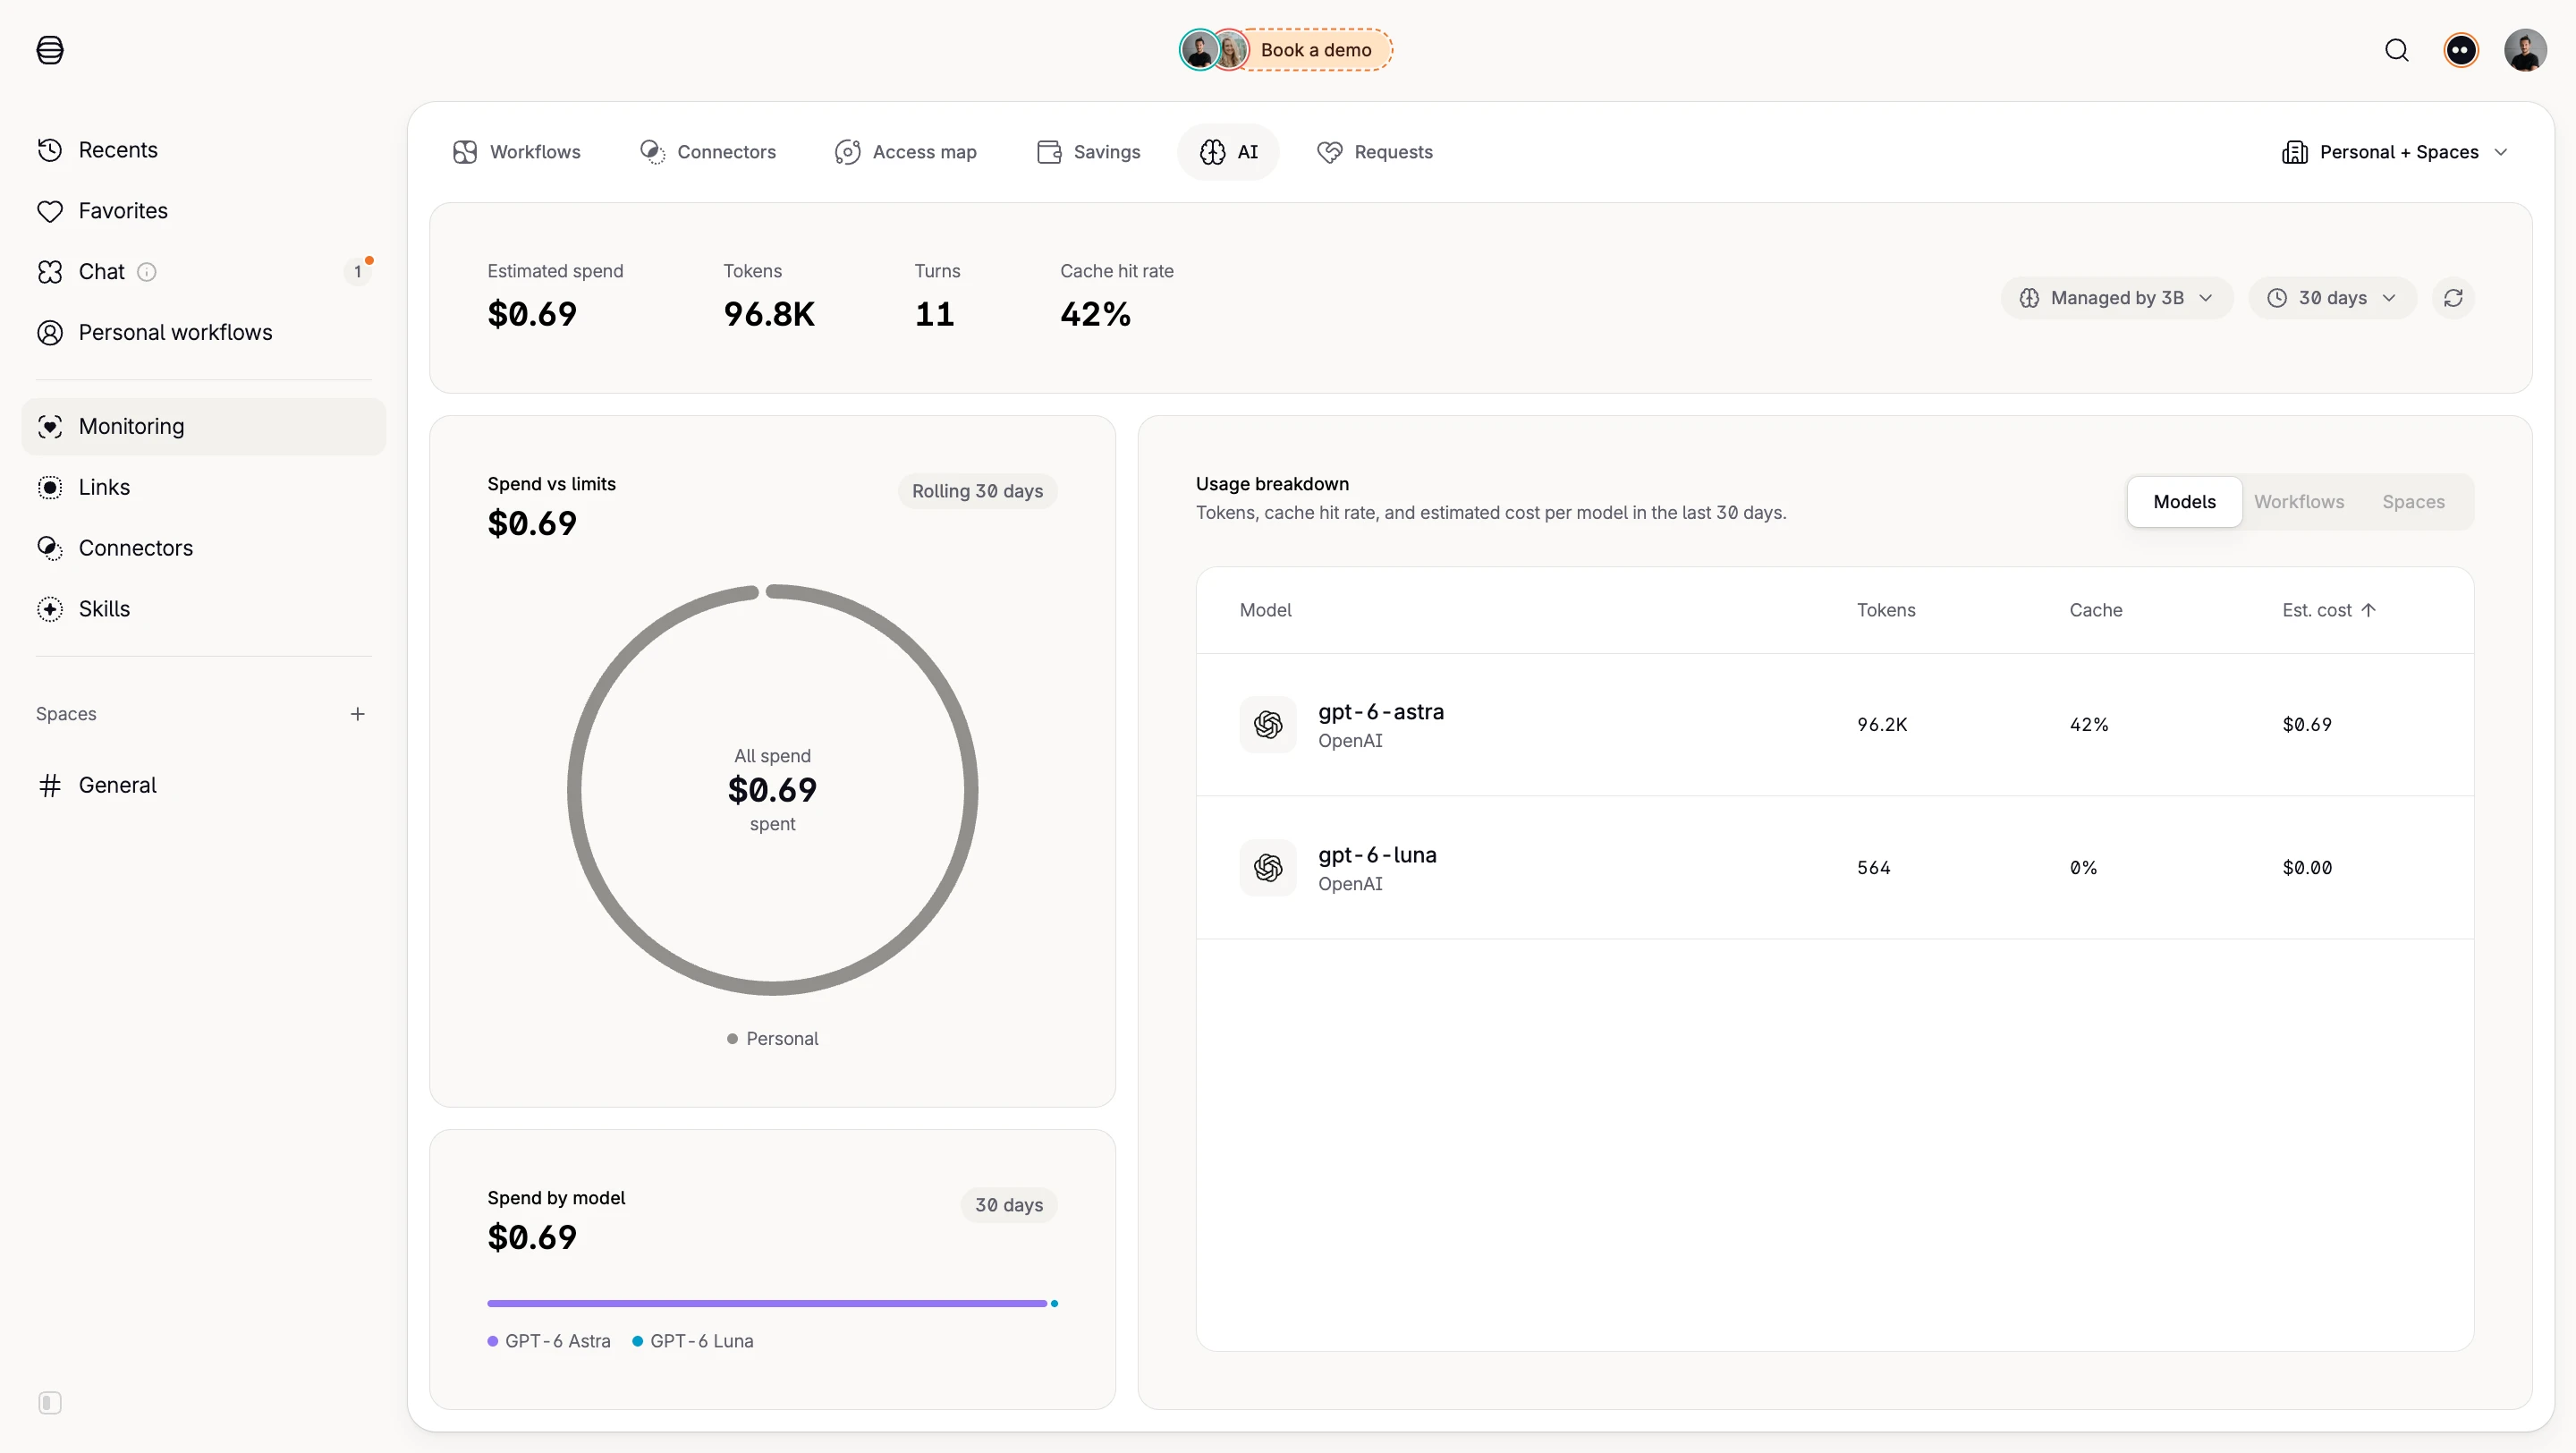
• Recents • Favorites & Chat O ® Personal workflows • Monitoring • Links • Connectors + Skills Spaces # General 69 Workflows Estimated spend $0.69 • Connectors Tokens 96.8K • Access map Turns 11 Rolling 30 days • Savings Cache hit rate 42% # AI Book a demo Requests Spend vs limits $0.69 Usage breakdown Tokens, cache hit rate, and estimated cost per model in the last 30 days. Model gpt - 6 - astra OpenAI All spend $0.69 spent gpt - 6 - luna OpenAI • Personal Spend by model $0.69 • GPT - 6 Astra • GPT - 6 Luna 30 days Tokens 96.2K 564 0 Managed by 3B v Models Cache 42% 0% daD Personal + Spaces v © 30 days v Workflows Est. cost 1 $0.69 $0.00 Spaces
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false
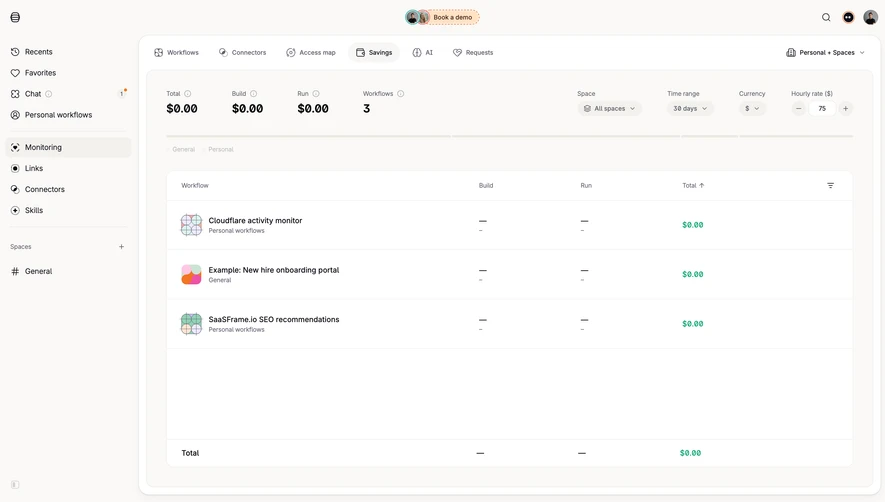
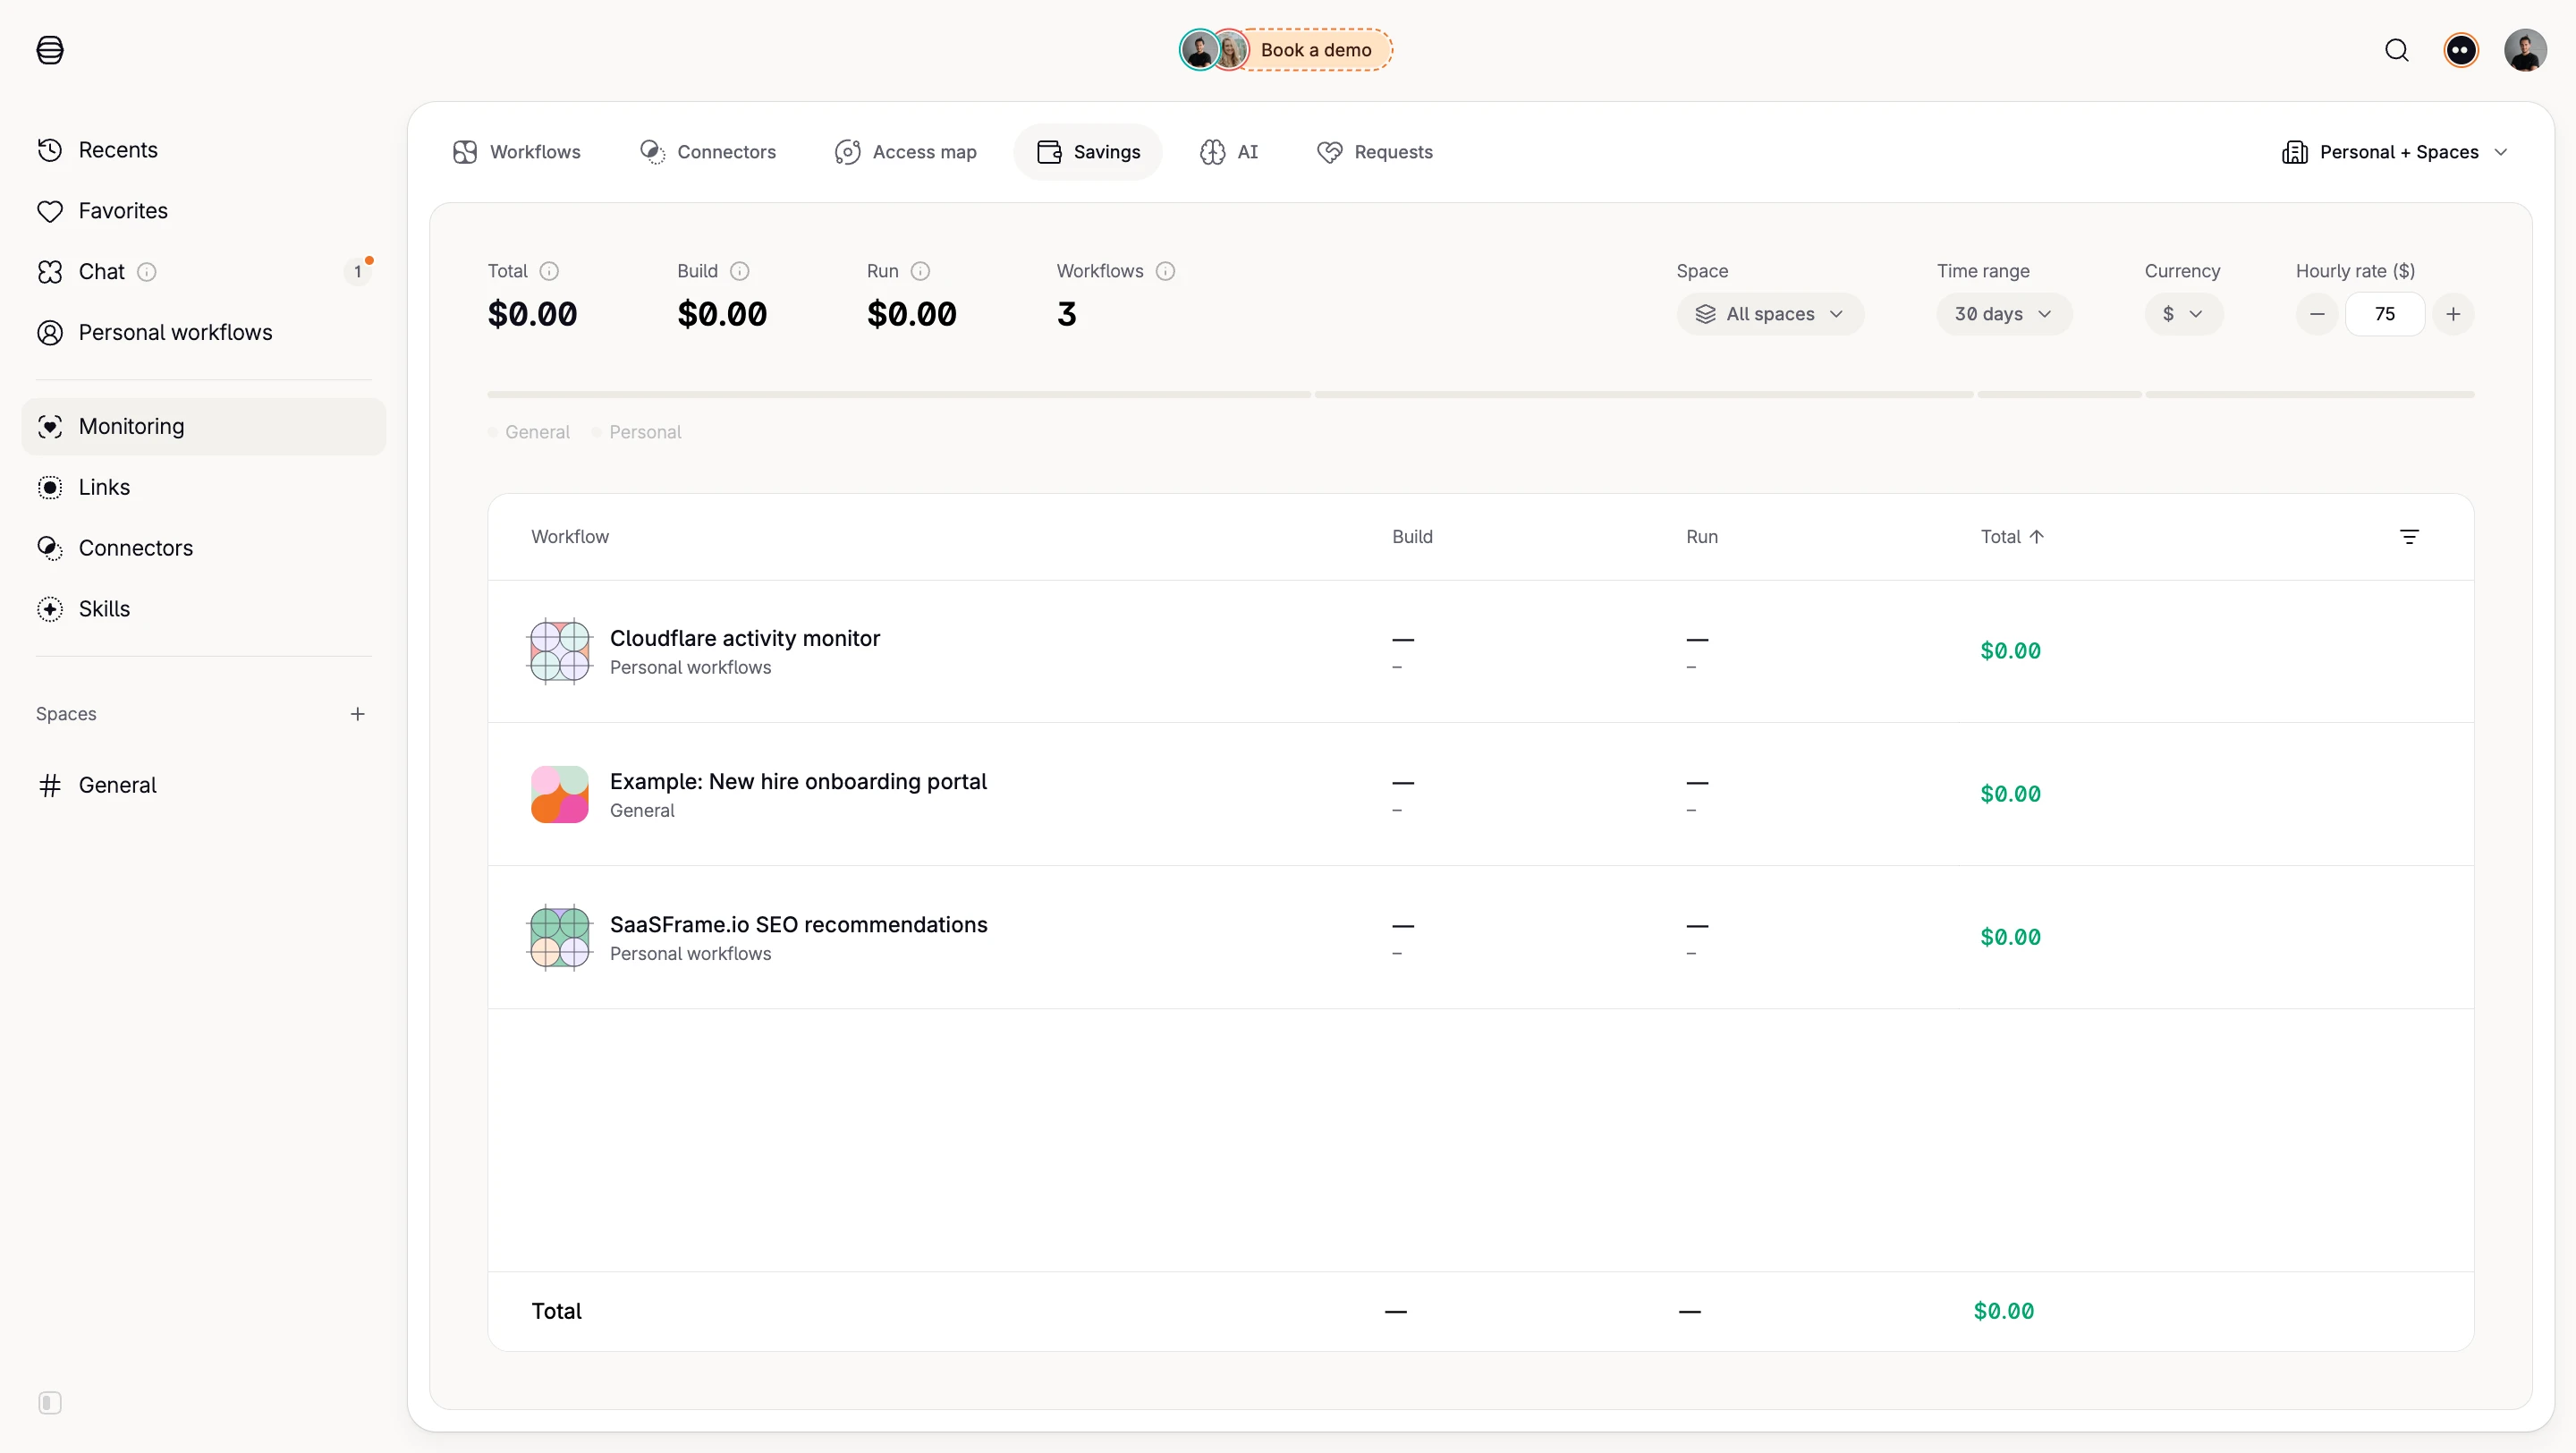
Workflow Savings Report
Tines
Usage
Product
• Recents • Favorites 8 Chat O ® Personal workflows Monitoring • Links • Connectors + Skills Spaces # General 8 Workflows Total O $0.00 General Workflow • Connectors 0) Access map • Savings # AI Book a demo 2 Requests Build O $0.00 Run O $0.00 Workflows O 3 Personal Cloudflare activity monitor Personal workflows Example: New hire onboarding portal General SaaSFrame. io SEO recommendations Personal workflows Build = = = Total Space • All spaces v Run daD Personal + Spaces v Time range 30 days v Currency $ v Hourly rate ($) 75 Total 1 $0.00 $0.00 $0.00 $0.00
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false
Workspace Access Map
Tines
Flowchart
Product
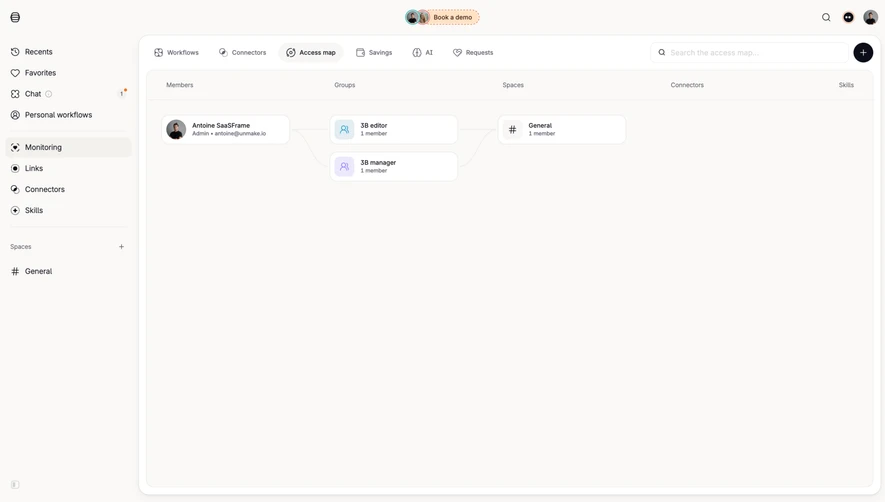
• Recents • Favorites & Chat O 8 Personal workflows • Monitoring • Links • Connectors (+ Skills Spaces # General + Je Book a demo 6 Workflows • Connectors (o) Access map • Savings 0 AI Requests Members Groups Spaces Antoine SaaSFrame Admin • [email protected] 3B editor 1 member # General 1 member 3B manager 1 member a o Q Search the access map... Connectors Skills
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false
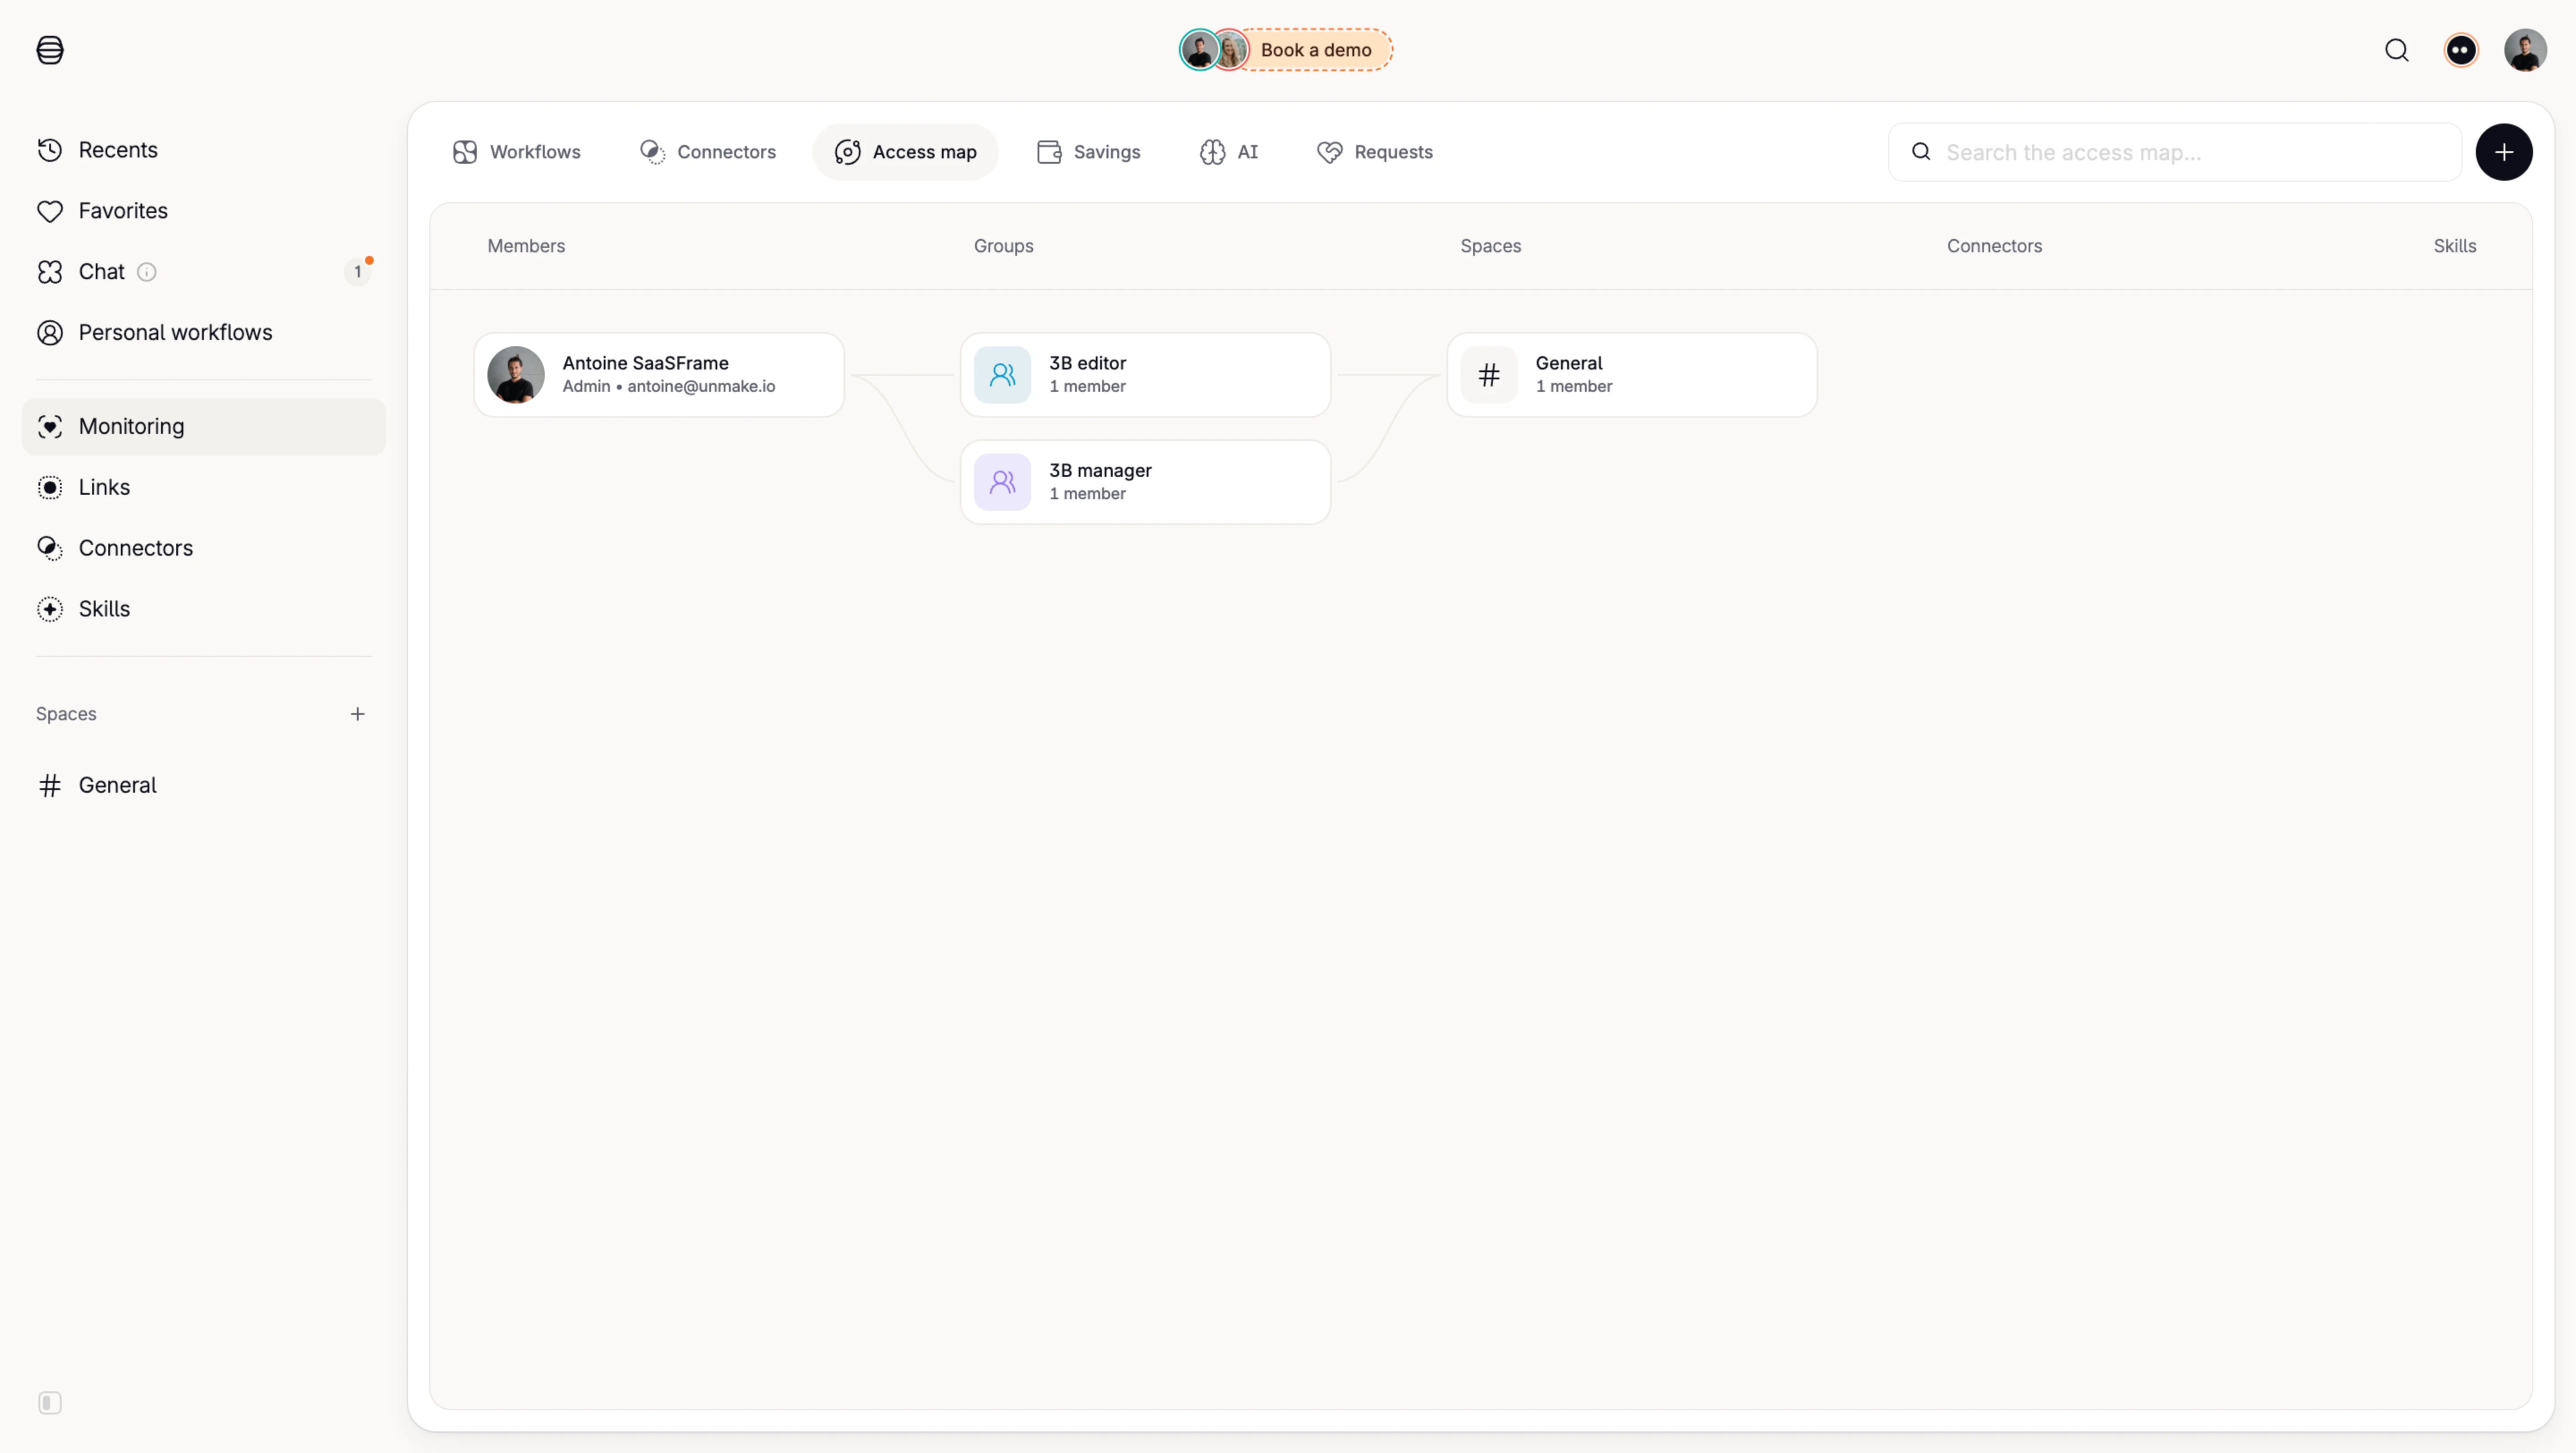
Connector Request Monitoring
Tines
Empty State
Product
• Recents • Favorites & Chat O • Personal workflows Monitoring • Links • Connectors + Skills Spaces # General + • Book a demo & Workflows • Connectors (0) Access map E savings # AI Requests Requests Errors Error rate © 30 days v Connector Requests by connector Requests per connector in the last 30 days. a daD Personal + Spaces v Requests Error rate
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false

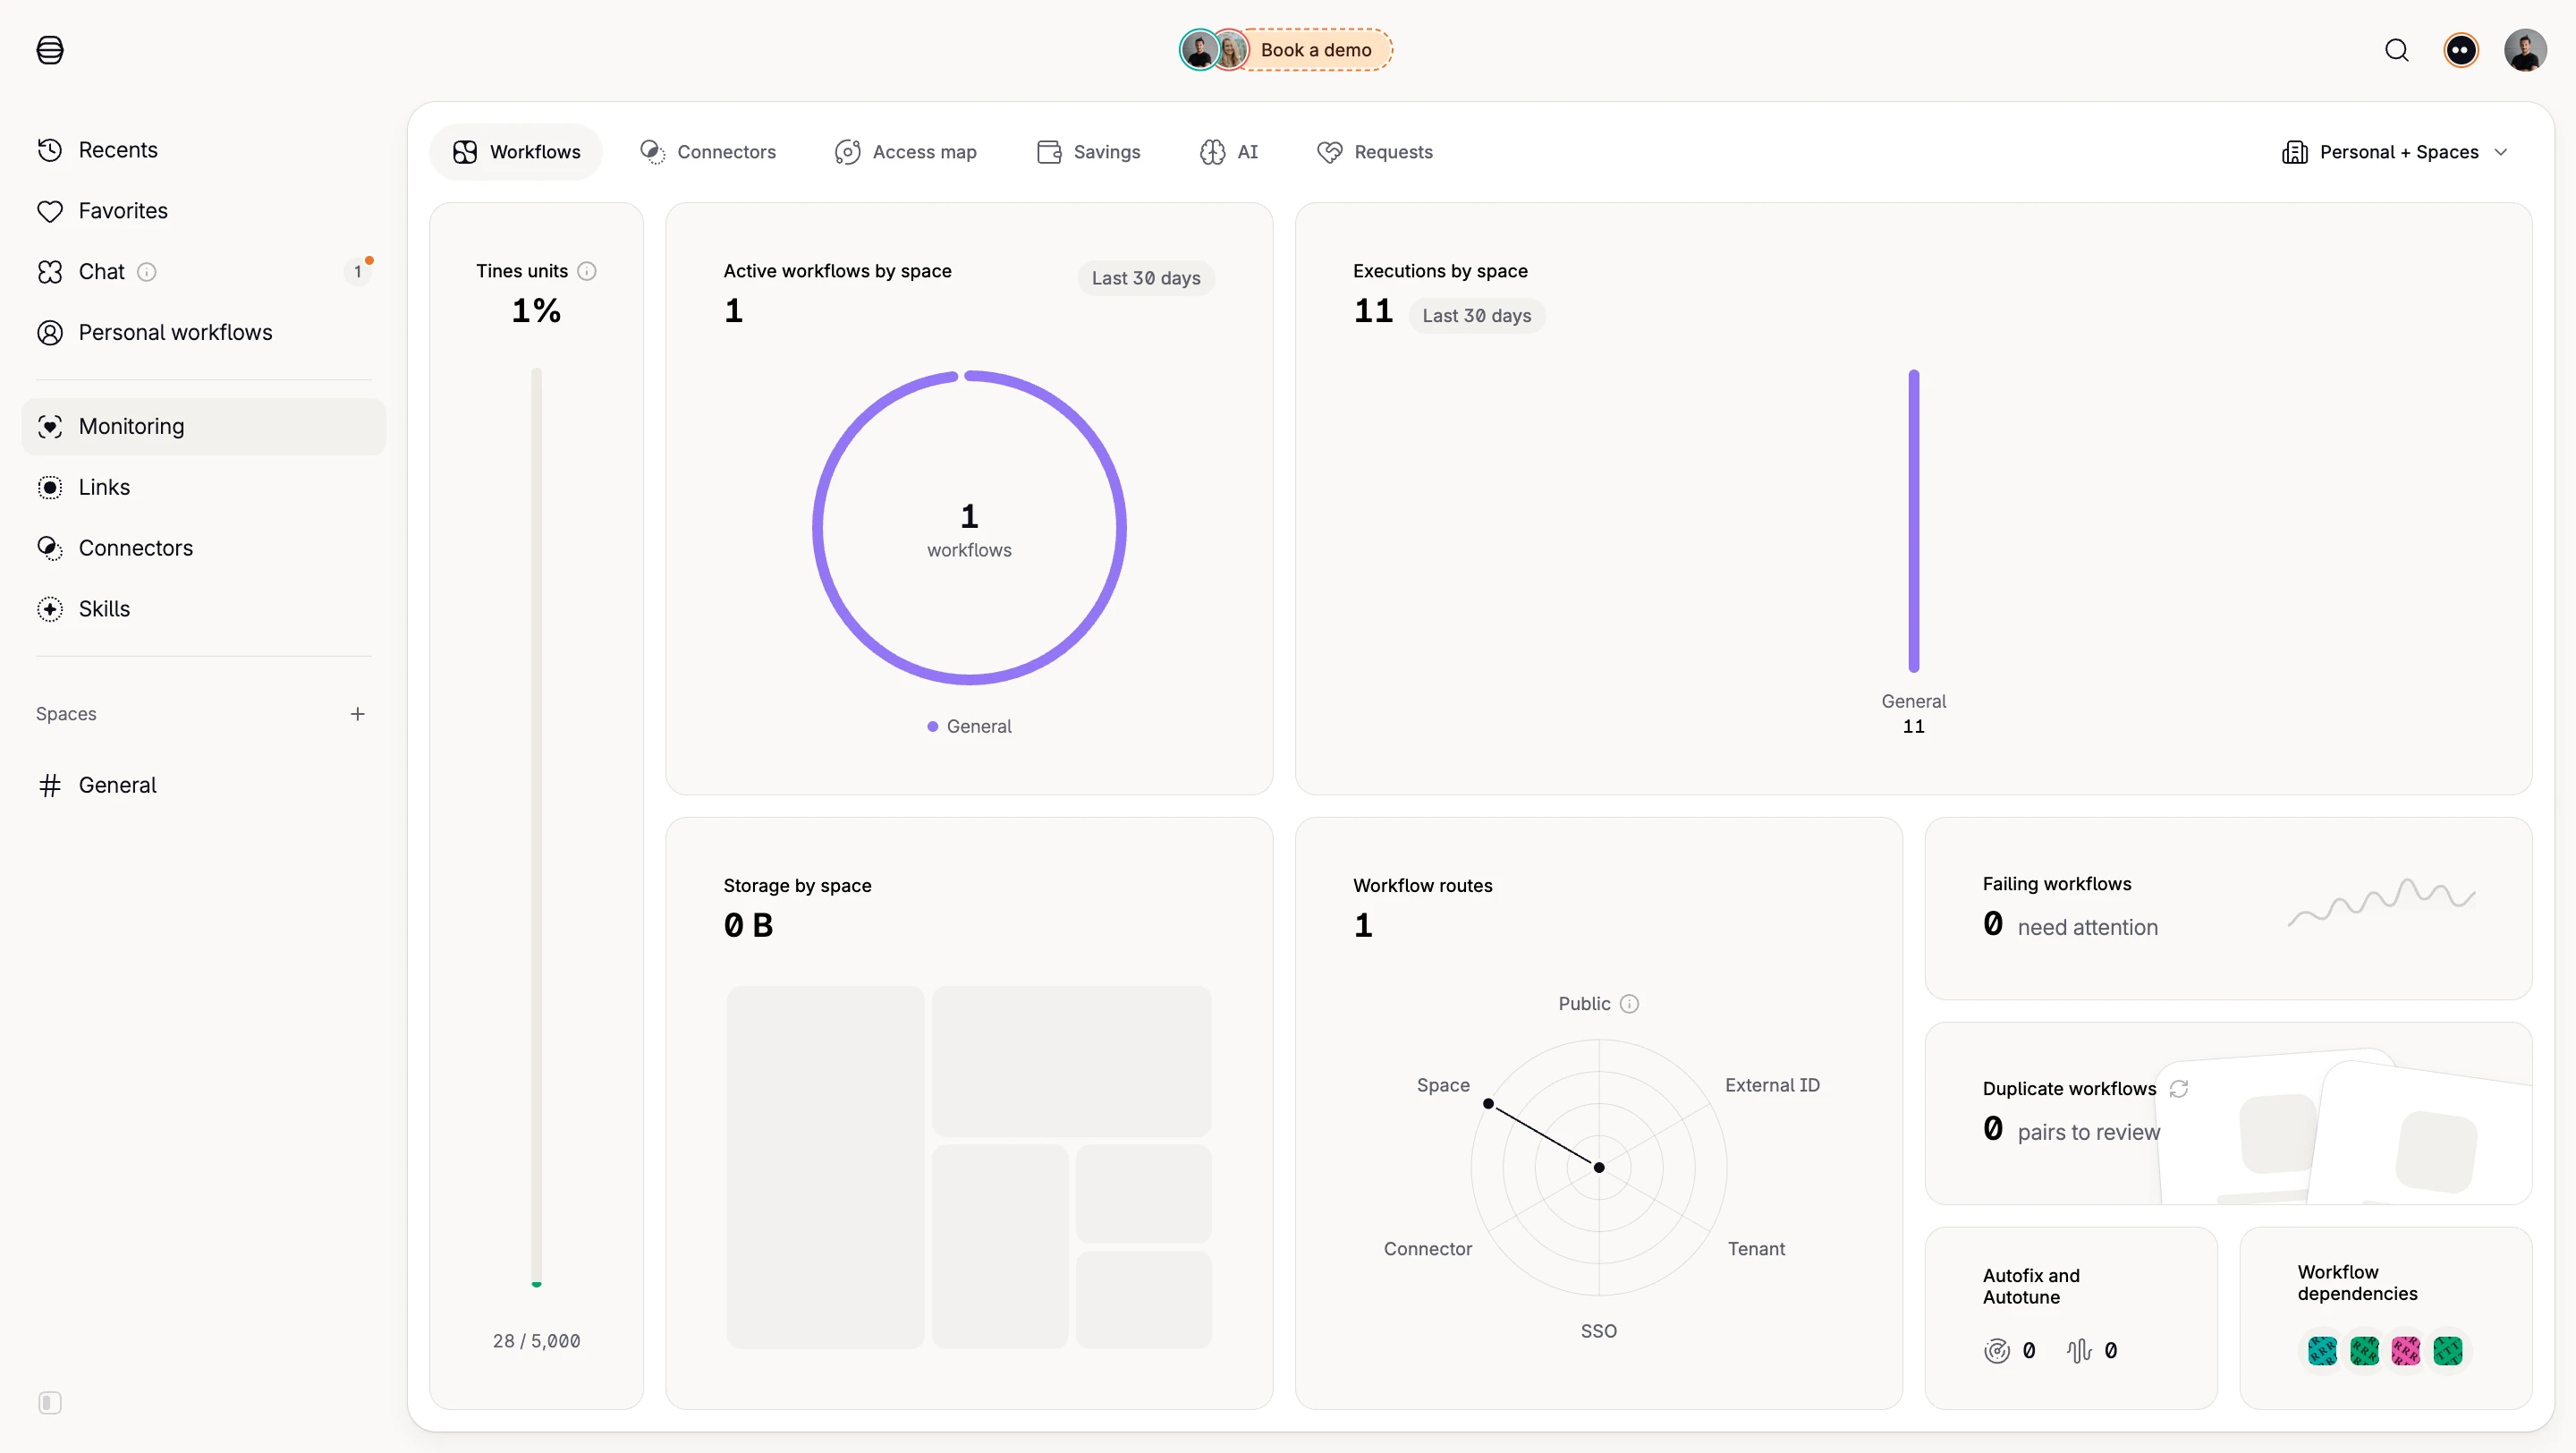
Workflow Monitoring Overview
Tines
Dashboard
Product
• Recents • Favorites & Chat • ® Personal workflows • Monitoring • Links • Connectors + Skills Spaces # General Book a demo & Workflows Tines units O 1% • Connectors 0) Access map • Savings # AI Requests Active workflows by space Last 30 days 1 Executions by space 11 Last 30 days 1 workflows • General Storage by space Workflow routes 1 Public ® Space Connector 28 / 5,000 SSO External ID Tenant General 11 Failing workflows • need attention Duplicate workflows C • pairs to review Autofix and Autotune daD Personal + Spaces v Workflow dependencies
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false
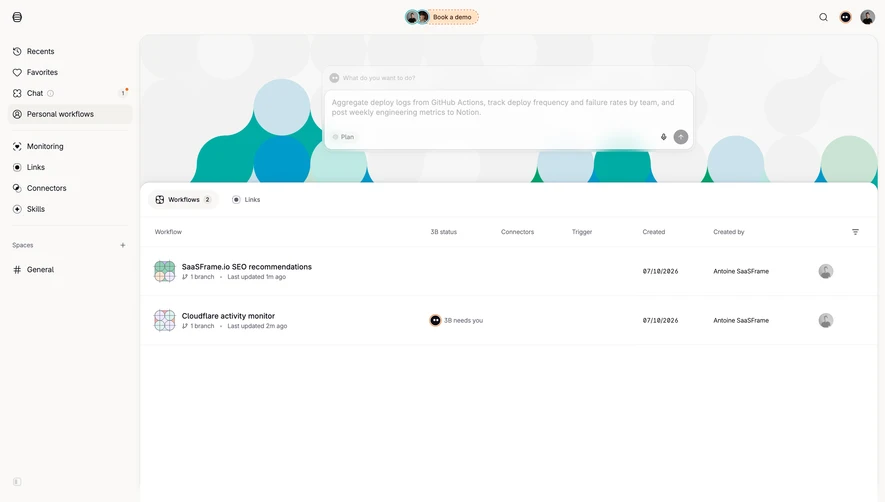
Personal Workflow Library
Tines
Table
Product
1 Recents • Favorites & Chat • ® Personal workflows Monitoring • Links • Connectors + Skills Spaces # General Book a demo • What do you want to do? Aggregate deploy logs from GitHub Actions, track deploy frequency and failure rates by team, and post weekly engineering metrics to Notion. • Plan • Workflows 2 • Links Workflow 3B status Connectors Trigger Created SaaSFrame.io SEO recommendations 1 1 branch • Last updated 1m ago 07/10/2026 Cloudflare activity monitor 1º 1 branch • Last updated 2m ago • 3B needs you 07/10/2026 Created by Antoine SaaSFrame Antoine SaaSFrame
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false
false
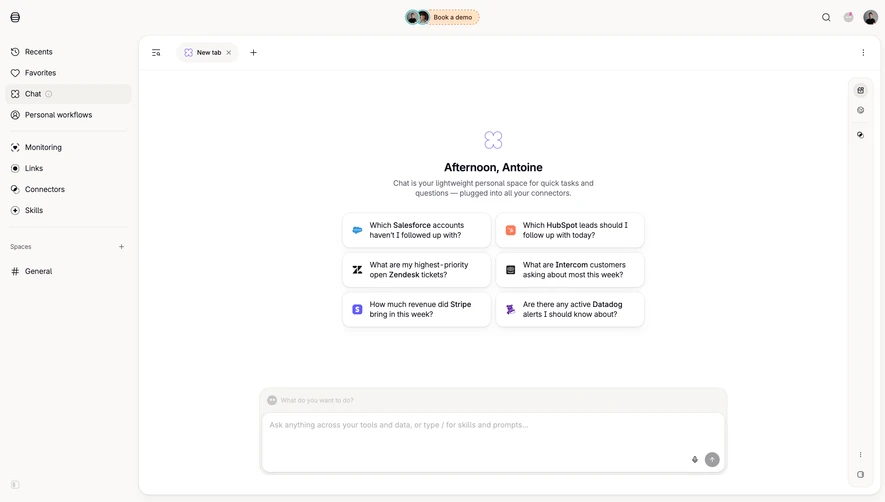
AI Chat Starter Prompts
Tines
Chat
Product
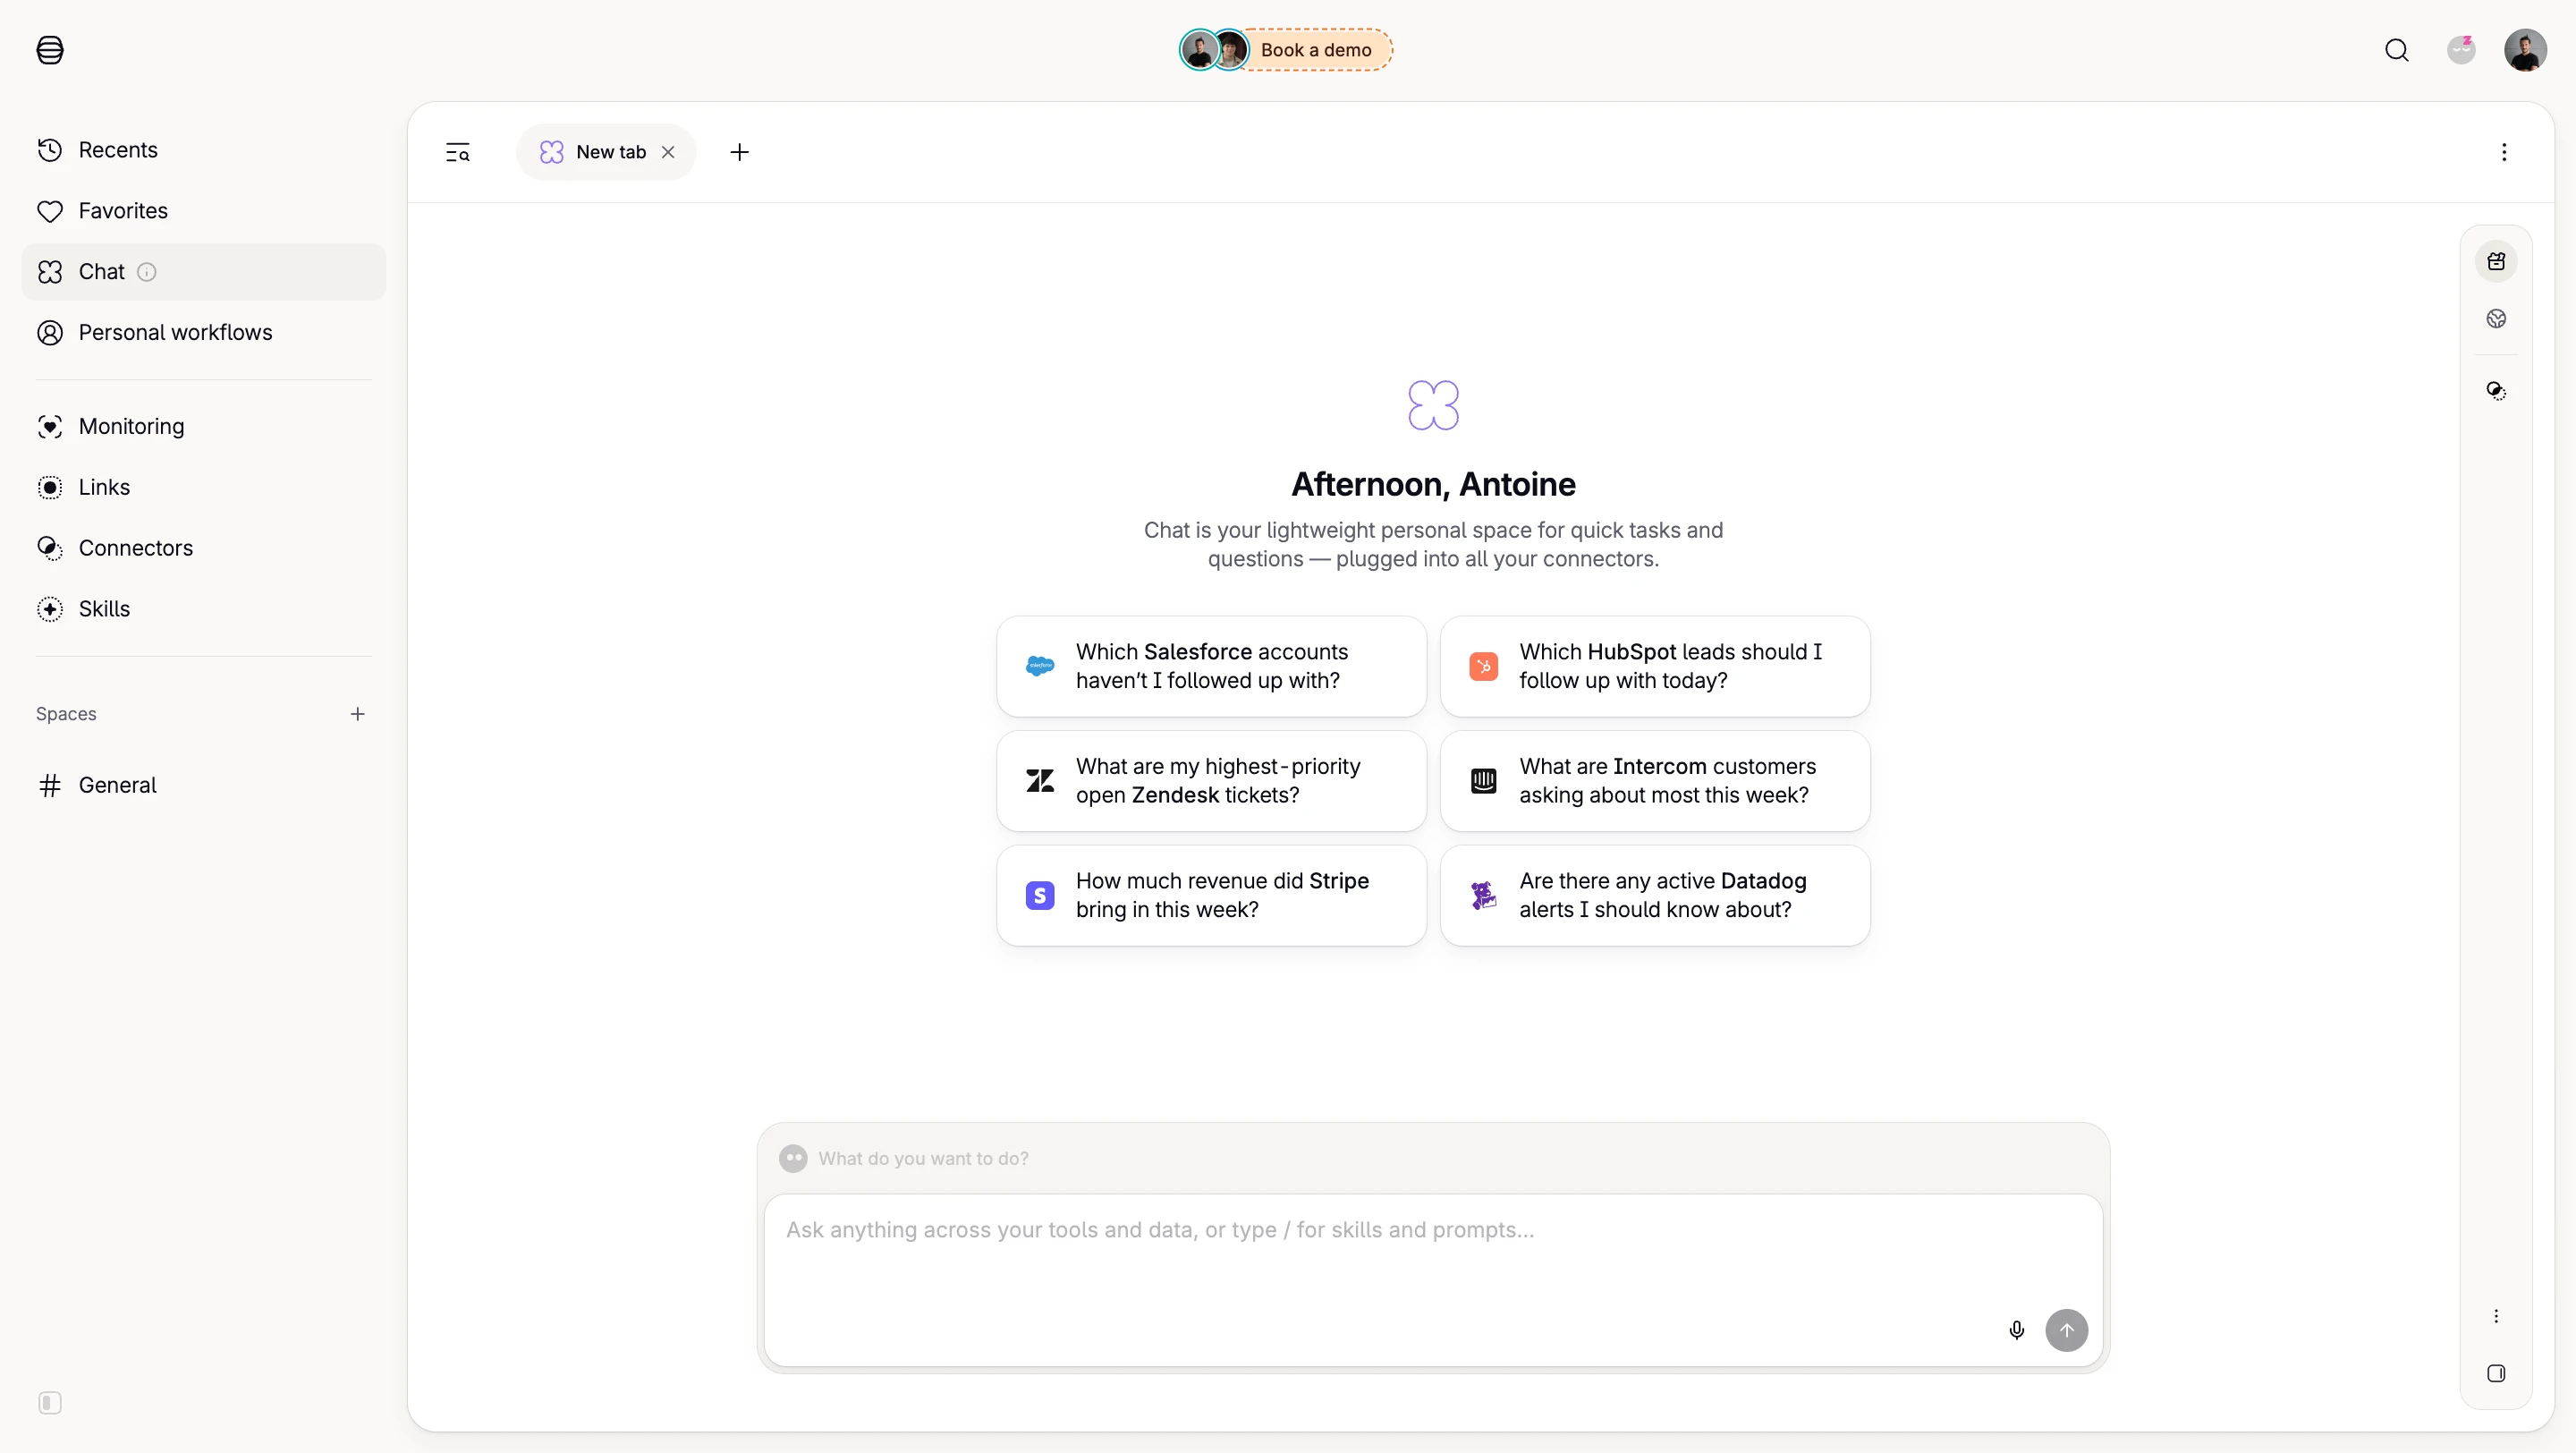
• Recents • Favorites & Chat O ® Personal workflows • Monitoring • Links • Connectors + Skills Spaces # General • + Book a demo a e E3 Newtab × + Afternoon, Antoine Chat is your lightweight personal space for quick tasks and questions - plugged into all your connectors. Which Salesforce accounts haven't I followed up with? I What Zendesk tickets priority How much revenue did Stripe bring in this week? Which HubSpot leads should I follow up with today? What are Intercom customers asking about most this week? Are there any active Datadog alerts I should know about? • What do you want to do? Ask anything across your tools and data, or type / for skills and prompts...
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false
false
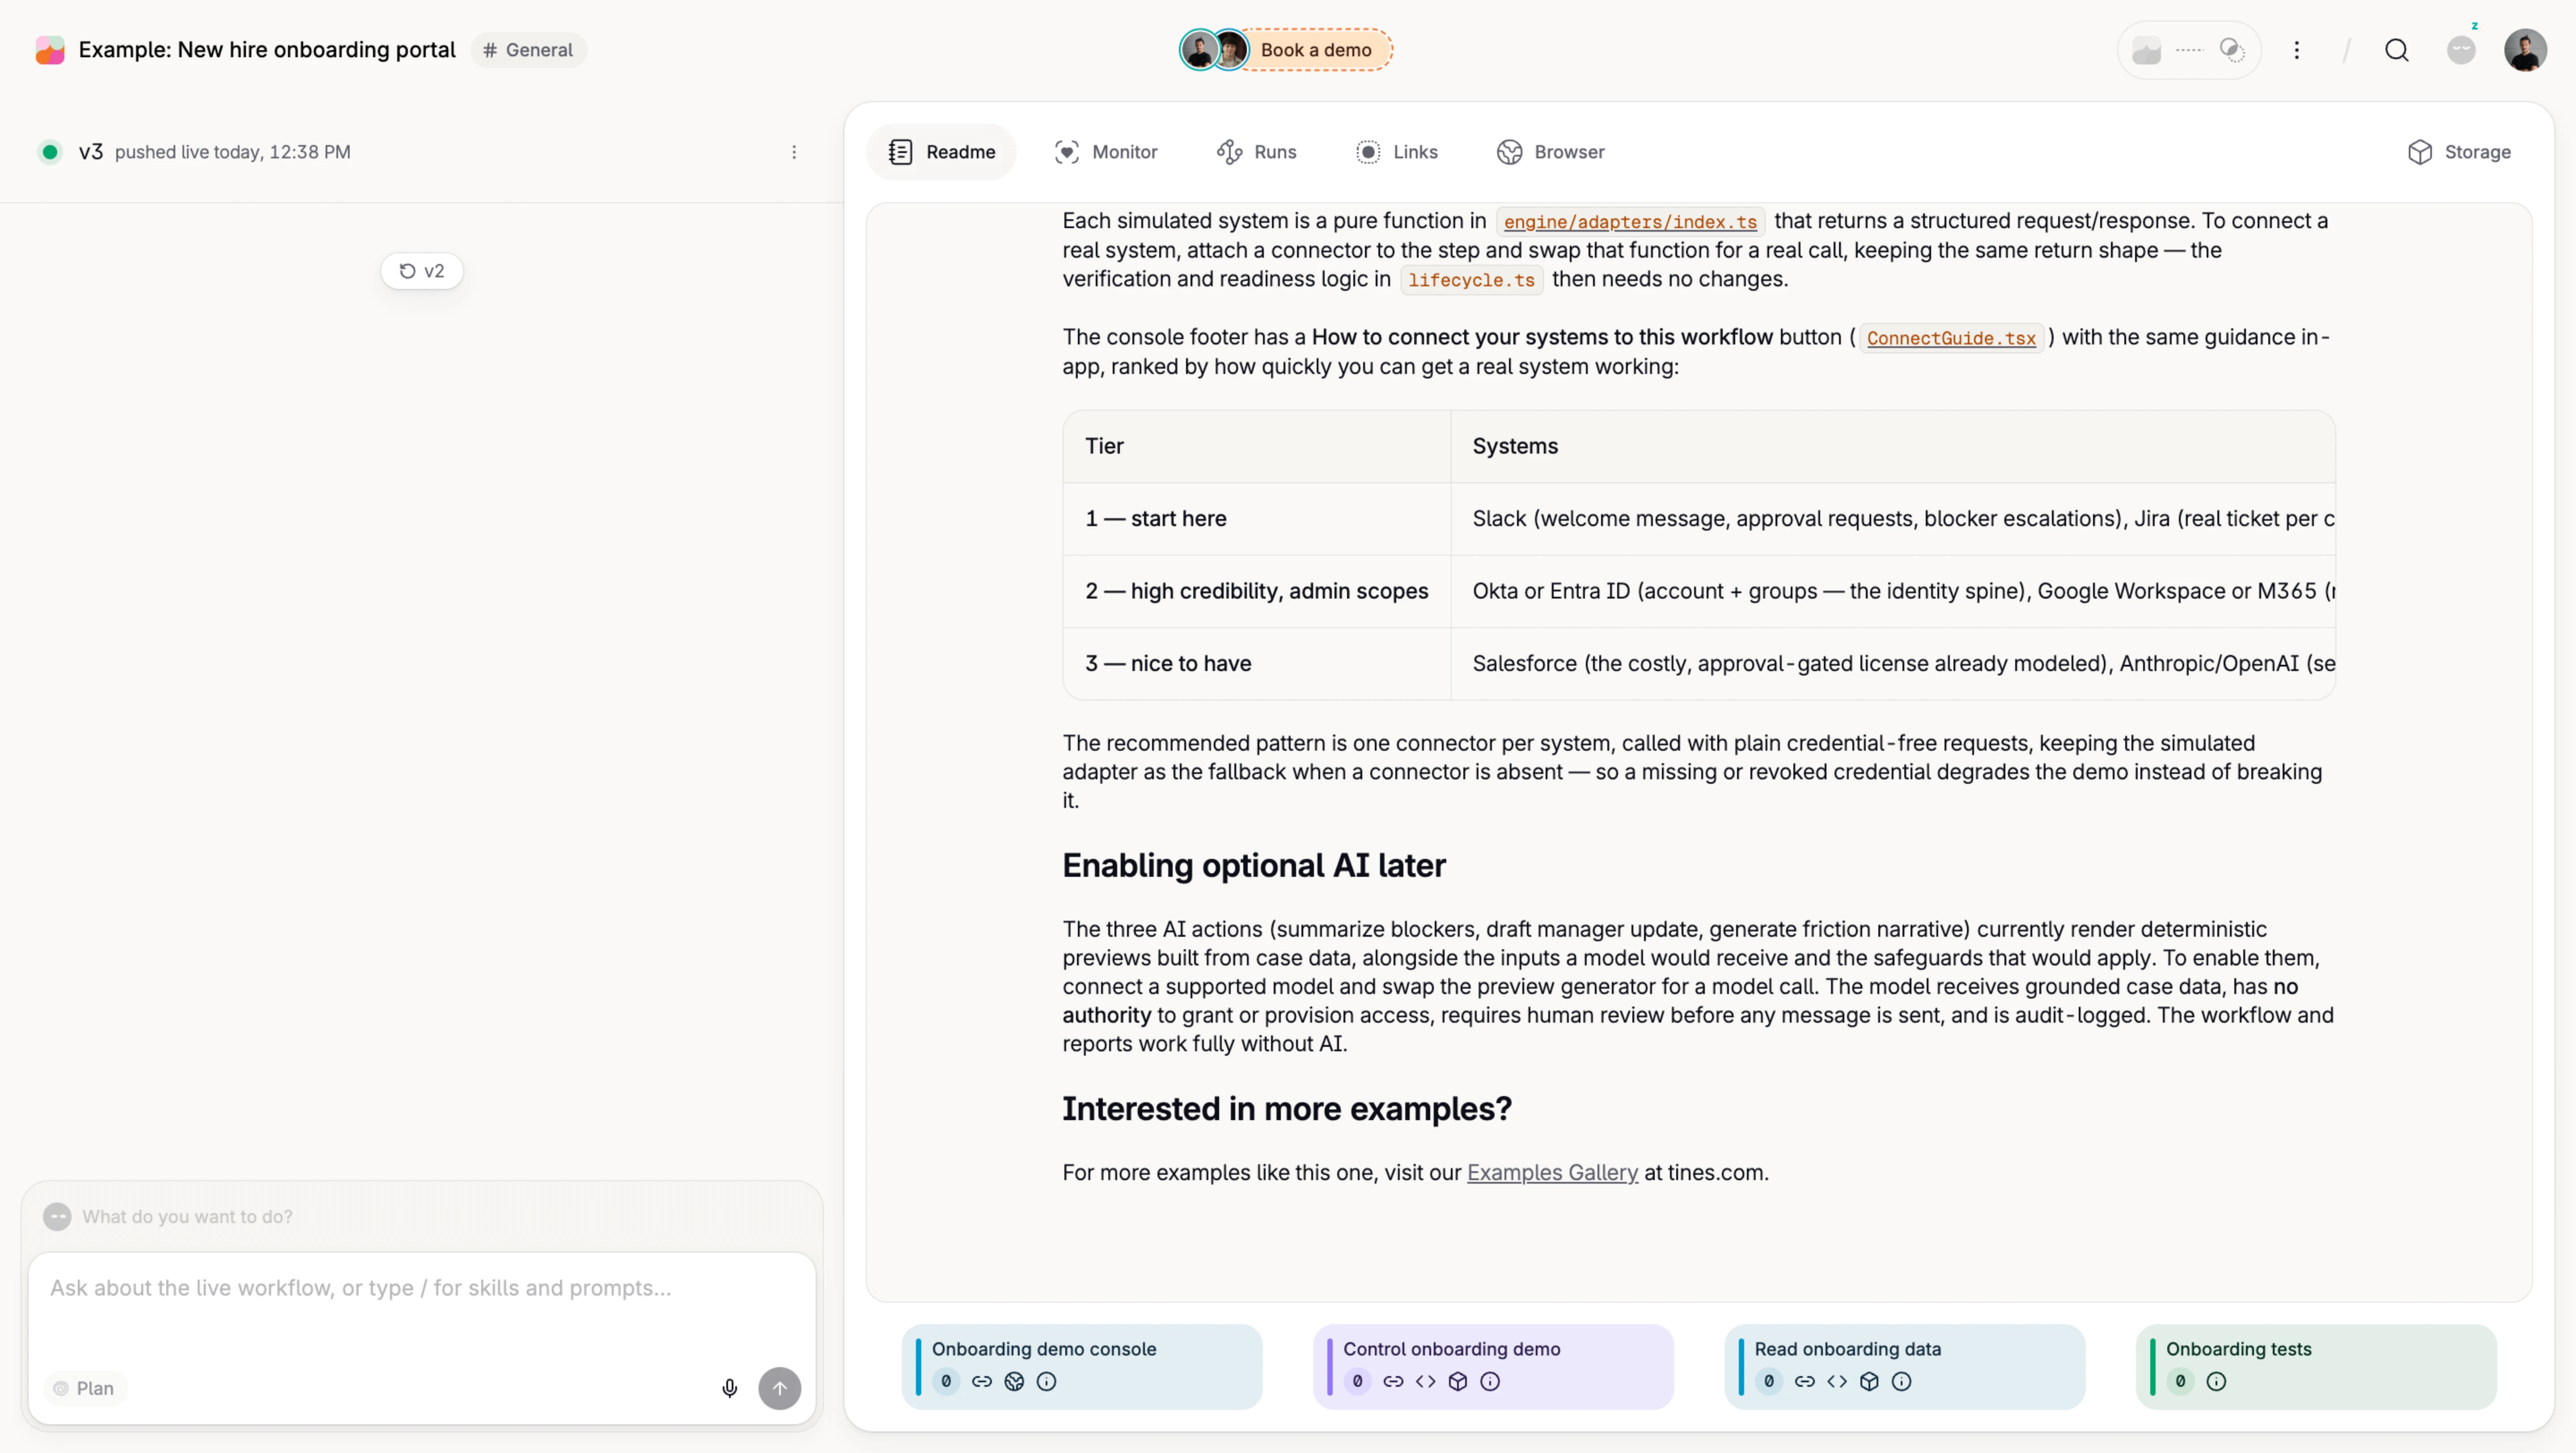
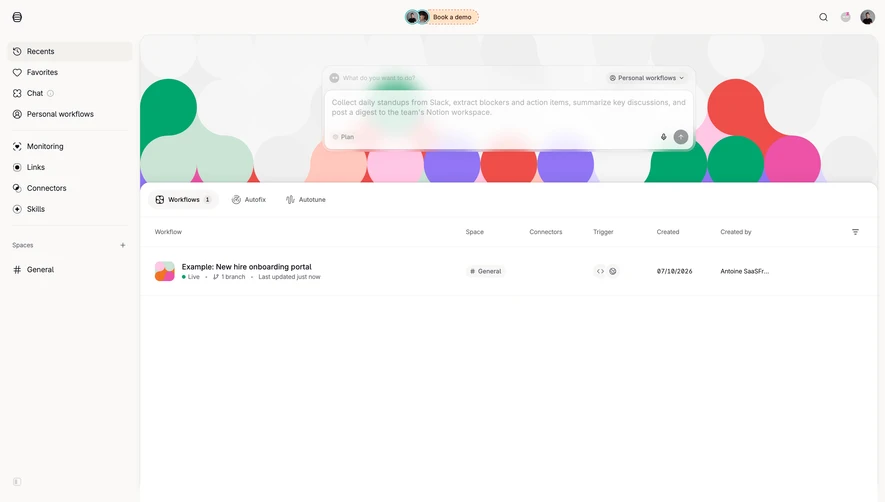
Workflow Workspace
Tines
Table
Product
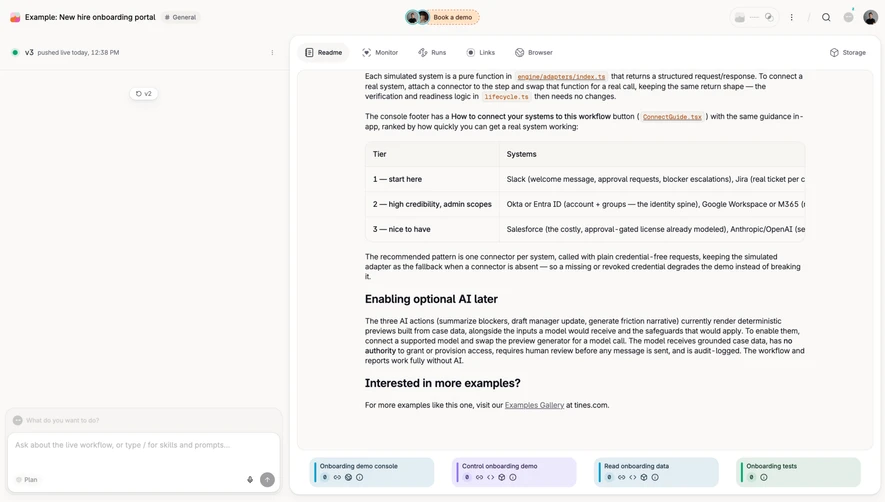
• Recents • Favorites & Chat • 8 Personal workflows Monitoring • Links • Connectors + Skills Spaces # General Book a demo a • What do you want to do? ® Personal workflows v Collect daily standups from Slack, extract blockers and action items, summarize key discussions, and post a digest to the team's Notion workspace. @ Plan 69 Workflows 1 @ Autofix N Autotune Workflow Space Connectors Trigger Created Created by Example: New hire onboarding portal • Live • 19 1 branch • Last updated just now # General 07/10/2026 Antoine SaaSFr...
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false
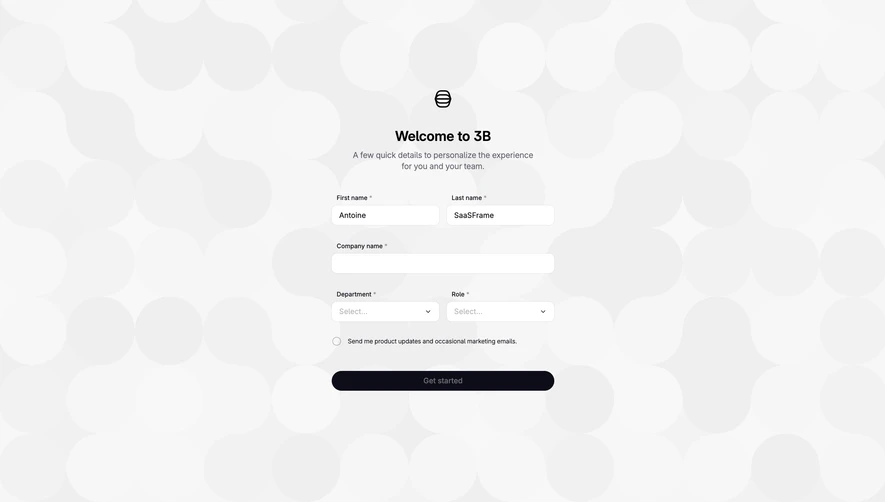
Account Profile Setup
Tines
Account Setup
Product
Welcome to 3В A few quick details to personalize the experience for you and your team. First name * Antoine Last name * SaaSFrame Company name * Department * Select... Role * Select... • Send me product updates and occasional marketing emails. Get started
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
false
Figma file available
Sign Up Options
Tines
Signup
Product
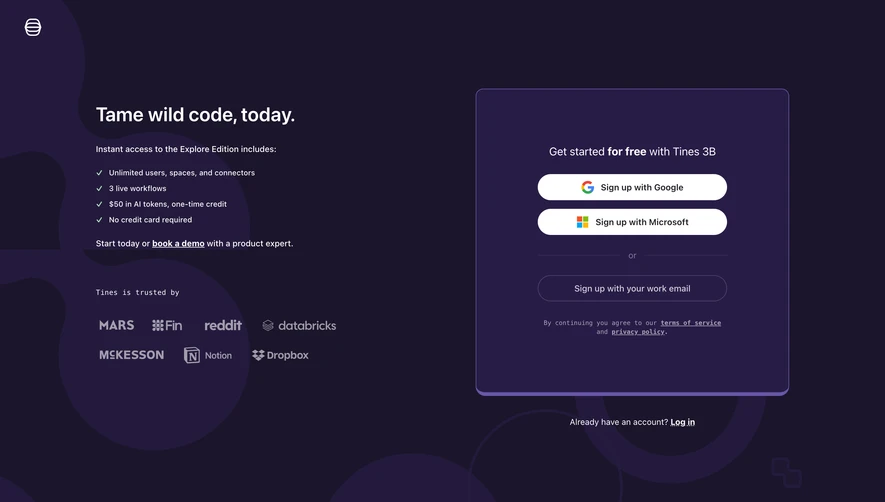
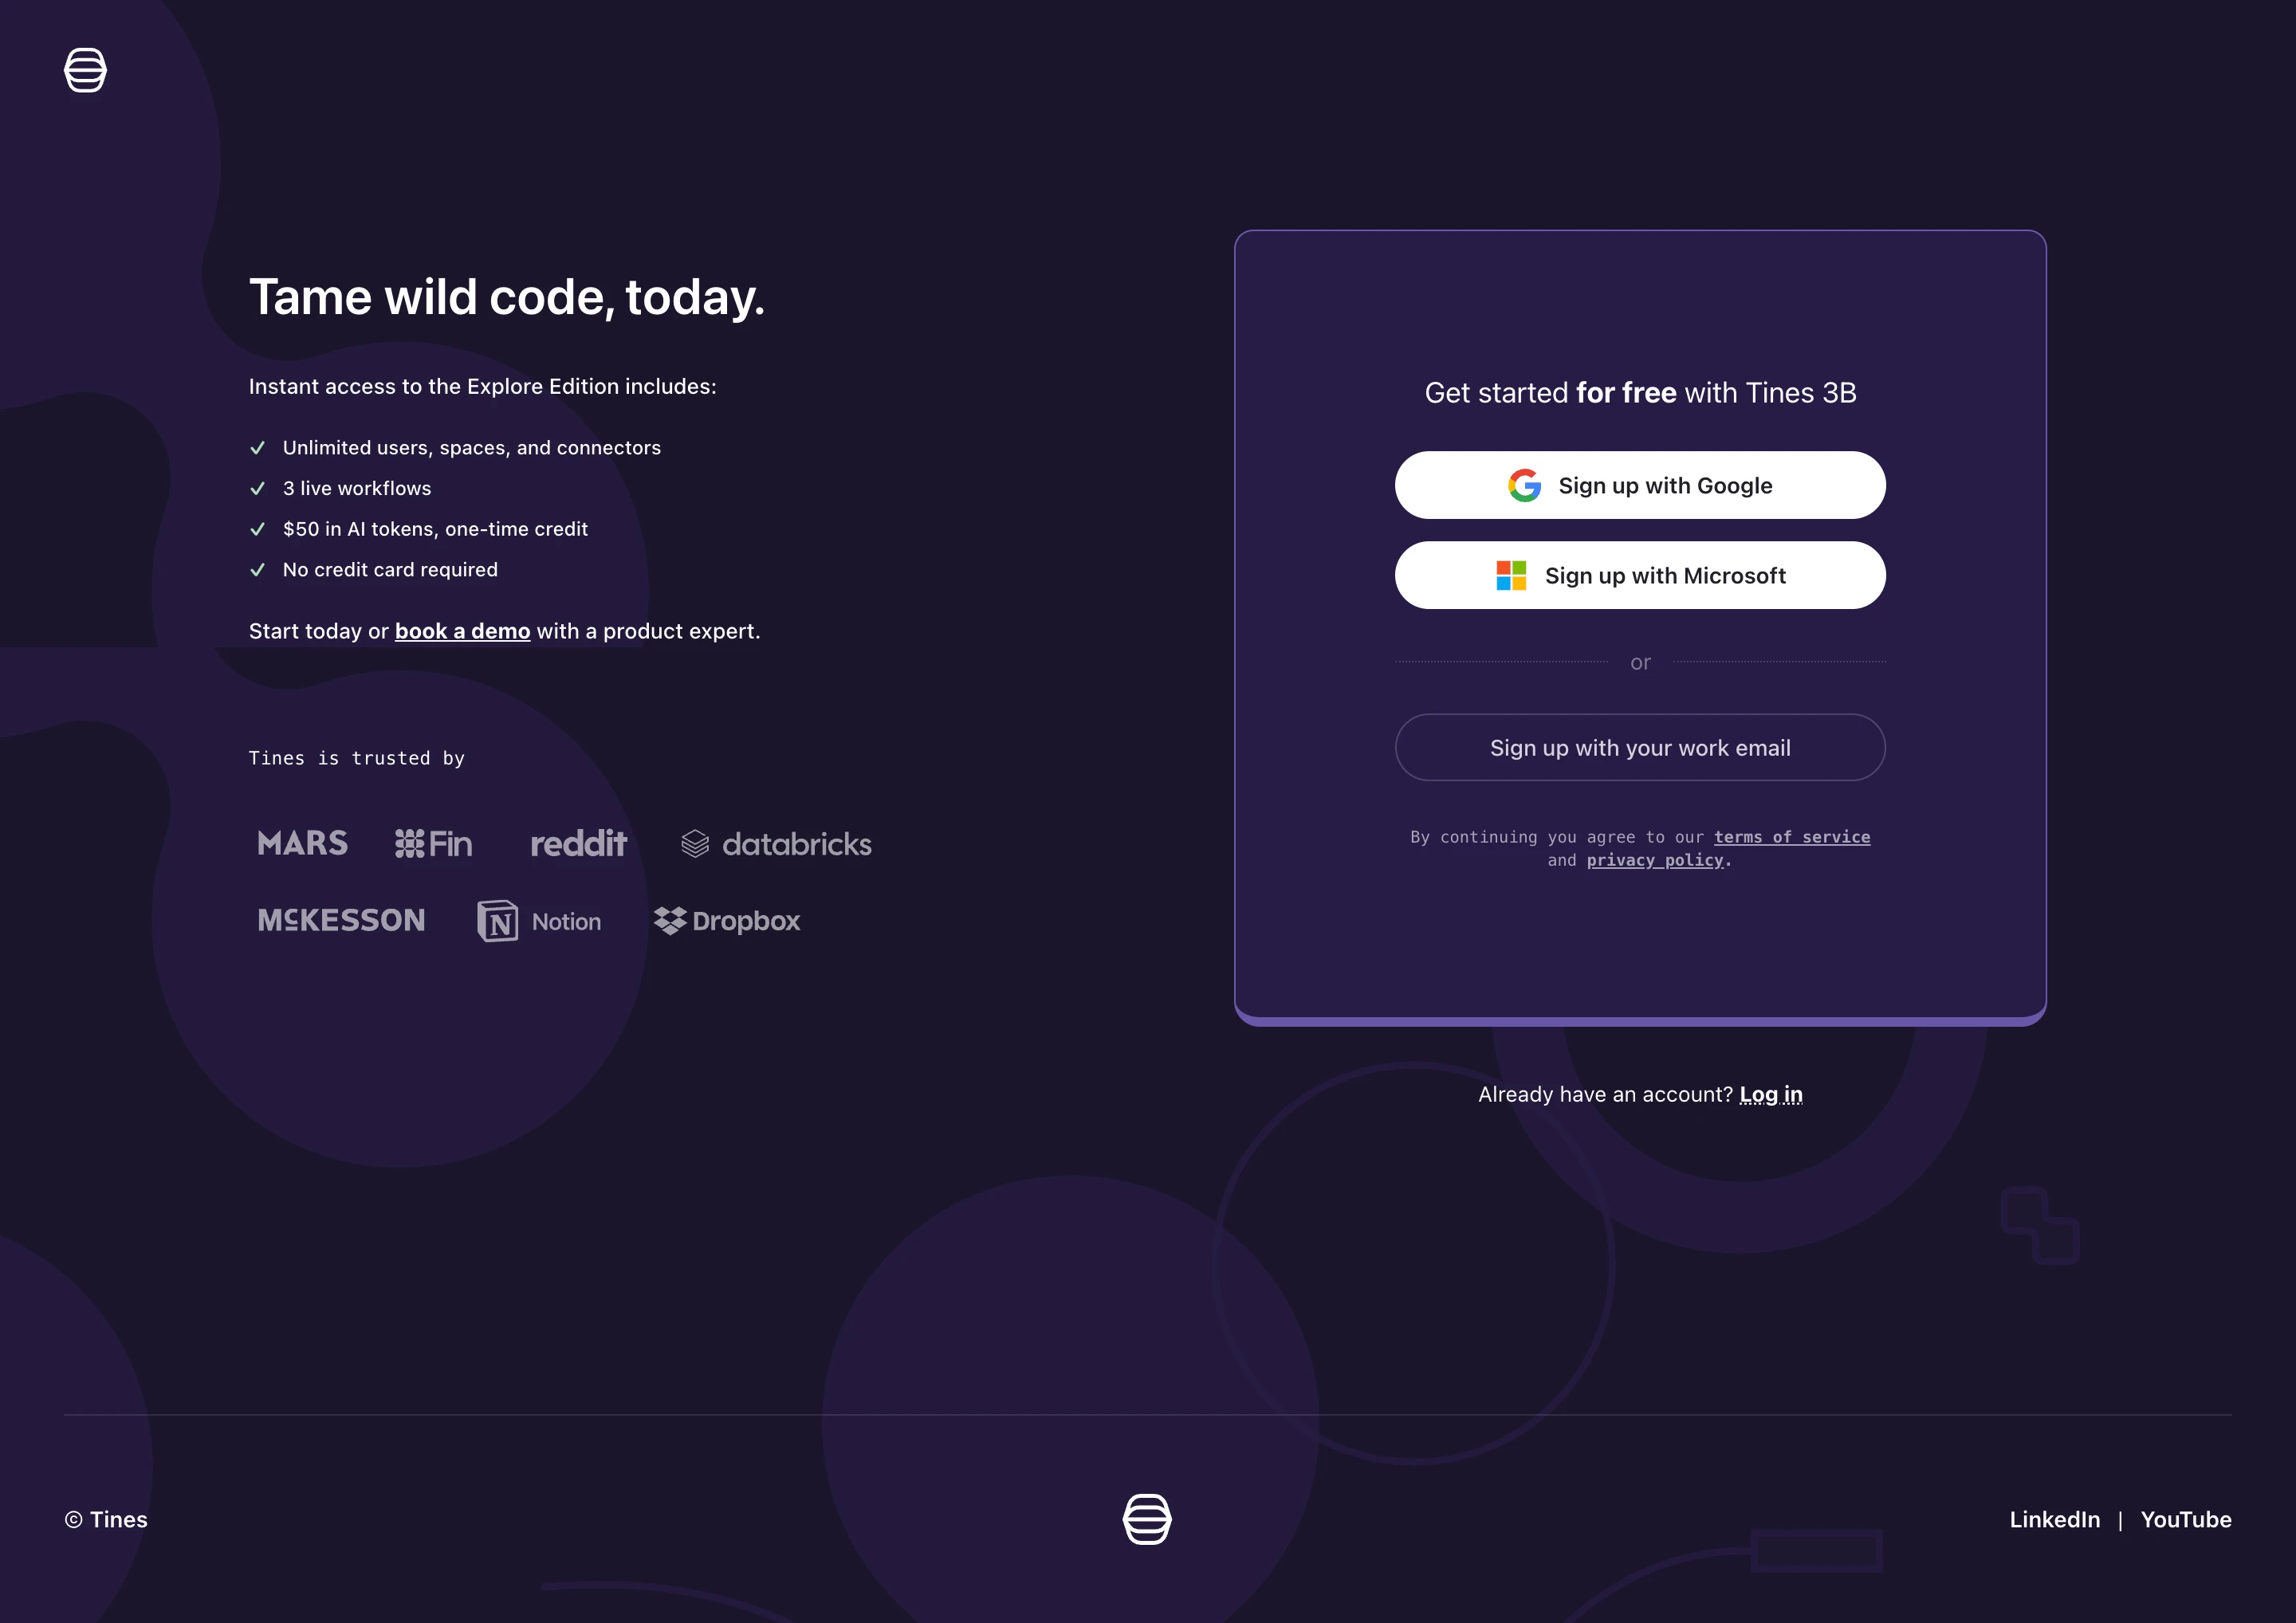
Tame wild code, today. Instant access to the Explore Edition includes: V Unlimited users, spaces, and connectors v 3 live workflows V $50 in Al tokens, one-time credit v No credit card required Start today or book a demo with a product expert. Tines is trusted by MARS MSKESSON reddit Notion • databricks · Dropbox © Tines Get started for free with Tines 3B Sign up with Google Sign up with Microsoft Sign up with your work email By continuing you agree to our terms of service and privacy_policy. Already have an account? Log in LinkedIn | YouTube
Workflow Automation
AI Agents & Assistants
Integration Platforms
No-code & Low-code
Cybersecurity & Threat Detection
true



Figma file available
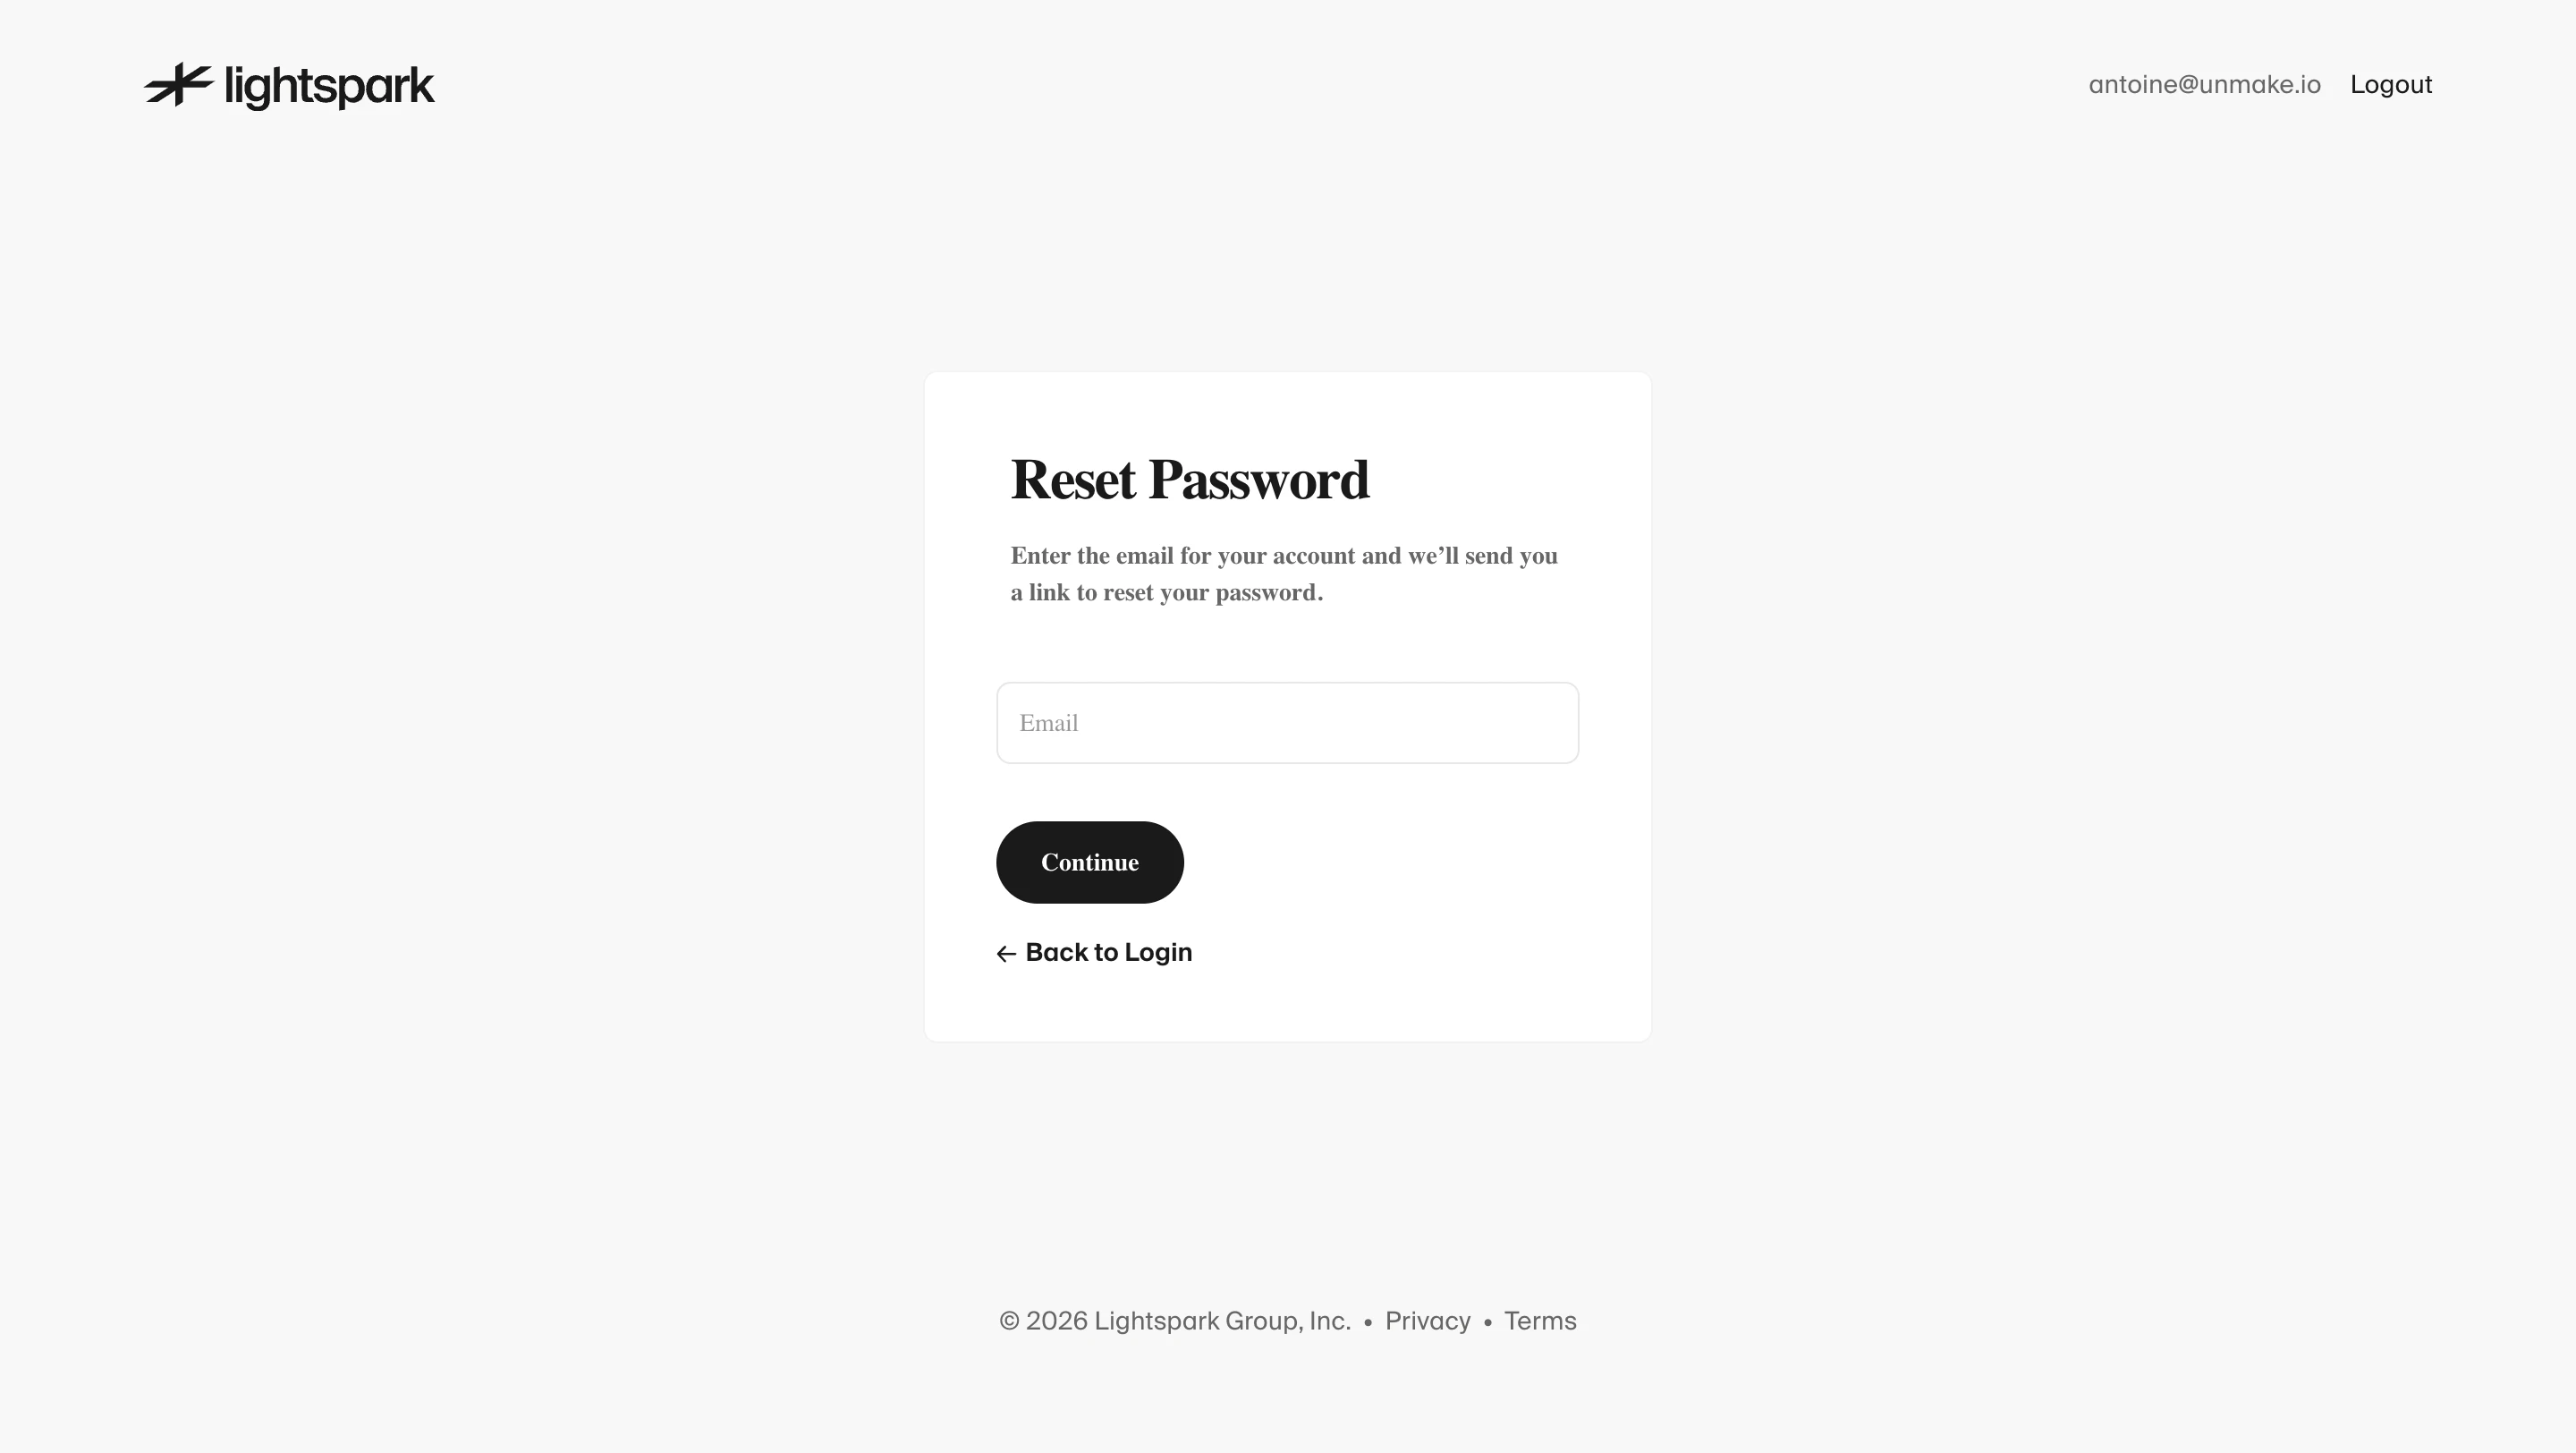
Password Reset Request
Lightspark
Login
Product
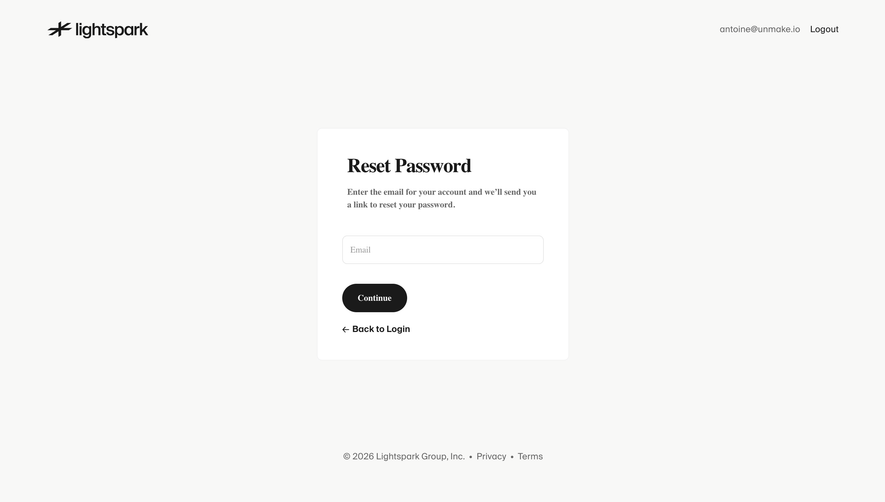
* lightspark [email protected] Logout Reset Password Enter the email for your account and we'll send you a link to reset your password. Email Continue + Back to Login © 2026 Lightspark Group, Inc. • Privacy • Terms
Payments & Invoicing
FinTech
Banking
true






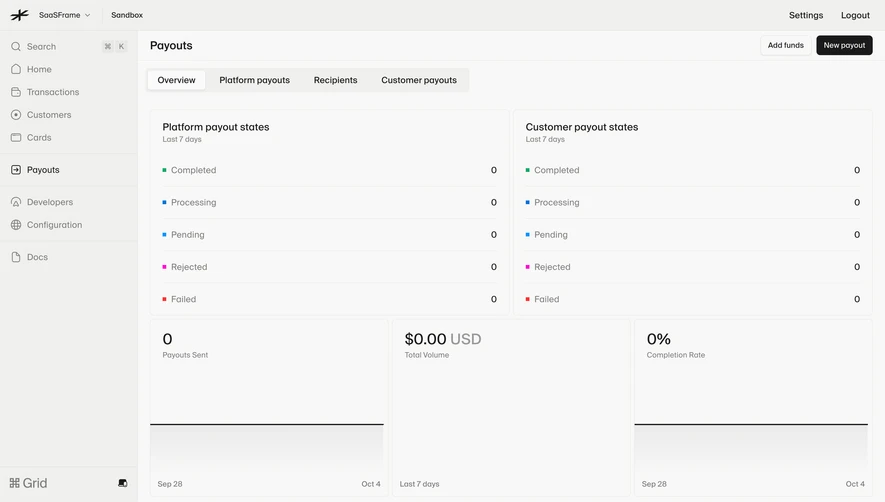


Figma file available
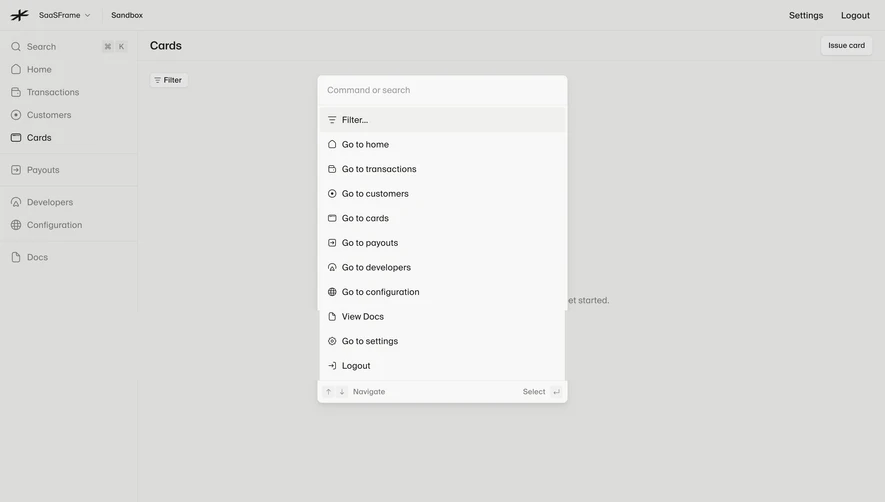
Cards Empty State
Lightspark
Empty State
Product
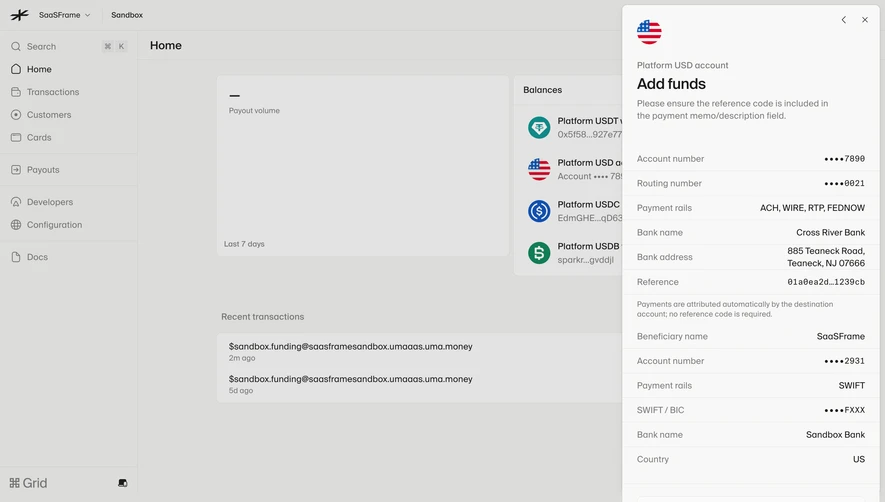
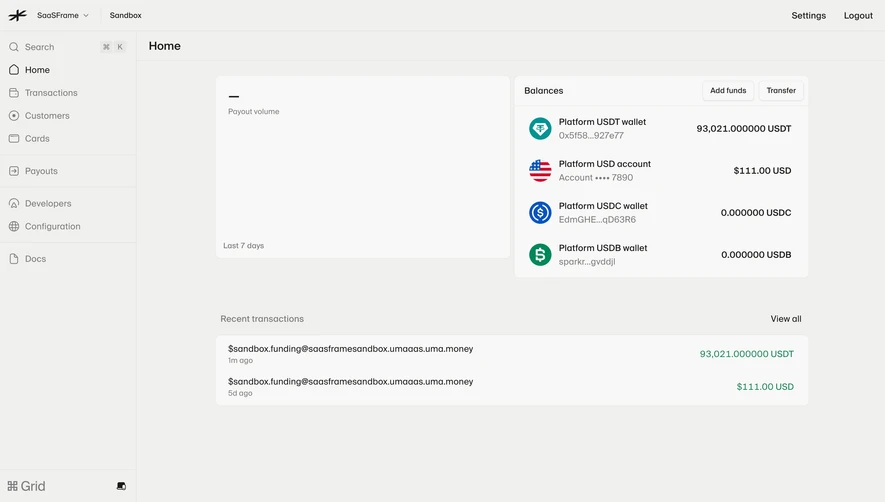
* SaaSFrame v Q Search • Home • Transactions • Customers • Cards • Payouts & Developers @ Configuration • Docs Sandbox 26 K Cards = Filter DE Grid Settings Logout Issue card No cards to show yet. Issue a card to a cardholder to get started.
Payments & Invoicing
FinTech
Banking
true










false